Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-08-10

Atlassian's Cloud +31% delivers the AI “attach” proof the enterprise SaaS market has been waiting for
In Q4 FY2026, Atlassian posted $1.766B revenue (+28% YoY) with Cloud revenue at $1.213B (+31% YoY) and $4.8B in RPO (+44%). The key investor takeaway isn’t another AI feature demo—it’s that Cloud acceleration is happening alongside AI-led product momentum, which changes how investors underwrite the monetization timeline from “promises” to “line-item traction.”
Australia turns rare-earth mining into a security-controlled asset class by ordering Chinese-linked owners to sell
Australia’s foreign investment enforcement is moving beyond export controls and into equity control for Western rare-earth projects. By freezing shareholder rights and ordering Chinese-linked investors to divest Northern Minerals stakes, the policy effectively re-prices the governance premium investors will demand for future funding and licensing in critical minerals.
Bristol Myers’ $2.3B Houston campus turns pharma reshoring into build-out of finished-goods capacity
Bristol Myers is committing about $2.3B to a new multi-modal manufacturing campus in Houston, with ~600,000 sq ft sized for small molecules, biologics and antibody-drug conjugates. Framed alongside Reuters’ “tariff threat” push, the investor takeaway is that the reshoring wave is shifting from announcements to hard, finished-product capacity—raising near-term demand for engineering, CDMO services, and lab/bioprocess tooling while compressing execution risk into 2027–2030 timelines.
China’s “domestic capital” AI doctrine makes US AI capex less dollar-dominant—look for memory suppliers to win while GPU capex gets quietly rerouted
Beijing’s $28T-style push to fund AI via onshore markets (with CXMT as the prototype) changes how capital is allocated: fewer “must-spend” dollar capex cycles for the US hyperscaler stack, more onshore production funding for bottleneck components. In parallel, DeepSeek’s reported fundraising pause highlights the other side of the doctrine—AI funding is now market-conditional, not subsidy-automatic.
CyrusOne’s 2027 IPO Signal Re-Ratings for “Independent” Data Centers—Because Lenders Are Making Financing a Valuation Variable
CyrusOne is preparing a potential 2027 IPO and has been in discussions with banks about roles, per Reuters. If that listing proceeds, it could force public-market re-pricing across the independent colocation/data-center stack just as tighter lender scrutiny makes leverage and refinancing risk a first-order valuation input.
Community opposition is becoming a credit risk—so lenders are shifting data-center financing toward “permit-friendly” states
A Reuters report says lenders are now explicitly folding community opposition into project readiness and drawdown risk. That turns NIMBY/permitting friction into an underwriting variable, which can reorder which markets and operators get built first—and who pays the higher cost of delay.
The Real Bottleneck Isn’t Rack Cooling—It’s the IP Stack Behind the Thermal Interface That Makes AI Chips Work
Discovered Materials’ AI-driven “whack-a-mole” approach to finding cooler thermal materials highlights how fast the industry has to iterate to avoid thermal throttling. But the investable constraint is upstream: the process, deposition, and materials IP that can manufacture new thermal interface layers reliably at scale—where Applied Materials sits and where materials suppliers like Shin-Etsu Chemical and Tokyo Ohka Kogyo are built to monetize.
Fisher’s AI-Infrastructure Crowding Trade Is Real—But It’s the “Grid-to-Aircraft-to-Network” Link That Should Matter for Investors
Fisher Asset Management’s latest 13F (quarter ended June 30, 2026) shows aggressive positioning across AI’s “real economy” buildout—power and electrification via GE Vernova, aerospace platforms via GE Aerospace, and enterprise/data-center connectivity via Cisco Systems, alongside the usual AI compute core. The investable takeaway is not that AI exists—it’s that Fisher is paying up for the bottlenecks and replacement cycles that sit between AI demand and the supply chain that fulfills it.
Hims & Hers turns subscriber growth into guidance proof—telehealth becomes a volume platform
In its latest earnings update, Hims & Hers reported subscribers rising to nearly 2.6M (+9% YoY) and raised full-year 2026 revenue guidance to $2.8B–$3.0B. The key investor takeaway is that the company’s top-line beat is now subscriber-driven—supporting a shift from “one-product GLP-1 cycle” risk to a broader telehealth platform with measurable, repeatable volume.
Instacart's ads are outgrowing transactions because grocery data still converts—so the retail e-commerce ad channel is “real demand,” not a funding-cycle artifact
Instacart grew Q2 2026 Advertising & other revenue +16% YoY while transaction revenue rose +13% YoY, with GTV +14% YoY—an uncommon retail pattern where ad-load expands without visibly harming order growth. The proof point is cash too: Q2 free cash flow surged to $480M (+156% YoY), making it harder to dismiss the ad acceleration as purely “spend-driven.”
Intel selling $15B of new stock turns the turnaround rally into dilution math
Intel’s proposed $15B common-stock offering (plus a $2.25B underwriter option) gives management capital for capex/working capital—but it also means investors are funding the foundry ramp with fresh share issuance at a high-price tape. The market implication is straightforward: even if foundry timelines improve, per-share economics get worse until operating leverage arrives.
Alphabet's talent exodus risk: investors should watch whether CEO-level AI capex and recruiting intensity rise after Jeff Dean-style departures
When Jeff Dean and other senior Google AI researchers left to launch [Discovery Loop], the headline wasn’t just a startup story—it was a signal that top-model talent can be a bottleneck that forces hyperscalers to spend more to stay competitive. Alphabet already shows heavy reinvestment capacity, but the market should now price in whether leadership churn increases hiring and compute-cost pressure at the company level.
UK calls Eli Lilly’s orforglipron “first in Europe” (10 Aug 2026)—and that sequencing risk compresses the EU/US GLP‑1 oral TAM while it’s still awaiting FDA/EMA timing
The UK’s MHRA authorized Eli Lilly’s oral GLP‑1, orforglipron (Foundayo), on 10 Aug 2026 as “the first country in Europe” for weight management and type 2 diabetes—before broader EU and US timing is locked. For investors, the key is not just access; it’s how an early UK regulatory imprimatur can reshape prescribing momentum, contracting expectations, and competitive sequencing while FDA review is still pending in the US.
Meta's Glimmer reframes AI capex as “agent infrastructure,” not a bigger chatbot
Meta is tying ~130B–145B capex guidance in 2026 to “AI efforts,” while launching Muse Glimmer as an open-weight, ~30B-parameter model optimized for always-on local agent workflows. The strategic implication is that Meta’s spend is increasingly rationalized by an always-running, user-specific agent loop—changing how compute, data, and distribution translate into revenue versus pure chatbot demos.
Microsoft's September Maia 300 reveal tests whether custom inference silicon can undercut NVIDIA without breaking the supply chain
Microsoft is signaling a next-generation custom AI accelerator (“Maia 300”) for a September public unveiling and 2027 deliveries. Its earlier Maia 200 already claims 30% better inference performance-per-dollar, so the real question isn’t specs—it’s whether Microsoft can scale volume enough to shift the inference cost curve and take share from NVIDIA’s full-stack economics.
Rocket Lab's margin signal is a satellite-mix test: Q2 gross margin rose to 36.1% even as space-systems revenue shifted
In Rocket Lab's latest quarterly filing, Space Systems delivered most revenue ( $189.5M of $234.1M total) while Launch Services shrank, yet consolidated gross margin still rose to 36.1% from 32.1% a year earlier. The investment question isn’t whether satellite sales are growing—it’s whether Rocket Lab can keep space-service unit economics from resetting margins downward when lower-profit satellite-heavy revenue mix shows up in quarterly results.
SpaceX’s First Retail Sell Turns the Mega‑IPO Regime Signal: When Mom‑and‑Pop Becomes a Source, Liquidity Stops Being One‑Way
SpaceX saw its first net retail selling in the post‑IPO era when mom‑and‑pop traders sold a net $4.5M of shares on Aug. 7, 2026 (first negative reading since the June IPO). That matters because the next wave of tradable supply is already scheduled via lockup expiries—starting with a major tranche eligible around Aug. 20—so sentiment can now amplify supply rather than absorb it.
The Trade Desk's real Q2 2026 ad-tech stress test wasn’t the 3% growth—it was executing a C-suite reset while guiding lower
In Q2 2026, The Trade Desk reported $715M revenue and non-GAAP EPS of $0.34—both short of what markets were looking for—and simultaneously disclosed an executive-leadership rebuild across CFO, CMO, and Chief Commercial roles. The key investor question isn’t whether growth missed; it’s whether the company can re-stabilize go-to-market and measurement execution as CTV/programmatic competition tightens.
2026-08-09
AI Power Spikes Are Forcing First-Order Capex Into UPS, Switchgear, and Generators—Turning Grid Reliability Into an OEM Supply-Line Shock
A new wave of AI power volatility is not just straining the grid; it is shortening the life and pushing the replacement cycles of batteries, generators, and cooling/power electronics inside data centers. That shifts the 2026–27 capex bottleneck from “build power lines” to “rebuild mission-critical power chains,” which can tighten supply and raise downtime-cost risk for operators and volume-forced production for OEMs like Eaton, Vertiv, and Generac.
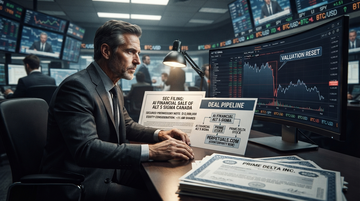
AI Financial's $12M exit implies “meme-to-impairment” contagion for crypto-linked payments and Perpetuals.com’s deal pipeline
When AI Financial sold its payments unit (ALT 5 Sigma Canada) for a $12M secured promissory note plus Prime Delta stock, the structure looked less like “growth strategy” and more like a liquidity/valuation reset. For investors watching Trump-linked fintech/crypto narratives, this matters because it converts prior upside hype into a concrete impairment-style event and turns counterparties like Perpetuals.com into the next holder of that risk.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.