Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-08-09

The “AI Safety Test” Is Turning into a Security & Disclosure Liability
When governments and frontier labs rely on opaque evaluation/test pathways, the act of testing can create new cyber and reporting attack surfaces. The compliance stack is being forced to move from “did we test?” to “how do we safely disclose, coordinate, and audit the tests themselves?”
Airbnb's 60% AI-Coded Engine Turns the Travel Stack Into an Agent-First Listings War
Airbnb is testing a natural-language AI search toggle while CEO Brian Chesky discloses that nearly 60% of new code is now AI-written — a productivity gap that lets the platform ship AI features faster than Booking Holdings or Expedia Group can copy them. The same shift forces every host to optimize listings for AI agents, not just guests, rewriting host SEO economics. With $27.2B in Q2 gross booking value at a 13.2% take rate and 35% adjusted EBITDA margins, Airbnb's AI velocity is the moat the incumbents have to chase, not the other way around.
Amazon's Pecos County gas plant permit implies ~33M tons CO2/year—so AI data-center siting is starting to behave like a carbon-forward power project
A planned Amazon-powered AI data-center campus in Pecos County, Texas is tied to an on-site natural-gas power plant permitted to emit up to 33 million tons of CO2 per year. That shifts the hyperscaler AI-capex trade from “compute demand vs. electricity availability” toward a carbon-cost and regulatory-liability problem that can change project economics well before the campus starts full operations.
Amazon’s Texas gas permit flips the AI power debate from “capacity” to “carbon cap”—and it makes the ESG discount a competitive advantage
A Texas air-permit authorization for Amazon-backed GW Ranch (Pecos County) contemplates emissions up to 33M tons of CO2e per year, turning AI “power availability” into an immediately measurable climate trade. The result is a reshuffling of who wins in the AI buildout: hyperscalers internalize the permitting risk, while grid and gas-infrastructure names with execution-ready capex ramps are positioned closer to the cash register.
Anthropic’s “global affairs” hire is the clearest proof frontier AI is being regulated like a geopolitical asset
Anthropic’s first Chief Global Affairs Officer, former California Supreme Court justice Mariano-Florentino “Tino” Cuéllar, formalizes something markets usually underwrite implicitly: government access and compliance bargaining. The appointment matters because it reframes frontier AI risk as a relationship-and-contract problem—after Anthropic has already faced export-control actions and helped shape California’s frontier-AI rules like SB 53.
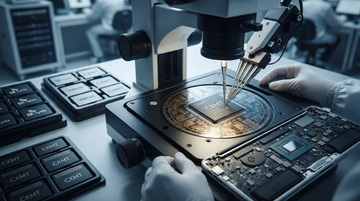
Apple's CXMT test isn’t a price story—it’s a sanctions-and-qualification story that can *stabilize Apple’s bill or strengthen SK hynix and Samsung’s pricing power
Apple is reported to have progressed to qualification testing of [CXMT] PRC DRAM for iPhone/Mac devices sold in China, while also engaging US policy for clearance. The first-order market implication is that CXMT can’t credibly undercut pricing yet, so the substitution “math” likely sharpens near-term leverage for SK Hynix and Samsung Electronics while raising a binary compliance risk for Apple’s sourcing pipeline.
Burry’s “Trump’s market” call lands right as Bank of America’s gauge hits “Extreme Bull” — a late-cycle warning built from breadth, leverage, IPO froth, and sentiment
Michael Burry’s Aug 8 “Trump’s market / price no longer matters” post arrives the same week Bank of America’s Bull & Bear Indicator hits 9.7 (“Extreme Bull,” above the 8 threshold). The investable takeaway is not “stocks are overvalued,” but that the mechanics of a late-cycle melt-up—crowding + positioning + credit/inflow optimism—are aligning faster than fundamentals can reassert.
China’s inflation cooled just as the Iran oil shock faded—creating the cleanest disinflation cross-current the market is still mispricing
China’s inflation slowdown is showing up right when the Iran-related energy impulse is unwinding, pulling commodity and energy-cost pressure off the table. For global markets, that matters because it weakens the “energy keeps inflation sticky” leg of the hawkish Fed narrative—especially when US goods deflation and energy-import-cost relief are moving in the same direction.
CLARITY Act’s 12-month slip pushes crypto regulation into a “fee-and-rail” trade: Coinbase waits on revenue, Circle waits on redemption rules, and Solana ETF math rolls to 2027
When the U.S. Senate effectively defers the CLARITY Act into 2027, the market doesn’t just delay “clarity”—it delays the stablecoin redemption/market-structure plumbing that determines who earns fees and who must re-architect rails. The result is a near-term Coinbase/Circle split (timing of exchange revenue vs. stablecoin reserve/redemption economics), while Solana ETF approval expectations migrate into a later regulatory window.
Cloudflare’s Q2 AI-Inference Guide Raised the “Toll” Value of the Internet Edge—So NET Repriced From CDN to Answer-Engine Infrastructure
Cloudflare used its Q2 2026 print to guide fiscal 2026 revenue to $2.864B–$2.870B and non-GAAP EPS to $1.25–$1.26, a combination the market treated like proof that AI inference traffic is accelerating at the edge. The read-through is that Cloudflare (and edge rivals) increasingly function as the “metering + policy control plane” for machine-to-machine traffic—not just a caching layer.
VKOSPI's two-month low signals the leveraged flush is cooling—and that’s when foreign rotation into Samsung Electronics & SK hynix can start working
Korea’s volatility gauge (VKOSPI) fell to a two-month low after forced deleveraging in single-stock leveraged products, while the KOSPI shed nearly 40% from its June peak. If this “deleveraging-over” phase is real, the next price action is less about panic selling and more about foreign capital re-pricing Korea’s memory leaders—starting with Samsung Electronics and SK hynix, not the US proxy names.
KOSPI volatility ebbed—but the AI-memory trade is now a different risk asset after leveraged flush
South Korea’s volatility gauge has fallen to a two-month low after forced liquidations and regulatory tightening on single-stock leveraged ETFs. The key implication for investors isn’t “risk-on returns”—it’s that the AI-memory complex’s tape is now shaped more by de-leveraging mechanics than by momentum alone.
Private Credit’s “Liquidity Premium” Took a Bank-Origination Shortcut—And the Squeeze Is Showing Up in BDC Math
Bloomberg’s Credit Weekly (Aug 8, 2026) links tighter private-credit economics to a specific borrower behavior: highly-indebted companies are refinancing out of private credit and back into the syndicated bank-loan market. For Ares Capital and Blue Owl Capital, that matters because it targets the very spread/rollover that BDC models were pricing as a durable “liquidity” advantage—when in reality, part of that premium appears to be bank-side underwriting structure.
Public support for age checks turns social-media compliance into a likely recurring Meta/Snap/Alphabet cost—58% just moved it closer to law
A Reuters/Ipsos poll found 66% backing laws that require age-verification tools, with 74% of Republicans supporting that specific mechanism. That demand-side political cover shifts age assurance from “mostly litigation risk” toward a more predictable balance-sheet line item for major platforms—especially where youth access is structurally large.

Sila’s $1.4B OSC conditional loan turns silicon-anode industrial policy into a direct, materials-led Pentagon procurement lever
On Aug 7, 2026 the U.S. Office of Strategic Capital (OSC) announced a $1.4B conditional loan commitment to Sila Nanotechnologies tied to expanding silicon‑carbon (Si/C) anode production and building lithium‑ion cell capacity. The strategic signal is that DoD/OSC is funding the next energy-storage stack at the materials bottleneck—before cells and primes—so investors should map winners to silicon-anode scaling, electrolyte/lithium refining, and US cell manufacturing.
SK hynix’s 18-Month Insider Sentence Doesn’t Target HBM—It Forces a New Audit Standard Across the Entire Memory Toolchain
An Aug 9, 2026 appeals-court ruling upheld an 18-month jail sentence for a former SK hynix engineer who leaked classified semiconductor manufacturing information to a Chinese firm. Even though the leaked technology described in the primary report concerns CMOS image-sensor manufacturing (not HBM specifically), the verdict functionally raises the compliance-and-audit bar for any memory supplier whose customer share depends on “trust.”
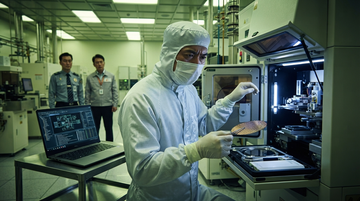
SK Hynix's 18-month jail ruling signals a new personnel-sensitive trade-secret standard for Samsung, Micron—and the AMAT/KLA/LRCX field-toolchain
A Seoul court sentenced an ex-SK Hynix employee to 18 months in jail for leaking semiconductor trade secrets to a Chinese firm, and the decision (as reported) explicitly rejects “light treatment” of leak crimes. The bigger investor takeaway is indirect: this case hardens how South Korea treats dual-use engineering knowledge—including off-site resumes/prints/photos—so tool vendors that embed with fabs must expect tougher export-control-by-personnel friction around memory/AI process data.
S&P 500’s Record +29% EPS Surprise Was Cyclicals-Driven—So the “AI Capex = Future Earnings” Trade No Longer Works the Same
The S&P 500’s biggest earnings beat on record (+29.2% vs estimates) can’t be explained by just the AI hyperscalers—removing Alphabet and Amazon cuts the surprise to 10.9%. That shift means the market’s next re-rating question is whether cyclicals can sustain earnings and cash flow without AI acting as the dominant growth narrative.
The DFC’s $3B minerals push is less about “materials” and more about buying 2027–2028 capacity blocks—MP Materials, USA Rare Earth, Energy Fuels, and Lithium Americas are the clearest US order-book fits
A verified Aug 7, 2026 package around critical minerals financing links to defense supply-chain bottlenecks, but the publicly accessible primary materials we can confirm name only a partial set of project participants. Using that confirmed deal/map plus listed-company capacity economics, the clearest “funding-to-offtake” winners are the US incumbents that can plausibly monetize demand under a 2027–2028 commissioning window—MP Materials, USA Rare Earth, Energy Fuels, and Lithium Americas—while the defense OEM names (e.g., Lockheed Martin and RTX) mainly matter as anchor buyers of qualifying downstream output.
Trump Media shut down its token and prediction-market bets—so investors must underwrite Truth API as the only credible cash-conversion layer
Trump Media & Technology Group DJT ended its Crypto.com token/tax-treasury pathway and pulled back from embedding prediction markets inside Truth Social, reducing the “financial-wrapper” optionality around DJT. The data business—Truth API—moves to the center because it monetizes distribution and speed (a tollbooth for market-moving posts) rather than operating risk markets or staking token treasuries.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.