Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-08-09

Ningbo’s shutdown turns Typhoon Dolphin into a timing-and-margin test for Apple, Nike, and PDD Holdings
Typhoon Dolphin triggered a suspension of Ningbo port operations on Aug 7 local time, with follow-on disruption across East China ocean and time-sensitive air freight. The investor-relevant risk is not just delays—it’s that missed replenishment windows force brands to choose between discounting, expedited freight, or inventory build, pressuring gross margin during the back-to-school freight cycle.
Ukraine’s drone strike on Russian refineries shifts the diesel story from “Iran/Hormuz risk” to hard supply destruction
By hitting two Russian refineries in a coordinated drone attack, Ukraine has targeted the part of the system that converts crude into diesel—tightening product availability and strengthening diesel crack spreads through lost runs. For refiners with product-heavy exposure, the investment implication is not just “war risk premium,” but whether incremental outages persist long enough to translate into sustained margins.
OFAC’s Aug 7 Shelbit Sanction Turns “UAE Iran-Crypto Compliance” Into a Bankable Risk Premium for Exchanges
Treasury’s Aug 7 OFAC action against Dubai’s SHELBIT GENERAL TRADING LLC frames a new enforcement surface: crypto “rails” used to support the IRGC and Nobitex. The second-order read-through is that any U.S.-facing exchange, wallet, or stablecoin on/off-ramp touching UAE OTC liquidity chains must treat “Iran-linked geo-compliance” as a material, tradable risk—not a reputational afterthought.
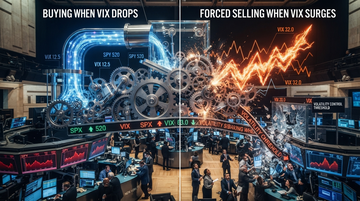
When cash floods the risk complex, volatility-control becomes the market’s real buyer—and that makes the next reversal asymmetric
A fresh wave of risk-asset inflows can look like consensus strength, but the marginal buyer can be automated volatility-control and trend-following CTA systems rather than discretionary capital. Those strategies have a documented pattern: they buy when the VIX drops and dump when it surges, so a cash-tide reversal can quickly turn into forced selling.
2026-08-08
Apple turns Alibaba Qwen into a China Mac distribution channel—iPhone was the pilot
Reuters says Apple’s China rollout lets eligible Mac users connect to Alibaba’s Qwen service via a macOS extension (macOS 26.6+), routing Qwen through Siri and Writing Tools for more detailed responses. That shifts the “Qwen for Apple Intelligence in China” story from a mobile-only monetization channel to desktop/enterprise workflows—raising the odds that Alibaba captures more downstream AI usage time (and thus higher Cloud/enterprise pull) alongside Apple’s China Services stickiness.
AppLovin's Q2 miss broke the “open access = upside” story—because its own model-driven auction timing still controls monetization
AppLovin didn’t miss on demand; it missed on timing, with management attributing the softer quarter to lighter-than-normal model improvement. That matters to the “open access / distribution” thesis because ad-tech economics clear through pricing/take-rate via auctions, not just incremental reach—so one weak quarter can vaporize the narrative even when the machine keeps growing.
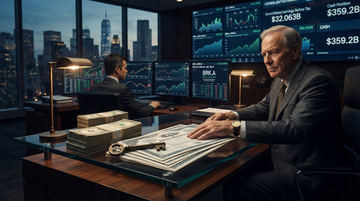
Berkshire Hathaway's Q2 cash use isn’t “patient”—it’s self-buyback at a size that forces the whole “cash mountain” narrative to update
In Berkshire Hathaway's Q2 2026 reporting, the firm shows operating-business earnings before tax of $14.376B and consolidated earnings before tax of $32.063B, alongside a clear cash deployment into buying back its own equity. The key reset is that cash, cash equivalents, and short-term U.S. Treasury bills were $359.2B at quarter-end—lower than where they stood at the start of the year—while treasury-stock purchases were material (most in Q2), implying the company is now returning capital through the same asset whose trade it’s marking.
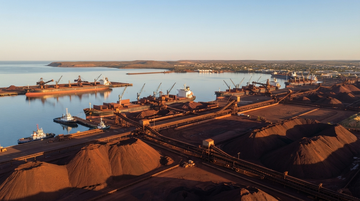
BHP’s Port Hedland 48-hour stoppage is a “steel-margin repricer,” not an iron-ore headline blip
A two-day protected action at BHP ’s Port Hedland Bulk Export Terminal starts with a 24-hour ship-loading ban (Aug 8) and then a 24-hour terminal stoppage (Aug 9). With the stoppages likely affecting ~800,000 metric tons of seaborne iron ore shipments per day, the shock hits steel input costs and downstream pricing faster than iron ore itself can mean-revert.
Treasury’s bond-auction mechanics don’t care about talking points—but they do re-route the 30Y buyer base
The clearest “backfire” signal in the next-30Y auction isn’t a headline yield; it’s the auction’s demand split. In the latest 30Y sale around the Aug 2026 window, non-dealers took 85% of accepted competitive bids, implying the marginal buyer is shifting away from traditional dealer behavior even when the accepted yield clears in a narrow band.
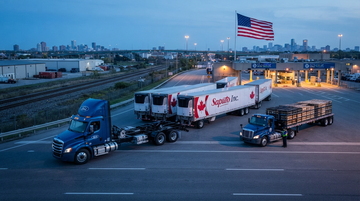
Canada’s Carney Concession Play Turns Section 338 Into a Sector Swap—Auto, Dairy, and Alcohol Winners Depend on Who Flips First
Under Section 338, the U.S. is imposing 50% tariffs on specific Canadian auto, dairy, and alcohol-linked categories with an Aug. 19, 2026 start date. Canada’s reported offer to trade relief—lifting retaliatory tariffs and ending U.S.-alcohol bans—in exchange for narrower U.S. tariff cuts changes the probability of resolution and re-routes near-term margin risk across North American supply chains.
Cloudflare turns the browser into agent compute—then prices the cost drivers (CPU/memory) inside Workers P&L
With Cloudflare’s Kitesurf (launched Aug 6), the “browser” becomes a stateless Rust engine running inside Workers, optimized for AI agent tasks rather than human browsing. The key economic tell is that Cloudflare reports materially lower CPU and especially memory than Chromium for common agent actions—shifting Cloudflare’s agent-compute revenue mechanics away from CDN/security toward browser-like workloads metered by resource cost.
DraftKings’ CEO didn’t hedge prediction markets—he argued they don’t work economically, and that reframes who owns the US iGaming TAM
DraftKings is building a predictions unit with explicit unit-economics assumptions (including low customer overlap and a plan to route more volume onto its own exchange), and that makes any operator pushback inside the sector unusually market-repricing. The key investor question now isn’t “will event contracts grow?”—it’s which iGaming revenue pools stay sportsbook-like versus which get structurally competed away by prediction-market infrastructure.
Framework turns an “all customers” breach into a board-ready enterprise cyber-insurance playbook
Framework’s disclosure that it notified all customers after attackers accessed customer contact data (via the Metabase cloud stack) raises the bar for consumer-hardware incident handling. The commercial signal is that cyber risk is moving from “best-effort security” to measurable, insurer-grade documentation—creating knock-on pressure for OEMs’ vendors (like Dell, Lenovo) and for insurers/reinsurers such as Chubb to price modular supply-chain exposure.
Hadrian’s $1.37B at a ~$7.87B valuation signals defense manufacturing is the new capital magnet—and it pressures software-multiple investors that can’t show factory throughput
Hadrian (private) raised $1.37B at a $7.87B valuation to scale “factories-as-a-service,” with explicit capacity moves for munitions, shipbuilding, and submarine-component production. For listed defense primes, the real test is whether new factory capacity can convert into deliverable, margin-protecting production schedules—while “autonomy-only” winners face longer cash-conversion paths.
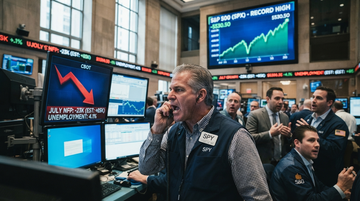
Negative payrolls, record stocks: the July -23K print didn’t just move Fed odds—it rewired the “hike vs cut” path for September
A -23K July nonfarm payrolls print (vs. +85K expected) forced investors to price September policy more aggressively toward action—yet the S&P 500 still pushed to a record high. The paradox is mostly about sequencing: markets treated the jobs shock as disinflationary “growth risk,” while Fed-hawk narratives must re-earn credibility through wage/inflation data before they can justify late-cycle hikes.
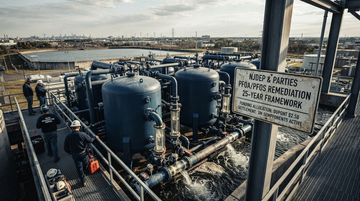
NJ’s $2.5B PFAS deal turns “forever chemicals” into a funded balance-sheet item—and rewrites who bears the next wave of US water risk
New Jersey’s court-approved PFAS settlements with DuPont (plus its spinoffs) and 3M convert open-ended “forever chemical” liability into scheduled, allocable payments through a 25-year remediation framework. For investors, the immediate read-through is less about one state getting paid—and more about how the payment+trust model pressures insurers, reshapes utility capex planning, and strengthens the enforcement pipeline across the US water system.
Nvidia’s $3B Lancium Bet Turns Stargate Into a Power-Site Landlord Play—Not a GPU Story
The key market constraint behind Stargate-style AI buildouts is shifting from GPU availability to multi-year power + grid interconnect lock-up. Nvidia’s $3B-scale equity commitment to Lancium (the power infrastructure developer tied to Stargate) matters because it anchors the “AI grid” that determines where compute can actually be deployed.
OpenAI’s “Critical Cyber” threshold turns AI-safety into a security-vendor compliance stack—creating a new 30-day-style review process even without a “kill switch” law
OpenAI’s Aug 7 post on “Responding to the next frontier of critical cyber capabilities” defines when a frontier model can perform end-to-end novel cyberattack strategies, and says it is strengthening/pausing releases and agent workloads accordingly. That threshold reframes AI safety from “model behavior promises” into a test-and-controls gate—one that can force security vendors and evaluators to operationalize compliance via measured exploitability and environment isolation, not just policy statements.
[OpenAI]’s [NextSlide] acquisition signals the productivity-stack era: ChatGPT is becoming the “AI-native Office distribution layer”
OpenAI’s Aug 2026 move to bring the [NextSlide] presentation team into the [OpenAI]/[ChatGPT] product suggests the next growth frontier is vertical workflow SaaS—starting with the work of turning ideas into decks. The deal’s disclosed specifics are thin, but the direction is testable: Microsoft and Alphabet can’t defend Office and Workspace UX with model access alone, they must out-execute on AI-native creation and formatting loops.
OpenAI’s $300–$400 Smart Speaker Trade: a voice-first margin switch that forces retailers and phone ecosystems to pay for access
A leaked report places OpenAI’s first consumer device—a screenless, donut-shaped AI speaker—at ~$300–$400 and suggests a 2027 entry. For investors, the key question isn’t “will people buy it?” but “who funds the margin bridge from OpenAI API to an always-listening voice edge in the home,” with likely knock-on pressure for Apple (ecosystem control) and Sonos (connected-audio relevance) while Amazon monetizes shipping distribution.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.