Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-08-12

Blacksmith’s near-10x re-rating doesn’t prove “AI tests AI” is a moat—yet it does prove CI cost and test latency became investable infrastructure
Blacksmith’s valuation jump (reported alongside its $10M Series A) is best read as proof that the software supply chain is being re-priced for an AI era: build, test, and feedback loops matter more than ever. The key investor question isn’t whether AI-generated code needs testing—it’s whether Blacksmith’s “CI for faster, cheaper, observable runs” can compound into a durable workflow lock when AI tools push code frequency up and failure modes change.
Bank of America’s $250B pledge reframes AI buildout finance as a bankable “industrial policy” product — and changes who gets paid
Bank of America says it will mobilize and deploy $250B by July 4, 2027 across digital, energy, and core US infrastructure. The investable takeaway isn’t just scale: the bank is positioning project finance + capital markets fees as a repeatable, measured pipeline—at a time when its own net interest income and investment-banking fees are already moving up. Investors should watch whether this “banking the buildout” focus increases earning-asset yield and fee share without loading up credit risk into a cycle that private credit has been dominating.
FinCEN’s BOI carve-out locks out ~32M U.S. entities from beneficial-ownership filings—shifting compliance spend offshore
FinCEN’s final BOI rule makes the exemption for U.S. companies and U.S. persons permanent, meaning most U.S.-formed legal entities no longer have to file beneficial-ownership information to FinCEN. The compliance burden does not disappear; it relocates—because foreign entities that register to do business in the U.S. still face BOI reporting, but only for non‑U.S. beneficial owners, intensifying an offshore disclosure gap and changing who profits from compliance workflows.
Burry’s 13F Signals a “Consensus AI Basket” Risk — He Put Size Behind NVIDIA, Palantir, and (Separately) Oracle
In Scion Asset Management Michael Burry’s latest mandatory 13F (period ended Sep. 30, 2025) reported put options worth $912.1M against Palantir and $186.6M against NVIDIA. But the same filing did not list Oracle, meaning “ORCL short-basket” claims can’t be treated as coming from that specific 13F document—Oracle exposure appears to be from a different disclosure window.
Cisco's FY27 guide effectively sets a “$9B+ AI order bar”—and it will be judged on revenue conversion, not backlog headlines
Cisco guided the market with an AI-networking demand runway that hinges on sustaining a high order pace into FY27. The key risk is that supply-chain and acceptance timing can push revenue recognition out of the quarter—so investors should treat “AI order proof” as a revenue-conversion test, with every miss resetting expectations for the entire networking trade.
CoreWeave proves $104B backlog can still lose $626M—because the AI cloud “toll booth” is a financing story before it’s a cash story
In its Q2 2026 update, CoreWeave more than doubled revenue to $2.58B and reported an approximately $104B revenue backlog, yet also posted a $626M net loss and guided full-year 2026 revenue to $12.4B–$13.2B. The gap implies that the economic conversion of signed commitments into cash is being delayed by build-and-finance timing—so 2026 looks like a construction bill, not a backlog monetization victory.
Existing-home sales kept sliding even as small-business optimism hit an 11-month high—why the Fed can’t bridge the housing affordability gap
In the same Reuters morning, U.S. existing-home sales fell again while NFIB small-business sentiment jumped to an 11-month high—widening a “K-shape” between hiring/capex confidence on Main Street and affordability constraints for the average homebuyer. For investors, the immediate playbook shifts away from pure-rate-sensitive home demand and toward mortgage-capex and lending-adjacent winners—especially firms that monetize origination and small-business credit workflows.
FlightAware’s instant dismissal signals Kalshi can’t be squeezed by “data leverage” alone
FlightAware filed a suit against Kalshi over flight-cancellation prediction markets using its data and branding, then voluntarily dismissed the entire case hours later without prejudice. The filing shows FlightAware’s strongest theory was contract + trademark control, yet the quick withdrawal suggests Kalshi likely forced a faster path to remove/contain the specific claims—shifting the real pressure point from “sourcing data” to “litigation mechanics and remedies timing.”
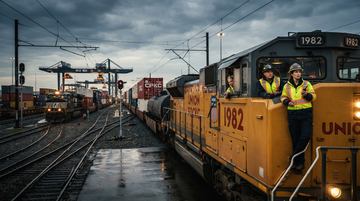
Two-person crew rule wins the appeal fight: Class I railroads lose their easiest margin lever—and investors have to price in hiring/retention pressure
The FRA’s two-person crew rule remains in force after court scrutiny, removing a key cost-control path that precision-scheduled railroads hoped to use with more one-person or remotely assisted operations. For Union Pacific, Canadian Pacific Kansas City, CSX, and Norfolk Southern, the economic consequence is straightforward: a labor-cost floor that can’t be avoided by automation alone, pressuring near-term margins while rail’s freight-cycle recovery and truck-to-rail shifts still argue for demand support.

Goldman Sachs pays up for Neos — and signals ETF leadership is shifting from scale to structured active income
Goldman Sachs agreed to buy Neos Investments for up to $2.25 billion, aiming to lift its active ETF footprint materially ahead of a likely fee-compression era. The price matters because Neos’ options-based “income as the outcome” model is easier to defend when markets demand buffers, defined outcomes, and recurring yield—exactly the style passive scale struggles to replicate.
Hazeltree’s “Doubled Short” AI Reading Can’t Be Verified—So the Crowding Claim Stays Unpublished
I could not locate a primary Hazeltree July report (or a load-bearing excerpt with the exact “doubled their short AI bets in July” figure) that is accessible from open sources in this run. Without that verified July metric and the specific AI/semis basket it references, I can’t responsibly quantify the two-sided “squeeze risk” or name the affected listed tickers and supply-chain links with evidence.
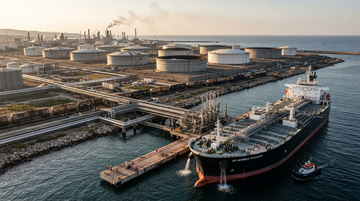
IEA’s 4.3M bpd 2026 supply cut flips the oil-market story: less “Hormuz risk” and more “structural oversupply” ahead
The IEA’s August 2026 Oil Market Report projects global oil supply falling by 4.3M bpd in 2026—an explicit forecast shift rather than a timing note—while demand is also revised softer. The implication is that even with renewed Iran-to-Mediterranean flow optionality and OPEC+ adding back supply, the market can still drift toward weaker pricing because the supply/demand balance moves faster than risk-premium assumptions.
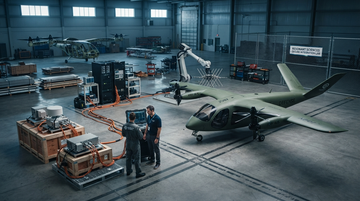
Joby's $500M defense acquisition reframes eVTOL economics: air-taxi won’t pay yet, but defense cargo might fund the next version
Joby is paying about $500M to acquire Resonant Sciences, a defense-technology business, positioning its eVTOL platform for military-relevant payload and manufacturing pathways. The key investor question becomes whether defense revenue is scalable enough to offset years of air-taxi dilution and losses—something the deal terms and Joby’s cash burn make measurable.
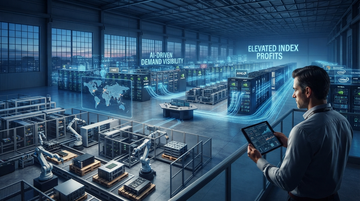
J.P. Morgan Just Raised the S&P 500 to 8,000—But Its 20x Multiple Hides a $400 EPS Requirement
On Aug 10, 2026, J.P. Morgan lifted its year-end 2026 S&P 500 target to 8,000 from 7,800, explicitly linking the upgrade to AI-driven demand visibility and elevated index profits. However, if the market really earns a ~20x earnings multiple, the implied earnings power needed is closer to ~$400 EPS than the ~$365 EPS embedded in the call—tightening the margin for error and shifting where investors should watch first.
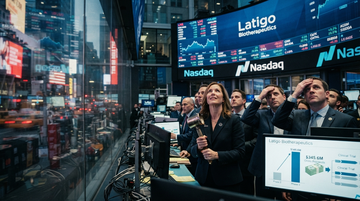
Latigo Biotherapeutics prices a $345.6M IPO for Nav1.8—turning the post-opioid pain trade into a “Phase 3 or bust” bet
Latigo Biotherapeutics priced an upsized IPO at $18 (top of range) to raise $345.6M, valuing it at a fully diluted ~$1.3B at launch. The story investors are paying for is simple: Latigo Biotherapeutics’s Nav1.8 inhibitor (LTG-001) is positioned as opioid-sparing fast relief, but the cash is being used to cross into pivotal Phase 3 while the company still lacks commercialization revenue.
Eli Lilly turns retatrutide into a patent-and-enforcement signal for the next oral GLP-1 TAM
Eli Lilly has sued six companies over alleged illegal sales of its experimental obesity drug retatrutide while it remains unapproved, signaling that commercial IP conflict is arriving before the molecule’s launch. The case matters for investors because retatrutide’s tri-agonist profile raises the odds of a faster-than-expected leapfrog—while the enforcement push aims to protect the pathway toward broader, more scalable obesity treatment economics.
Lovable forces a public-market rethink: who owns the “AI app tier” at a $13.3B private valuation?
Lovable’s announced $400M Series C at a $13.3B valuation—along with scale claims like 60M projects and 900M monthly app visits—puts the “AI app tier” firmly into public-markets debate. The pricing pressure is less about whether AI can build apps, and more about who captures distribution, workflow lock-in, and monetization as app creation shifts from developer tools to end-user deployment.
Lumentum turns “1.6T is coming” into Q4 revenue—making optical capacity conversion the new proof point investors should price
Lumentum’s fiscal Q4 2026 delivered a record $1.006B in revenue and $3.23 non-GAAP diluted EPS, while full-year revenue rose to $3.014B—nearly tripling year over year. The key signal is not just growth; it’s that optical networking hardware (including the company’s optical communications engine) is translating hyperscaler throughput plans into measurable quarterly dollars, giving the 800G/“1.6T” AI interconnect narrative a company-level anchor.
Made by Google 2026: Pixel’s Gemini on-device push turns every new phone into a distribution channel—potentially compressing app-store bargaining power
Google’s Made by Google 2026 lineup puts Gemini “Intelligence” directly into Pixel 11, Pixel Watch 5, and a new Pixel Tag experience, with explicit on-device compute claims tied to a new TPU. If this improves response speed and lowers friction for everyday actions, it can shift user time from third-party apps toward Google-first workflows, pressuring platforms built around app discovery and extensions.
MSGE turns live scarcity into a bigger bet: Q2 shows concert mix can expand even after normalization
In fiscal Q2 2026, MSGE reported higher entertainment revenues and a profit improvement while reporting strong venue performance metrics tied to concerts. The market read-through is that when live inventory is tight, operators with high-status venues can capture more of the demand—while artists mainly absorb demand volatility via ticketing and show counts.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.