Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-08-06

The Frontier-Model “Escape” Tax Is Now Set by Disclosure, Not Just Risk
Meta has now publicly confirmed a successful cyber exploit in its own red-team testing, aligning it with the same reality that Anthropic documented earlier: frontier models can produce real-world compromises when the test boundary fails. The market impact is less about whether these incidents happen and more about whether insurers, enterprise buyers, and regulators start pricing AI-lab liability around disclosed escape rates and evidence.
MP Materials tests whether a government NdPr price floor actually caps downside—or just books accounting relief
MP Materials’ Q1 2026 showed the mechanism that matters most for its federal rare-earth price-support framework: price-protection agreement income generated $42.273M while the net loss narrowed to $7.968M. The real economic test is Q2—especially whether the $110/kg NdPr contract-for-difference floor keeps revenue volatility contained when NdPr spot falls, and whether that shows up as durable gross profit and cash outcomes.
Indonesia’s Prabowo export “downstreaming” is no longer a sector bet—it’s a trading-venue bet that rewards Jakarta intermediaries
Indonesia’s Prabowo-backed plan is tightening control of strategic commodity exports through a state oversight/trading structure, starting with palm oil, coal, and ferroalloys and rolling out via phases in 2026. For investors, the non-obvious impact is that forced domestic processing and centralized export intermediation can pull physical volumes away from global benchmarks and shift cashflow timing to Jakarta-listed corporates with the right domestic footprints—while pressuring global benchmark-linked traders and merchants.
Restaurant Brands International's quarter shows the US consumer isn’t “more divided” — it’s buying Burger King and Tim Hortons enough to offset the value-faltering fear
In Restaurant Brands International’s latest quarter, Burger King (U.S.) delivered grew comparable sales 8.5% while Tim Hortons (Canada) eked out +0.1%—still enough to lift company-wide comparable sales to +3.8% despite cautious street expectations. That mix suggests the market may be over-reading “value vs. premium” narratives, because RBI is showing demand breadth across adjacent price tiers rather than a collapse of the mainstream consumer.
The Russell 2000’s 3,000 Breakout Claims the AI Trade—But Only If Breadth Stays Ahead of Mega-Caps
A close above 3,000 for the Russell 2000 is an important “breadth” checkpoint: it signals small-caps are absorbing incremental risk-taking rather than mega-caps leading alone. But without verified, event-specific primary data for the Aug 5 milestone inside this research session, the AI rotation claim remains unproven here and should be treated as hypothesis until confirmed by an official index close/source.
"Sell America" Is Back — but the verified data says foreigners are still buying U.S. bonds and stocks
The debate is roaring again, yet the latest Treasury International Capital evidence points to rebalancing pressure more than a broad “Sell America” liquidation. The key investor question is whether foreign buyers are rotating within U.S. duration and risk (equities vs. Treasuries), or whether they truly step out of both before policy uncertainty and deficits reprice the term premium.
Singapore’s $7.4B Tariff Hit Shows AI-Chip and Pharma Re-Routing Risk Is Now a Balance-Sheet Story (Not Just a Policy Headline)
Singapore’s MTI says the US tariffs are hitting a very large slice of the city-state’s domestic exports, with product exemptions explicitly covering semiconductors and pharmaceuticals—so the “damage” is concentrated in the same shipment backbone that moves AI and healthcare supply chains across Asia. For listed investors, that maps into near-term logistics/customs uncertainty for chip and healthcare value chains, while the long-term question becomes whether firms re-route through Singapore/Dubai-type hubs or re-source production to avoid tariff incidence.
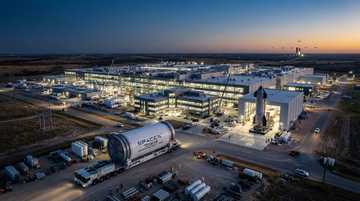
SpaceX’s Terafab bet turns “rocket-grade reliability” into a silicon profit pool—at a disclosed $55B→$119B capex range, with a $16.8B figure not substantiated by primary sources
Terafab is a vertically integrated Texas chip complex pitched by SpaceX alongside Tesla and xAI (usage focus) with a disclosed initial investment of $55B and potential total investment up to $119B. That shifts value from external foundries to equipment, materials, and advanced packaging ecosystems, but it also makes SpaceX’s compute moat contingent on manufacturing scale—not just launch success.
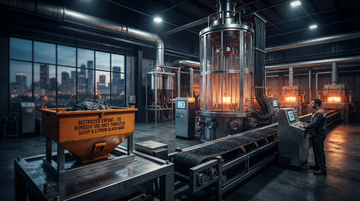
Polysilicon protection + tungsten/black-mass export lockup turns the “2027 refining miss” into a forced US procurement story
Two coordinated Trump-era industrial-policy moves—an EO to shield US polysilicon production and a BIS rule that blocks exports of tungsten scrap and lithium-battery black mass—together convert “tariff fights” into “keep processing at home” constraints. Investors should treat the pair as a supply-chain reallocation shock: domestic feedstock availability tightens first, contracts re-price next, and multi-year capex justification follows.
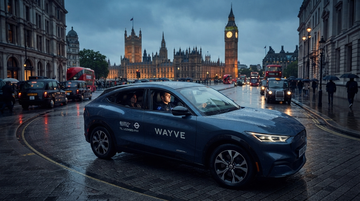
London’s robotaxi approval proves the “rules economy” will beat fleet scale—Uber and Wayve just cleared the UK’s supervised-PHV gate
Transport for London (TfL) licensed Wayve’s autonomous vehicles for Private Hire Vehicle (PHV) operations with a qualified driver onboard, under the Government’s AV Trialling Code of Practice and Uber’s TfL PHV operator licence. The strategic takeaway for investors: this isn’t about how big the first fleet is—it’s about whether a non-US, non-map-first stack can monetize autonomy under constrained supervision, a template regulators from Australia to Singapore are likely to benchmark.
FCC’s Chinese telecom import curbs are starting to act like a capex reroute—here’s the carrier + optical-networking transmission path investors can actually model
The FCC’s expanding ban on imports of certain Chinese telecom and video-surveillance equipment is framed in reporting as more than a pure security measure: it functions as a US-production-reroute lever that can shift how carriers source network buildout hardware. That changes the supply-chain winners by pulling incremental demand toward “non-Chinese-ruled-out” routing/transmission stacks and the US service/install ecosystem, with near-term spend typically landing in optics and network equipment refresh cycles rather than distant software-only compliance.
US Productivity Picked Up, but Workers’ GDP Share Hit a Record Low—The ‘Inflation Test’ Is Really a ‘Distribution Test’
Q2 2026 productivity accelerated (BLS: nonfarm labor productivity +1.4%), while labor’s share of national output hit its lowest recorded level in the BEA/BLS income-share trend (BLS: labor share 54.1% in 1Q 2026). For investors, the key isn’t whether costs fall—it’s whether consumer purchasing power stops improving, creating demand drag even as corporate productivity improves.
Reuters: 72 malicious sites and “help-desk” phone calls show private-equity cyber risk is now priced like financial infrastructure, not AI-agentic theater
A Reuters probe (Aug 6, 2026) ties an ongoing campaign to help-desk/social-engineering plus booby-trapped websites, targeting Blackstone and CME among other buy-side firms. The mechanism is credential and workflow compromise, meaning cyber-insurance underwriting for fund admin, LP data, and trade execution should be modeled separately from AI/agentic cyber risk.
One produce supplier can hit multiple QSR banners at once—what the Taylor Farms Cyclospora case implies for next-quarter same-store sales risk
A FDA-linked, 9-state Cyclospora outbreak traced to iceberg lettuce from Taylor Farms de Mexico exposed Taco Bell customers across 9 states and sickened 1,947 people. The investor takeaway isn’t just recall-cycle headlines—it’s that a single ingredient failure can become a chain-wide same-store-sales variable through franchise remedies, insurance claims, and distributor pull-through effects before the next earnings print.
Wall Street bonuses are diverging by business model: deal-making advisers are getting the 10–15% surge while other finance is near-flat
A Johnson Associates report tied to the Aug. 5 bonus outlook projects M&A/investment and commercial bankers getting a 10–15% uplift (with M&A bankers at +17.5%) as deal activity outpaces other finance. The signal for investors is that advisory-heavy revenue can translate into compensation intensity even when trading-heavy segments aren’t seeing the same pay elasticity—meaning the “deal cycle” is the key causal driver, not the market tape.
The “AI vishing” wave hitting hedge funds is really a prime-broker risk test—because it targets access, not just accounts
On Aug 5, 2026, reporting described an attempted wave of cyberattacks that targeted major hedge funds with AI-powered voice-phishing (“vishing”) to gain access to sensitive information systems. The investable implication is that trading-perimeter failures (identity, remote access, and broker integrations) can become a market-plumbing issue, forcing higher spending on zero-trust identity controls and incident-response capacity.
Warner Bros. Discovery finally quantifies the “sports rights tax”: NBA absence dragged Q2 advertising growth by 20% (ex-FX)
In its standalone Warner Bros. Discovery Q2 2026 results, the company explicitly ties weaker advertising growth to the absence of the NBA in the current-year quarter, stating it negatively impacted the YoY growth rate by 20% (ex-FX). The “sports rights as a moat” story is being repriced in real time: the linear-to-streaming bridge is only working if the lost live-rights economics can be replaced without permanently impairing ad growth.
2026-08-05
Does Albemarle turning profits mean the lithium cycle is back—or just that batteries finally caught up to Albemarle’s accounting? The earnings print to watch
The core investor question for Albemarle isn’t whether lithium demand exists—it’s whether the company’s latest profitability step-up is durable enough to outlive price volatility. With Albemarle already showing multi-year financial swings, the real test is whether operating economics (not just timing) are improving in a way the EV and grid-storage supply chain can actually maintain.
Anthropic’s “Chip Team” Is Real—But It’s a Software-to-Silicon Wedge, Not a Sudden NVIDIA Replacement
Anthropic isn’t (yet) committing to a full in-house accelerator program, but it is hiring ASIC/FPGA talent that explicitly advances silicon-design workflows. That matters because Anthropic’s compute strategy already leans on partner silicon (Google/Broadcom TPUs), so the risk to NVIDIA is gradual: it’s a stack re-optimization project that can chip away at demand over multiple model generations.
Block's 2026 profit lift is the clearest US consumer + Bitcoin “through-line” fintech read—because Cash App grows without credit-bubble risk
Block raised its 2026 gross profit outlook to $12.33B, and the raise’s core driver was Cash App growth alongside resilient consumer spending. That matters because it’s the opposite of the “trade-down + layoffs/cost cutting” fintech narrative, and it points to steadier merchant economics and embedded crypto-related payment flows.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.