Materials & Supply Chain
Raw materials and the chokepoints that price them
Lithium, rare earths, copper and shipping — permits, export bans and capacity, followed to the miners and manufacturers on either side.
2026-08-20

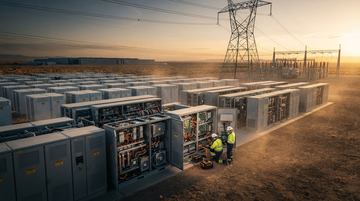
AI’s grid firming bottleneck isn’t batteries—it’s the grid-scale storage “power electronics” that let queues turn into revenue
Grid-scale battery projects are increasingly pulled forward by AI-driven interconnection demand, but economics are still governed by what can actually connect and operate: cells, then PCS/power electronics, then integrator execution. Tesla and Enphase both show how tariff and policy mechanics flow through the storage value chain—strong deployments can coexist with margin pressure when the PCS/inverter leg costs rise faster than pricing.
INTerpath-001 proves the science—but Moderna’s personalised mRNA build is the sales “throughput” limiter investors must model
On Aug 19, 2026, Merck and Moderna reported positive Phase 3 topline results for intismeran autogene plus Keytruda (INTerpath-001). But the product is “made-to-order” per patient using that patient’s tumor mutations, so capacity is constrained by sequencing turnaround and bespoke mRNA manufacturing/fill-finish, not just by clinical demand.
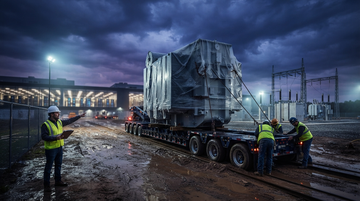
Utility-scale power transformers are the AI grid’s multi‑year choke point—and today’s ~5.2% long-rate turns every delay into a financing problem
High-capacity transformer lead times have stretched to years, shifting “grid connection readiness” from a construction issue to a procurement-and-capital-access issue. With 30-year Treasuries recently around ~5.2%, the present value of AI-driven grid buildouts falls just as transformer delivery schedules slip—rewarding vendors and projects that can win connection queues first.
2026-08-19
Berkshire Hathaway is selling Nucor even as tariffs should be “most” protective — which points to a demand problem the market isn’t pricing
Berkshire Hathaway’s successor, Greg Abel, has trimmed Nucor by more than half in the latest disclosed portfolio changes, turning a steel trade that looked tariff-protected into something Abel no longer wants as a bet. The deeper read isn’t “tariffs stop working”; it’s that steel upside is being driven by order and end-demand durability, and when demand weakens, even a tariff bloc can fail to prevent earnings compression. For investors, the move shifts focus from the tariff math to the domestic steel order book, working-capital intensity, and how fast producers can re-price supply.
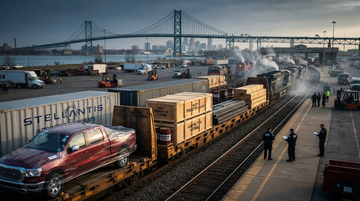
Tariff Whiplash Gets a 3-Day Refund: What Gets repriced first in autos, dairy, alcohol, and construction materials
The 50% Section 338 tariffs on select Canadian goods were paused for three days right before the midnight start, followed by a “deal” framework. For markets, the investment question shifts from “damage” to “unwind”: which sector discounts were priced for immediate tariff flow disruption—and how fast they can reverse when the policy shock is temporarily removed.
Lagarde’s “order” warning reframes EURUSD: the risk isn’t just currency—it’s Europe’s supply-chain competitiveness lagging the US
ECB President Christine Lagarde says the weakening of a rules-based global order—specifically tied to America’s pullback from Western security leadership—is eroding the conditions behind Europe’s post-war growth model. The bigger market risk may be the second-order transmission: slower European investment and scaling under geoeconomic fragmentation, which can pressure both competitiveness and the euro’s role in trade, not merely EURUSD spot levels.
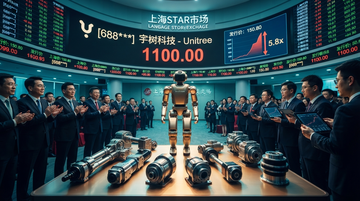
Unitree’s 5x Shanghai debut turns China’s humanoid supply chain into a capital magnet—here’s who captures the first funding windfall
Unitree Robotics (listed as Yushu Technology) debuted on Shanghai’s STAR Market after an IPO priced at 150.8 yuan—then opened at 1,100 yuan, implying a ~5–6x first-day jump versus the offer. The windfall is likely to flow first into the “mechanics layer” (actuators, harmonic reducers, precision sensing) because Unitree’s IPO disclosed near-term R&D and manufacturing-capex use of proceeds—while US-led procurement barriers can redirect Chinese demand into domestic component ecosystems that Tesla Optimus can’t easily bypass.
2026-08-18
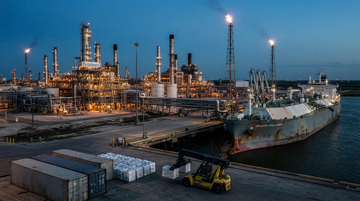
Braskem BAK ‘s Mexico Chapter 11 moves the ethane-cracker stress test to the front of the Americas petrochem trade
Braskem’s Mexico ethane-into-polyethylene footprint is entering a U.S.-court Chapter 11 restructuring, after consents designed to cut senior debt by more than $920MM. The event matters beyond Braskem BAK: it pressures the ethane-cracker operating model and turns the next move for U.S. ethane exporters and PE pricing from “tailwind” into “risk.”
Brookfield’s A$4.75 cash bid for Reliance Worldwide prices repair/remodel resilience into a plumbing-fittings roll-up
Brookfield Capital Partners has proposed buying Reliance Worldwide for A$4.75 per share, valuing the deal at about A$4.1 billion. The valuation hinges on a bet that Reliance Worldwide’s push-to-connect plumbing mix and US repair/remodel exposure can keep converting sales into cash even when new construction cools.
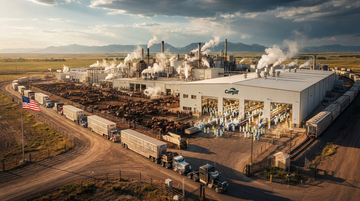
Cargill’s Fort Morgan restart just added ~20,000 head/week of US beef packing capacity—right when the “cattle squeeze” thesis needed it to stay tight
Cargill workers ratified a contract ending the Fort Morgan, Colorado lockout, with slaughter expected to restart the week of Sept. 7 and production ramping over the following weeks. Using the plant’s stated throughput (up to 4,700 head/day), the return of roughly 4 months of idled capacity is a direct supply release into a beef chain already sensitive to cattle availability—compressing the near-term probability that packers can keep tightening margins and that cattle/beef prices remain one-way.
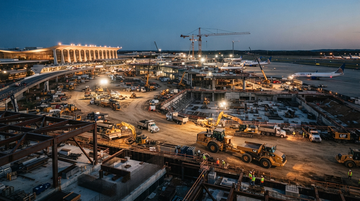
Dulles’ $19.9B overhaul gets the green light—yet financing math at ~5% Treasury yields is the real schedule risk
MWAA’s board is set to vote on a roughly $19.9B Washington Dulles overhaul, framing it as a once-a-generation rebuild. The investment size is less important than the financing stack: if rate-sensitive municipal capital is repriced upward, the program’s phased construction plan becomes the pressure point for contractors, aviation engineering services, and durable-goods suppliers.
2026-08-17
The real AI “tolls the rack” war: Ethernet-scale NVLink’s moat can’t stop fabric spend from compounding
At 100k-GPU scales, the winning network design is less about peak interconnect bandwidth and more about how fast hyperscalers can buy, deploy, and oversubscribe the fabric without sacrificing collective efficiency. The Ethernet side is gaining momentum through purpose-built standards like Ultra Ethernet, while NVLink remains the scale-up “in-rack” fast path—so the interconnect profit pool migrates between chip, switch, and server layers depending on where architectures settle.
The 48V rack bus is the new price bottleneck in AI data centers—SiC/GaN power silicon may capture the “dollars-per-watt” upside that electrical OEMs can’t
As AI racks scale toward hundreds of kilowatts, the in-rack power-delivery chain (PSU → 48V bus → VRMs → SiC/GaN switching) is getting harder to build, cool, and qualify as one stack. Primary disclosures show that the Vera Rubin NVL72 rack design already concentrates power demand into multiple 110kW shelves, while grid-side electrical backlogs (Eaton) and 800V HVDC guidance (onsemi) point to a multi-year build-out. Investors should expect silicon vendors supplying SiC/GaN efficiency and density to monetize the “per-watt” upgrade cycle faster than the grid/electrical OEM layer.
Apple's $2,000 foldable would test whether margins can beat the memory-cost crunch—and who captures the bill of materials
A $2,000+ Apple foldable would be a rare bet that high-end mix can defend handset profitability even as component pricing pressure rises. If the build routes through Samsung Electronics OLED supply plus hinge and ultra-thin glass specialists, then $2K demand is less important than yield-driven costs—because margins rise or fall at the display and crease/hinge failure points, not in memory alone.
China’s steel output slide collides with US tariff protection—how the steel demand print is pressuring iron ore and squeezing US margin assumptions
A new demand-side picture—China’s weaker steel production alongside faster housing price declines—implies less real steel consumption and more export overhang. That mix matters for US mills because tariff walls can keep certain steel flows out, but they can’t stop global raw-material pricing from repricing.
ATE is the real AI bottleneck: Advantest and Teradyne own the “last meter” on shipping HBM-heavy silicon
As HBM stacks and chiplet complexity multiply test vectors, test floor throughput and “known-good” screening—not EUV—can become the binding constraint on how fast AI chips convert into shippable units. Teradyne and Advantest are positioned as critical enablers because they sell the platforms (and test pattern memory/architecture) that make high-throughput memory and compute testing feasible.
2026-08-16
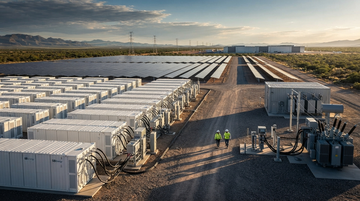
Nvidia’s $3B SB Energy bet highlights the missing “grid-firming” link in AI power
Nvidia’s reported move to invest up to $3B into SB Energy underscores that AI data-center growth is constrained less by chips than by 24/7 power availability. The real supply-chain margin sits in grid-scale storage, power-electronics, and fast interconnection—areas where equipment and energy-storage firms can see order-flow spillover once projects lock fuel (or storage) and transmission timelines.
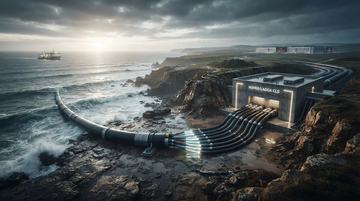
The transatlantic bottleneck for AI isn’t fiber—it’s who gets to land it
Google’s new transatlantic subsea buildout shows how AI demand is now translated into physical route control: its Nuvem system targets ~384 Tbps across 16 fiber pairs and lands at the Atlantic “gateways” it chooses. In the U.S., FCC licensing and the ownership/architecture of cable landing stations then shape which ecosystems can absorb that capacity first—creating a new competitive edge for operators that sit closest to landing points like Equinix, and a new risk for traffic planners that assume capacity availability is purely a “cable count” problem.
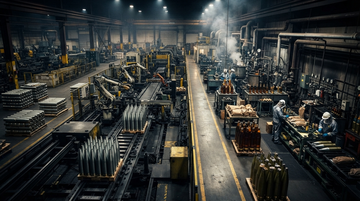
The real bottleneck in 155mm restock isn’t the shell-body line—it’s TNT, propellant charges, and the energetics/chemicals substrate
The U.S. Army’s effort to surge 155mm output has exposed a binding constraint: the energetics layer (TNT explosive fill, propellant charges, and related specialty energetic materials) is harder to scale than the metalworking and assembly steps. The sharpest proof is how capital spent on shell production can still fail to yield usable rounds when upstream requirements—like explosive-fill readiness and propellant/charge compatibility—can’t ramp fast enough.
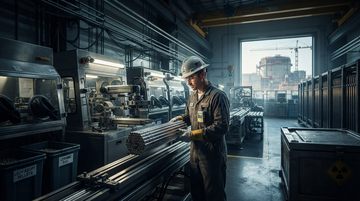
AI data-center power demand isn’t choking reactor builds—fuel-cycle bottlenecks are tightening uranium-to-fabrication capacity
The hyperscaler PPA wave is being stress-tested by the slowest part of the nuclear supply chain: the front-end fuel cycle. ConverDyn-scale conversion, enrichment capacity, and downstream fuel fabrication are the binding constraints on when new megawatts can actually produce—turning uranium, enrichment, and fuel makers into the margin hinge for AI-linked deployments.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.