Materials & Supply Chain
Raw materials and the chokepoints that price them
Lithium, rare earths, copper and shipping — permits, export bans and capacity, followed to the miners and manufacturers on either side.
2026-08-10

2026-08-09
AI Power Spikes Are Forcing First-Order Capex Into UPS, Switchgear, and Generators—Turning Grid Reliability Into an OEM Supply-Line Shock
A new wave of AI power volatility is not just straining the grid; it is shortening the life and pushing the replacement cycles of batteries, generators, and cooling/power electronics inside data centers. That shifts the 2026–27 capex bottleneck from “build power lines” to “rebuild mission-critical power chains,” which can tighten supply and raise downtime-cost risk for operators and volume-forced production for OEMs like Eaton, Vertiv, and Generac.

Sila’s $1.4B OSC conditional loan turns silicon-anode industrial policy into a direct, materials-led Pentagon procurement lever
On Aug 7, 2026 the U.S. Office of Strategic Capital (OSC) announced a $1.4B conditional loan commitment to Sila Nanotechnologies tied to expanding silicon‑carbon (Si/C) anode production and building lithium‑ion cell capacity. The strategic signal is that DoD/OSC is funding the next energy-storage stack at the materials bottleneck—before cells and primes—so investors should map winners to silicon-anode scaling, electrolyte/lithium refining, and US cell manufacturing.
SK hynix’s 18-Month Insider Sentence Doesn’t Target HBM—It Forces a New Audit Standard Across the Entire Memory Toolchain
An Aug 9, 2026 appeals-court ruling upheld an 18-month jail sentence for a former SK hynix engineer who leaked classified semiconductor manufacturing information to a Chinese firm. Even though the leaked technology described in the primary report concerns CMOS image-sensor manufacturing (not HBM specifically), the verdict functionally raises the compliance-and-audit bar for any memory supplier whose customer share depends on “trust.”
SK Hynix's 18-month jail ruling signals a new personnel-sensitive trade-secret standard for Samsung, Micron—and the AMAT/KLA/LRCX field-toolchain
A Seoul court sentenced an ex-SK Hynix employee to 18 months in jail for leaking semiconductor trade secrets to a Chinese firm, and the decision (as reported) explicitly rejects “light treatment” of leak crimes. The bigger investor takeaway is indirect: this case hardens how South Korea treats dual-use engineering knowledge—including off-site resumes/prints/photos—so tool vendors that embed with fabs must expect tougher export-control-by-personnel friction around memory/AI process data.
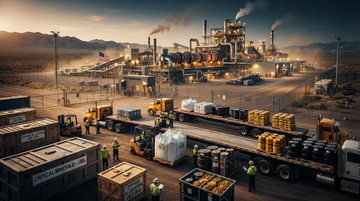
The DFC’s $3B minerals push is less about “materials” and more about buying 2027–2028 capacity blocks—MP Materials, USA Rare Earth, Energy Fuels, and Lithium Americas are the clearest US order-book fits
A verified Aug 7, 2026 package around critical minerals financing links to defense supply-chain bottlenecks, but the publicly accessible primary materials we can confirm name only a partial set of project participants. Using that confirmed deal/map plus listed-company capacity economics, the clearest “funding-to-offtake” winners are the US incumbents that can plausibly monetize demand under a 2027–2028 commissioning window—MP Materials, USA Rare Earth, Energy Fuels, and Lithium Americas—while the defense OEM names (e.g., Lockheed Martin and RTX) mainly matter as anchor buyers of qualifying downstream output.
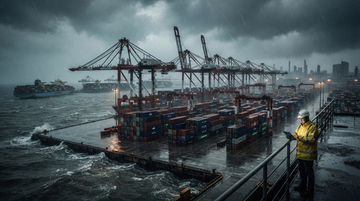
Ningbo’s shutdown turns Typhoon Dolphin into a timing-and-margin test for Apple, Nike, and PDD Holdings
Typhoon Dolphin triggered a suspension of Ningbo port operations on Aug 7 local time, with follow-on disruption across East China ocean and time-sensitive air freight. The investor-relevant risk is not just delays—it’s that missed replenishment windows force brands to choose between discounting, expedited freight, or inventory build, pressuring gross margin during the back-to-school freight cycle.
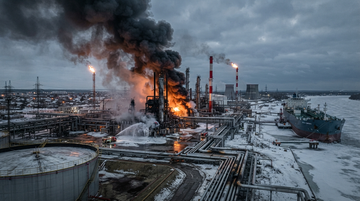
Ukraine’s drone strike on Russian refineries shifts the diesel story from “Iran/Hormuz risk” to hard supply destruction
By hitting two Russian refineries in a coordinated drone attack, Ukraine has targeted the part of the system that converts crude into diesel—tightening product availability and strengthening diesel crack spreads through lost runs. For refiners with product-heavy exposure, the investment implication is not just “war risk premium,” but whether incremental outages persist long enough to translate into sustained margins.
2026-08-08
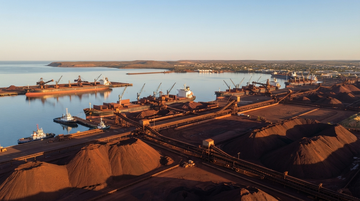
BHP’s Port Hedland 48-hour stoppage is a “steel-margin repricer,” not an iron-ore headline blip
A two-day protected action at BHP ’s Port Hedland Bulk Export Terminal starts with a 24-hour ship-loading ban (Aug 8) and then a 24-hour terminal stoppage (Aug 9). With the stoppages likely affecting ~800,000 metric tons of seaborne iron ore shipments per day, the shock hits steel input costs and downstream pricing faster than iron ore itself can mean-revert.
Hadrian’s $1.37B at a ~$7.87B valuation signals defense manufacturing is the new capital magnet—and it pressures software-multiple investors that can’t show factory throughput
Hadrian (private) raised $1.37B at a $7.87B valuation to scale “factories-as-a-service,” with explicit capacity moves for munitions, shipbuilding, and submarine-component production. For listed defense primes, the real test is whether new factory capacity can convert into deliverable, margin-protecting production schedules—while “autonomy-only” winners face longer cash-conversion paths.
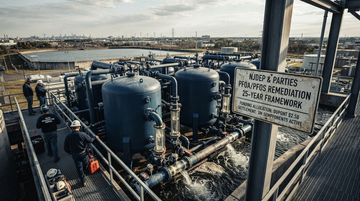
NJ’s $2.5B PFAS deal turns “forever chemicals” into a funded balance-sheet item—and rewrites who bears the next wave of US water risk
New Jersey’s court-approved PFAS settlements with DuPont (plus its spinoffs) and 3M convert open-ended “forever chemical” liability into scheduled, allocable payments through a 25-year remediation framework. For investors, the immediate read-through is less about one state getting paid—and more about how the payment+trust model pressures insurers, reshapes utility capex planning, and strengthens the enforcement pipeline across the US water system.
DFC’s $3B minerals bet turns “China decoupling” into a processing-margin race—and the winners are the firms that can monetize working capital first
The U.S. Development Finance Corporation (DFC) has outlined a $3B set of domestic critical-minerals deployments, including a prominently cited $58M-financed component, aimed at strengthening defense-adjacent supply chains. For investors, the key shift is not “more mining,” but which listed processors can pull forward separation/refining timelines—because DFC-style financing changes capex sequencing and who captures the processing margin.
2026-08-07
2026-08-06
Yuan-Price Iron Ore Would Break the Dollar Benchmark Lock—And Reprice the Largest China Seaborne Deals Faster Than Prices Move
China’s steel and iron-and-steel leadership is pushing for a CNY-denominated iron ore price index to anchor contract pricing alongside (and increasingly in place of) dollar benchmarks. If implemented at scale, it would shift how Vale VALE and BHP BHP settle long-term and spot-linked formulas, changing FX-adjusted margins and hedging needs more than the headline iron ore price alone.
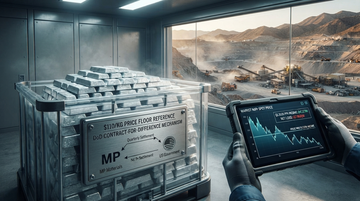
MP Materials tests whether a government NdPr price floor actually caps downside—or just books accounting relief
MP Materials’ Q1 2026 showed the mechanism that matters most for its federal rare-earth price-support framework: price-protection agreement income generated $42.273M while the net loss narrowed to $7.968M. The real economic test is Q2—especially whether the $110/kg NdPr contract-for-difference floor keeps revenue volatility contained when NdPr spot falls, and whether that shows up as durable gross profit and cash outcomes.
Indonesia’s Prabowo export “downstreaming” is no longer a sector bet—it’s a trading-venue bet that rewards Jakarta intermediaries
Indonesia’s Prabowo-backed plan is tightening control of strategic commodity exports through a state oversight/trading structure, starting with palm oil, coal, and ferroalloys and rolling out via phases in 2026. For investors, the non-obvious impact is that forced domestic processing and centralized export intermediation can pull physical volumes away from global benchmarks and shift cashflow timing to Jakarta-listed corporates with the right domestic footprints—while pressuring global benchmark-linked traders and merchants.
Polysilicon protection + tungsten/black-mass export lockup turns the “2027 refining miss” into a forced US procurement story
Two coordinated Trump-era industrial-policy moves—an EO to shield US polysilicon production and a BIS rule that blocks exports of tungsten scrap and lithium-battery black mass—together convert “tariff fights” into “keep processing at home” constraints. Investors should treat the pair as a supply-chain reallocation shock: domestic feedstock availability tightens first, contracts re-price next, and multi-year capex justification follows.
2026-08-05
Does Albemarle turning profits mean the lithium cycle is back—or just that batteries finally caught up to Albemarle’s accounting? The earnings print to watch
The core investor question for Albemarle isn’t whether lithium demand exists—it’s whether the company’s latest profitability step-up is durable enough to outlive price volatility. With Albemarle already showing multi-year financial swings, the real test is whether operating economics (not just timing) are improving in a way the EV and grid-storage supply chain can actually maintain.
Cerberus’s $4B Supply Chain Fund II pitch turns private capital into a Pentagon policy lever—because Feinberg is now an underwriting mechanism
Cerberus is targeting at least $4B for its second supply-chain fund, framed as scaling U.S. domestic industrial capacity. The unusual signal isn’t just fundraising size—it’s that Stephen Feinberg’s post as Deputy Secretary of Defense creates a feedback loop where defense-aligned portfolio bets can directly shape the Pentagon’s procurement-and-industrial base priorities.
Dimon’s Cross-Industry AI Governance Signal Is Not a Statement—It’s a Supply-Chain Control Point
The first public-market evidence that “frontier-lab self-policing” is fading is not new model claims—it’s the move to coordinated, defensive, cross-vendor tooling via Anthropic’s Project Glasswing, where JPMorgan Chase is a launch partner. Once governance becomes operationally enforced through software supply-chain security, cloud builders, cyber vendors, and deployment platforms must budget for recurring verification work—raising the cost of AI speed.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.