Materials & Supply Chain
Raw materials and the chokepoints that price them
Lithium, rare earths, copper and shipping — permits, export bans and capacity, followed to the miners and manufacturers on either side.
2026-08-05


Glencore’s ASX Secondary Listing Is a Capital-Flow Play, Not a New Share Sale—and That Changes How Copper M&A Will Get Financed
Glencore is exploring an Australian secondary listing to broaden its investor base in a market where mining capital is sticky and deal scrutiny is comparatively workable. The upside for copper investors is less about “fresh money” and more about lowering the cost of capital for future copper/power/industrial metal projects—while the risk is that governance and execution will still be the real constraint.
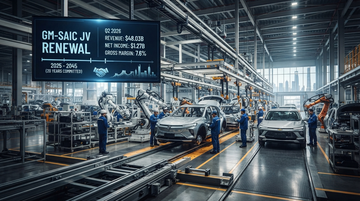
General Motors's SAIC JV renewal makes “decoupling” look optional—because it locks manufacturing in China through 2045
GM renewed its 50-50 SAIC joint venture for 20 years after a restructuring that included plant closures and model elimination, extending the partnership’s manufacturing commitment in China through 2045. That decision reframes the investing debate: US automakers aren’t just choosing where to sell—they’re choosing where to stay and who controls the production footprint. The second-order question now is whether Ford and Stellantis treat JV renewals as a supply-chain strategy template (or an overdue retreat).
Honeywell Aerospace is trading like an “inventory-and-labor” story after it cut its 2026 outlook for supply-chain reasons
Honeywell Aerospace’s first stand-alone guidance update reframes the supply-chain debate from macro “constraint noise” into a measurable operating squeeze: inventory normalization and labor execution risk show up in how it guides 2026. For investors, the read-through is less about “GE Aerospace-style sell-the-news” and more about who downstream can absorb delivery gaps while upstream (titanium/fasteners/avionics) still has the hardest bottlenecks to solve.
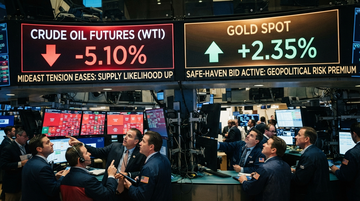
A “deal is imminent” reprice flips oil-and-gold the other way—here’s what it means for Exxon Mobil, Chevron, Delta Air Lines, and Barrick Mining
When reports that a US-Iran “imminent” peace package would reduce Middle East risk hit, oil fell sharply while gold rose—signaling markets are pricing supply-likelihood and safe-haven bid at the same time, but in opposite directions for different asset classes. The first-order implication is not just “lower escalation risk”: it’s a capex and margin timing shift across oil majors, refiners/airlines, and gold miners—turning July’s escalation-premium framework inside out.
Samsung and SK Hynix testing AMEC tools signals the first real “tool-vendor hedge” against U.S. export-control risk
Reuters reports that Samsung and SK Hynix are evaluating AMEC etching tools for their China fabs as a hedge against tighter U.S. export controls. The key buy-side read-through is not just China localization—it’s a shift in how leading memory makers de-risk Western tool reliance via second-source qualification, which changes the demand timing and pricing power across the etch/deposition value chain.
Polysilicon tariffs aren’t a module story—they’re a waiver-and-margin story that decides whether IRA solar builds keep running
The US Commerce Department’s polysilicon Section 232 process is upstream policy leverage, and it can still ripple to module prices even before any “15% tariff” becomes official. The investor impact is a bifurcation: First Solar is structurally insulated because it sells cadmium-telluride modules that don’t rely on polysilicon waifers, while Enphase and residential installers face demand risk if tariffs raise installed system costs faster than incentives can offset.
2026-08-04
ADM’s Raised 2026 Biofuels-Driven Outlook Suggests a Margin Cycle That May Be More Policy-Structured Than Cyclical
ADM lifted its 2026 adjusted EPS outlook to $4.15–$4.70, explicitly tying the upgrade to “constructive” post–U.S. biofuel policy clarity and expected earnings improvement across its crushing and ethanol businesses. The key shift isn’t just higher margins—it’s that renewed regulatory demand visibility is changing how feedstock economics flow through crushers, refiners/ethanol plants, and ultimately to farmers.
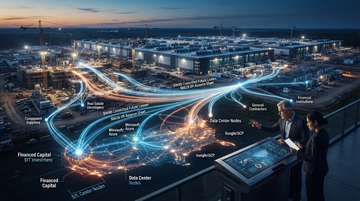
AI’s $1 Trillion Lease Tab: Hyperscalers Shift Utilization and Refinancing Risk—But It Reappears Everywhere
Moody’s estimates $662B of future data-center lease commitments across the largest U.S. hyperscalers sit off balance sheets because they’re not yet commenced—despite the projects being financed and under construction. That shifts occupancy and refinancing risk down the supply chain, turning “leased compute” into a system-wide obligation map investors can’t ignore.
Iron Ore at a 13-Month Low Turns Beijing’s Stimulus Into a Math Problem at ~$95, Not ~$115
A slide in iron ore forces investors to separate “China steel demand” from “headline price.” Using China’s iron-ore import/inventory signals, the real test for the whole bulk-materials chain is whether stimulus can lift steel throughput enough for benchmarks to stay above the economic clear price—otherwise high-cost supply is still punished while US/EU steel margins get a temporary cushion.
Procter & Gamble's $3.8B Thorne bet shifts “wellness” from shelf risk to premium supply-chain leverage
Procter & Gamble is reportedly paying $3.8B in cash to acquire Thorne, a science-driven supplements brand, with closing expected later in 2026. The investor question is not “does supplements grow?”—it’s whether P&G can add a higher-growth, higher-trust revenue stream without sacrificing the margin discipline that supports its staple-like cash generation.
America’s trade deficit shrank because imports fell—watch the supply-chain “pause” behind the headline
In June, the U.S. goods trade deficit narrowed to $101.5B largely because imports of goods fell $8.2B m/m. That looks GDP-friendly on the surface, but it can also signal a demand pause and inventory/freight timing effects—typically showing up first in logistics and in companies with high import exposure.
2026-08-03
Copper Foil Is the New US IPO “Test of Trust” for China’s AI Compute Supply Chain
Londian Wason [FOIL] is using a US listing to formalize access to Western capital for a bottleneck material: electrolytic copper foil that feeds both LiB and PCB-grade conductors used in high-performance computing. In its F-1, it frames AI/high-speed computing PCBs as requiring lower-roughness foil (RTF/HVLP) and highlights a scale where PCB-grade remains far smaller than LiB—so investors should watch whether the market can re-rate the PCBs growth story before certification and customer concentration risks show up.
Curium’s Lantheus bid is really an isotope-capacity bet—because radiopharma growth is constrained by reactors, not chemistry
Curium’s reported pursuit of Lantheus shows radiopharma is shifting from “drug + distribution” to “drug + isotope throughput.” The investment implication is that bidders can gain durable advantage only by securing upstream nuclear capacity and locking down downstream commercial pull.
Tyson Foods's cattle squeeze turns into a repricing event for the whole US beef chain
In its FY26 outlook language, Tyson Foods ties weaker profit to structurally tight US cattle supplies, not just short-term volatility. For investors, the key shift is that the beef complex now has to price longer-lasting scarcity (and higher upstream cost risk), while downstream channels face slower relief from cheaper cattle.
2026-08-02
2026-08-01
The Quartz TRQ Protects U.S. Makers—But Its First Cost Lands on Builders
President Trump’s July 31 safeguard turns quartz countertops into a four-year test of tariff-rate-quota policy: imports face a 25% duty inside a rising volume ceiling and a 40% duty above it in Year 1. The structure should improve pricing power for U.S.-made premium surfaces, but it also raises delivered costs for fabricators, retailers, and remodeling customers while listed supplier Caesarstone enters the policy with falling sales and negative EBITDA.
The UFLPA’s 43-Company Expansion Turns Supply-Chain Proof Into a Cross-Industry Cost
DHS added 43 China-based companies to the UFLPA Entity List on July 31, bringing the total to 187 and making the restriction materially broader than an apparel-only issue. The immediate risk is not a blanket tariff: it is shipment detention, denied entry, supplier replacement and documentation costs for importers using aluminum, metals, battery materials, food or electronics linked to the listed entities.
2026-07-29
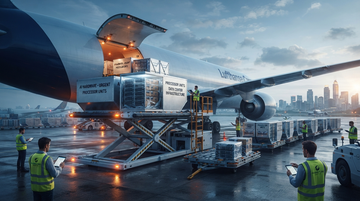
AI hardware is pulling air cargo capacity toward data-center “just-in-time”—and operators with scheduling power are the gatekeepers
In 2025, air cargo transported more than two-thirds of global AI-related goods, making aircraft utilization and slot allocation a strategic bottleneck rather than a background logistics variable. The air-freight scarcity that e-commerce previously dominated is shifting to dense, time-sensitive AI hardware lanes, where the margin moves from shipping volume to capacity control.
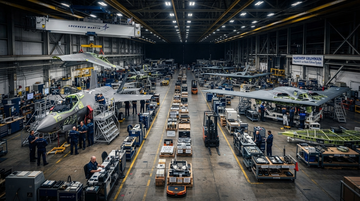
Defense backlogs are not “capacity”—fixed-price contract structure and supply-chain + labor execution decide which primes (and suppliers) actually monetize demand
Across Lockheed Martin and Northrop Grumman, the filings show that backlog growth can coexist with contract-level cost and margin pressure under fixed-price development/early-production risk. Investors should treat backlog as a demand signal—but value conversion hinges on labor availability, supply-chain performance, and how much profit/loss risk sits inside the contract terms.
China’s DUV mass-production pressures Congress: MATCH Act’s servicing ban timing will decide whether Lam Research, Applied Materials, and KLA harvest China growth in 2H26 or lose it to license “latency”
China’s July 27, 2026 shift to mass-producing homegrown immersion DUV tools increases the probability of near-term fab ramp—exactly when the MATCH Act must clear Congress if it’s meant to restrict not just exports, but servicing/maintenance. For the US semicap trio, the key risk is that a servicing ban applies a licensing policy of denial, which can delay tool upkeep and directly disrupt backlog/revenue conversion even if some equipment already sits in-country.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.