Materials & Supply Chain
Raw materials and the chokepoints that price them
Lithium, rare earths, copper and shipping — permits, export bans and capacity, followed to the miners and manufacturers on either side.
2026-08-30

Prysmian’s $3.8B Atkore deal is a “full electrical stack” play—priced like channel control, not just capacity
Prysmian’s planned $3.8B acquisition of Atkore would add U.S. conduit/raceway and electrical installation/distribution-adjacent products to its cable business, locking in more of the data-center electrical build. Read with Prysmian’s earlier €5.5B (€/$) Molex data-center anchor, the pattern points to consolidation that should raise “electrical-content-per-GW” pricing power, because it reduces interface risk across the stack.
12-inch wafer contracts are the earliest AI-caper cycle tell—if you know where to look
In the 12-inch wafer substrate oligopoly, the key “demand signal” is not wafer pricing or foundry capex—it’s the multi-year contracting structure that can smooth (or amplify) the AI spending cycle years before GPU deliveries. Using Shin-Etsu Chemical, GlobalWafers, and Siltronic financials alongside public contract disclosures, wafer suppliers show more stable but still counter-cyclical revenue/margin behavior than downstream process-cost components, making “contracting depth” a practical investor lens into the post-2023 AI rebuild.
Smart-ring value doesn’t start in sapphire or sensors—it locks in at the recurring health-data subscription
The next wearable “boom” is still constrained by the physical parts—biosignal optics, power, and skin-contact materials—but the investable margin is increasingly determined by who controls the recurring health-data layer. Oura’s move toward public markets makes that hardware-vs-subscription split measurable, while FDA’s stance on non-authorized glucose claims shows why regulated signal quality—not the enclosure—drives durable platforms.
2026-08-29
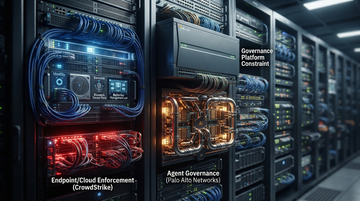
AI-security isn’t a “whole stack” spend—identity, endpoint, and agent governance each claim a different budget line
A wave of demand for AI-assisted defenses is showing up most clearly in identity security and cloud/endpoint platforms’ disclosed contract pipelines, not in any single “one-size-fits-all” security bucket. The investor takeaway: the next security dollar is likely to route through identity (Okta), endpoint/cloud threat prevention (CrowdStrike), and security platforms that operationalize AI (Palo Alto Networks), while broader security incumbents (Microsoft) and zero-trust network layers (Zscaler) shape the platform constraints that determine which vendors get renewed.
The grid emergency isn’t a power-policy problem—it’s a materials bottleneck upstream of the turbine
The U.S. has framed a national emergency around the foreign supply of bulk-power electric equipment, because reliability can’t wait for long lead-time replacements. At the same time, data-center electrification faces a copper chain strain, while the wind-and-grid buildout still depends on rare-earth magnets. Investors should watch which listed suppliers can convert constrained input availability into backlog, pricing power, and margin support.
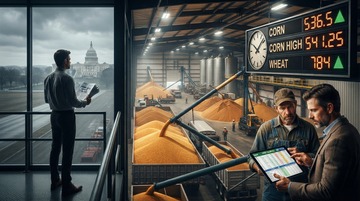
Farm Bill stalled in the Senate while corn and wheat surge: how policy risk reshapes crop-insurance, SNAP, and lender math for the 2027 crop cycle
On Aug. 6, 2026, the Senate Agriculture Committee failed to advance the 2026 Farm Bill after a SNAP cost-sharing fight turned into a party-line roadblock. That political uncertainty lands right as corn and wheat futures hit more-than-three-year highs on Aug. 28, intensifying the near-term tug-of-war between higher revenue expectations and risk-transfer/payments that depend on stalled policy.
Corn and wheat at 3-year highs don’t automatically mean fertilizer margins—Louisiana gas-cost capacity can flip the second derivative in US nitrogen pricing power
With grains strong, the real supply-chain swing is whether US nitrogen pricing tightens or normalizes as new Louisiana capacity moves through permitting and operations. CF Industries’ Blue Point complex and its near-term urea supply plan point to a more local, gas-cost-advantaged margin story that the grains rally can’t price unless fertilizer tightness persists under China-driven export friction.
2026-08-28
The “dollars per rack” race quietly reorders the BOM: high-speed 224G-grade connectors and 48V power interconnects are becoming the compounding constraint
As AI rack designs push faster copper SerDes and higher bus voltages, the connector/interconnect layer is shifting from “plumbing” to a margin-controlling build constraint. Evidence from TE Connectivity and Luxshare Precision shows 224G connector ecosystems are already being engineered for next-gen switch slot density, while Amphenol reports AI-related strength within IT datacom alongside fast revenue growth.
NVIDIA can sell GPUs, but server-assembly wins the “dollars per rack” race—Amazon’s 2M-GPU step makes the ODM bottleneck investable now
Amazon’s AWS is expanding its NVIDIA GPU deployment with an additional 2 million GPUs across 2027–2028, tightening demand for complete rack-scale systems, not just accelerators. With NVIDIA’s Vera Rubin platform emphasizing much faster rack assembly and a broad OEM/ODM ecosystem rollout, the bargaining power shifts toward the companies that can convert GPU schedules into installed racks on time—while margin pressure concentrates where design control and manufacturing yield meet.
AI Servers’ Quietest Bottleneck Is the Passive Layer: MLCC + Power Magnetics Can Gain Content Share Even When “Component Strength” Reads False
The passive parts that sit under every GPU power step—MLCCs and power magnetics inside the 48V rack ecosystem—can grow faster than the “GPU-cycle” proxy because higher power density increases decoupling and transient-demand content per rack. Using Murata’s reported financials as a compounding baseline, the investment takeaway is that winners in capacitors/inductors can look steadier than the semiconductor tape, while memory-price volatility can distort how component strength shows up in reported supply chains.
Anthropic’s courtroom win against the Pentagon’s “supply chain risk” blacklist redraws the rules for AI procurement—then the next fight moves to contracts
On Aug. 27, U.S. District Judge [Rita Lin] ordered the Pentagon’s “supply chain risk” designation against [Anthropic] blocked, finding the measure likely violated the First Amendment and due process. The practical outcome is bigger than one vendor: it constrains how DoD can de facto exclude frontier AI providers from defense work using national-security framing—shifting procurement leverage toward evidence-backed contracting decisions and away from broad, pretextual blacklists.
2026-08-27
Grid-to-GPU’s new bottleneck isn’t transformers—it’s who can schedule switchgear, UPS and interconnection fast enough to hit data-center deadlines
AI capex is colliding with power-delivery realities that don’t clear on silicon lead times. The result: switchgear-to-UPS-to-interconnection becomes the scheduling choke point where long backlogs, constrained commissioning windows and utility bottlenecks convert into multi-quarter project deferrals and pricing power for a narrow set of electrical-equipment suppliers.
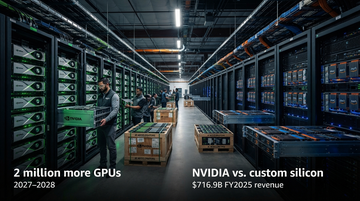
Amazon turns 2M more NVIDIA GPUs into a supply-chain signal—while AWS Trainium argues the “Nvidia-only” story is incomplete
Amazon’s expanded AWS partnership adds 2 million more NVIDIA GPUs for delivery in 2027–2028, the clearest hyperscaler “yes” to the AI capex cycle that aligns with NVIDIA’s recently reiterated ~70% FY2028 revenue-growth framing. But the same expansion exists alongside AWS’s continued scaling of Trainium, meaning the order book can strengthen Nvidia demand while still reshaping how much incremental compute ends up being “Nvidia GPUs vs. custom silicon.”
China’s industrial profit growth hits a 7-month low—proof that deflation is squeezing export margins, not just output
China’s July industrial-profit growth cooled to the weakest pace in months, reinforcing a market that’s already questioning demand and pricing power. The signal matters for global cyclicals because margin pressure in China typically turns from “cheap supply” into “less export price support,” which can quickly reprice copper and steel-related demand expectations—while boosting the probability of Beijing stimulus as September approaches.
2026-08-26
Boston Scientific's cyberattack hits order/shipping systems—so medtech investors should price a new “working-capital + revenue-timing” risk
Boston Scientific BSX disclosed a global cyberattack that disrupted operations and is expected to continue limiting access to systems that support “the ability to process and ship customer orders.” The immediate market question isn’t just whether product manufacturing stopped—it’s whether order intake and fulfillment delays push revenue recognition into later quarters and increase working-capital and charge risk at the same time BSX is running a large restructuring program.
Akzo Nobel’s Dulux owner rejects a £14.5B break-up bid—what that implies for the next price investors should underwrite for global coatings assets
Akzo Nobel rejected a €12.5B all-cash bid from Nippon Paint and Sherwin-Williams tied to splitting the group, arguing the proposal lacked certainty and did not qualify as a “Superior Proposal.” That rejection effectively sets a higher valuation floor for whole-company consolidation of coatings capacity—while also clarifying where “DIY-slow” cycle risk is being priced into deal math for the next would-be buyer.
2026-08-25
The AI data-center buildout’s schedule risk is shifting from permits to field capacity—and it changes who prints margin
As AI megawatt demand accelerates, the bottleneck is increasingly the “build the building” layer: general contractor throughput and the MEP electrical/mechanical labor pool that physically delivers power and cooling. For listed contractors and engineering-services firms, that translates into a different margin map than the chip stack: working-capital intensity and execution reliability start to matter more than design throughput alone.
New home sales jump into a confidence wobble: what Richmond Fed manufacturing says about the “slowing, not breaking” consumer right before the July PCE reset
Today’s macro stack—July new home sales, Conference Board consumer confidence, and the Richmond Fed manufacturing survey—tests whether housing’s rate-driven bottom is durable or just a temporary demand lull. The key investor question is whether confidence is stabilizing for the same consumers who can now buy new homes, or whether spending risk is shifting from the calendar into the PCE/PPI window.
Canada’s 15% retaliation is a consumer-durables and electronics hit—so margins, not energy, are what US investors should model next
Canada’s Aug. 25 retaliation package sets 15% counter-tariffs on US steel, dairy, appliances and electronics effective Sept. 8, contradicting the prior read that pressure would mainly land on oil/uranium/potash and power. For US-listed suppliers to these categories, the near-term question shifts from energy spreads to tariff-driven demand and pricing power—with a second risk layer emerging from Trump’s threatened 50% auto tariffs starting Jan. 1.
HVDC’s “unmapped toll” is landing in converter stations and XLPE cable, not reactors—because PJM is already pricing grid pain at ~$6B/H1 and AI will have to pay it again
PJM’s transmission-constraint costs surged to $6 billion in the first half of 2026, turning congestion into a near-cash “toll” for any AI load that arrives without enough long-haul transfer capacity. The bottleneck chain for adding that capacity is concentrated: converter stations plus XLPE land/subsea cable (and the HVDC transformer scope around them), where multi-year backlogs and long lead times translate grid buildout into a pricing-power opportunity.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.