Materials & Supply Chain
Raw materials and the chokepoints that price them
Lithium, rare earths, copper and shipping — permits, export bans and capacity, followed to the miners and manufacturers on either side.
2026-09-18

Manufacturing fell 0.3% in August, ending a seven-month streak. The Fed had hiked 25bps into it two days earlier.
The Federal Reserve's September 18 G.17 release showed U.S. manufacturing output down 0.3% in August — the first miss after seven consecutive monthly gains — and the categories that broke weren't AI. Motor vehicles (-1.2%), defense & space equipment (-1.2%), computers (-1.4%), and construction supplies (-0.7%) all fell, while semiconductors held +12.4% year-over-year. The print landed two days after Fed Chair Warsh's FOMC delivered the first rate hike since 2023, lifting the funds rate to 3.75–4.00%. The streak bulls called an AI buildout was actually reshoring, autos, and defense — and three pillars all rolled over in the same month.
Bessent and He put AI and rare earths on the same table — and that re-prices both
Treasury Secretary Scott Bessent meets Chinese Vice Premier He Lifeng in New York on Sept 19–20 with Nvidia's China access and MP Materials's price floor on the same agenda, four days before the Trump–Xi summit in Washington. The unusual pairing — AI competition and rare-earth licensing at one negotiating table — exposes the only durable leverage each side actually has: China's grip on heavy rare-earth refining, and Washington's grip on the chips that train frontier models. Investors should expect a working group, not a grand bargain; the immediate read-throughs are to MP Materials, USA Rare Earth, Nvidia, AMD and Micron.
GM Built a Patriot Part in 22 Days — Auto Capacity Just Entered the Munitions Supply Chain for Good
GM Defense delivered its first PAC-3 MSE interceptor housings to Lockheed Martin on August 28 — twenty-two days after the contract was signed, instead of the several months a typical aerospace supplier needs. The shipment is the first concrete evidence that the Pentagon's industrial-base pivot is pulling civilian auto-OEM capacity into the $58.6 billion, seven-year Patriot framework, and it reframes General Motors's 2026 guidance of roughly $700 million in defense revenue and positive EBIT as the floor of a much longer-cycle structural margin story — not an EV-cycle hedge.
Trump's $4B Oklahoma Smelter Is a Federal Aluminum Quid Pro Quo — and the Downstream Is Now Collateral
The Inola 'Oklahoma Primary Aluminum' project — EGA 60% / Century Aluminum 40%, a $500M DOE grant and a Trump Section 232 proclamation that halves the import tariff for onshoring-approved companies — locks in a multi-year US aluminum premium by doubling domestic primary capacity on paper while keeping the 50% tariff wall up for everyone else. First metal won't arrive until late this decade, but the plumbing downstream — Alcoa's $5.6B South32 acquisition, Constellium and Hindalco/Novelis's multi-billion rolling expansions, and the levered can makers Ball and Crown Holdings — is already being repriced.
Manufacturing's Seven-Month Streak Just Snapped — and the AI Buildout Wasn't Big Enough to Hide It
U.S. factory output fell 0.3% in August, ending seven straight monthly gains and missing Reuters-polled expectations of +0.3%, with the Federal Reserve's G.17 release showing the weakness concentrated in motor vehicles, defense and space equipment, business equipment, and construction. The AI-linked information-processing line — up1.2% — only partly offset the broad cyclical roll-over, leaving the print a hard split between AI-supported and traditional manufacturing. With the Fed having just hiked 25bp on Sept. 16 and the dot plot still pointing to another 25bp by year-end, the report forces a reckoning for the goldilocks thesis: investors must now price AI-buildout strength separately from cyclical industrials.
2026-09-17
2026-09-16
Apple and HP Can Eat the Memory Bill. Xiaomi and Transsion Can't.
Combined Samsung Electronics and SK Hynix memory inventories fell below 10 days as HBM4 absorbs ~3× the wafer capacity of standard DRAM, and the squeeze runs into 2027. Memory now eats ~35% of HP's laptop BOM and over 60% of a sub-$400 smartphone's BOM — a margin shock Apple and HP can pivot around, but smaller OEMs like Xiaomi and Transsion cannot. The trade is the memory oligopoly versus a smaller, more concentrated consumer-hardware market that emerges by 2028.
Diesel Just Made Rail the Cheaper Lane: Quantifying the 2026 Truck-to-Rail Modal Trade
Union Pacific CFO Jennifer Hamann publicly confirmed the modal shift on Sept. 16, 2026, the same week EIA diesel hit a record $5.967/gal. With truckload cost-per-mile now north of $0.81, intermodal economics have flipped decisively toward rail — CSX and NSC posted 9% and 5% intermodal volume growth in Q2 2026 while JBHT's fuel bill jumped 53%. The first quantifiable margin trade of 2026 is rail over truck.
2026-09-13
Buffett's $37B 'mistake' is now a $100B castings monopoly — and the supply-chain read explains why
Berkshire Hathaway's Precision Castparts, written down by ~$11B in 2020, is now worth close to $100B per Barron's, rerated not because of cyclical aerospace recovery alone but because competitors are paying 26x EBITDA for the same bottleneck. GE Aerospace's $11.75B bet on Consolidated Precision Products on September 8 — which wiped 10.7% off Howmet Aerospace — put a market price on the castings shortage. The supply-chain read for investors is that Boeing, GE Aerospace and Berkshire now sit on the only physical infrastructure that can clear a 12-year, record 16,683-aircraft backlog, and the next squeeze is titanium, where China controls 75%+ of metal output.
Saudi Shut Its Hormuz Bypass After Iraq-Launched Drones — The $104 Brent Tape Is Missing the Real Risk Channel
Saudi Arabia closed its 5 million-barrel-per-day East-West pipeline on Sept. 11 after drones launched from Iraq struck pumping stations near Medina and Riyadh — the same corridor that has carried 64% of Saudi crude exports since the Strait of Hormuz shut during the Iran war. Brent settled Friday at $104.61, down 2.8%, with traders pointing to 10 million bpd still transiting Hormuz and ship-to-ship transfers off Fujairah. That frame is wrong: Iraq-launched drones penetrating Saudi airspace hit internal infrastructure no Red Sea reroute can replace, and any incremental Hormuz risk now has no domestic fallback. Valero Energy, Marathon Petroleum, Phillips 66 and PBF Energy carry the cleanest heavy-sour margin upside, while Frontline, International Seaways and DHT Holdings ride the war-risk premium.
2026-09-12
2026-09-11
Coffee's 'Invisible Glut' Just Punched Through $3 — Why the J.M. Smucker, Keurig Dr Pepper, Starbucks Margin Trade Just Reopened
Arabica has fallen roughly 25% from its July spike of $3.57/lb to ~267 cents on the ICO composite as Brazilian export shipments surge and ICE-certified stocks remain near a 26-year low — the classic 'invisible glut' where origin warehouses bulge while exchange-licensed warehouses stay tight. With the 40% US tariff on Brazilian coffee removed in November 2025 and Brazil's 2026/27 harvest forecast at a record 66.7 million bags (+18% YoY), the deflationary tailwind now flows directly to roasters who locked in hedges at the peak. J.M. Smucker posted 37.1% coffee-segment margins in Q1 FY2027, Starbucks expanded operating margin 430 bps thanks to tariff refunds, while Keurig Dr Pepper's US Coffee segment still absorbed a 36% GAAP operating-income drop — and the EUDR compliance cliff on December 30, 2026 will decide who keeps the gains.
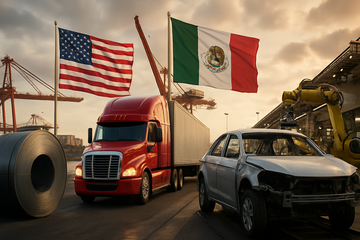
The US\u2013Mexico sprint beats Canada \u2014 and the cheese, steel and auto carve-outs will outlast the midterms
Mexico and Washington are negotiating an interim bilateral trade deal before the November 3 US midterms after Canada talks collapsed, with a likely framework of a 15% auto tariff (~\u22487% effective for high-US-content vehicles), a cap on the 50% Section 232 steel rate, and a quiet concession on Chinese-investment screening. Winners are the listed names already wired into Mexico\u2019s USMCA-compliant supply chain \u2014 Ternium, Grupo M\u00e9xico, Ford, Coca-Cola FEMSA \u2014 while losers are Mexico\u2019s pure auto exporters and any USMCA sunset clause that would strip the 16-year regional backbone.
2026-09-09
GE Aerospace’s $11.75B castings move reframes delivery risk as a margin lever—because it attacks the bottleneck, not the symptoms
GE Aerospace agreed to buy Consolidated Precision Products (CPP) for $11.75B to expand mission-critical castings capacity and support a stated >30% airfoil demand outlook. The deal’s $200M net synergies target and “yield/productivity” capacity levers suggest the company is pricing delivery reliability as an income-stream, not a one-off cost. For the broader US aerospace supply chain, the signal is clear: constraint-heavy components are becoming vertical-integration targets, and OEM delivery-risk assumptions are likely to be repriced in contract negotiations.
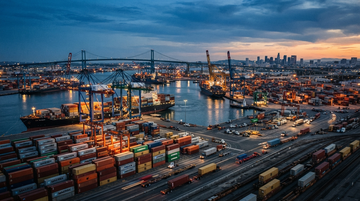
Port of LA's 3-month record is a tariff-and-fuel arbitrage clock — and it's already winding down
The Port of Los Angeles just posted its busiest three consecutive months in history — 2.9 million TEUs across June, July and August 2026 — but every container in that record represents a holiday good pulled forward to dodge August's new 10–12.5% tariffs and the Iran-war diesel surge past $5.85/gallon. Retailers and freight bellwethers caught the arbitrage: Walmart booked $2.9B in IEEPA tariff refunds, Target absorbed a $994M refund benefit, and J.B. Hunt printed 22% intermodal growth. The catch: NRF forecasts September imports to drop 5.7% YoY and October 13.2% — meaning Q4 freight volumes, fuel surcharge revenue, and the trade-deficit tailwind all reverse together.
2026-09-08
2026-09-07
2026-09-06
Sigma Lithium just lost its Brazilian permits again — and the ruling exposes who really wins in a Western lithium cycle
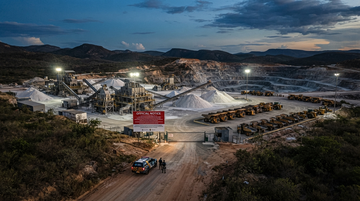
On September 5, 2026, a Brazilian court suspended every environmental permit for Sigma Lithium's Grota do Cirilo mine, the fourth legal shock in eight months, even as Albemarle's Q2 print revalidated the lithium cycle and the DFC funnels billions into Western-miner alternatives. The ruling doesn't move global tonnes meaningfully, but it re-prices Brazilian jurisdiction risk inside a market that has spent a year betting on policy-backed US supply: Sigma Lithium trades at a discount for the right reason, Albemarle and Lithium Americas collect the spread, and downstream battery makers face a louder case for sourcing from DFC-aligned projects.
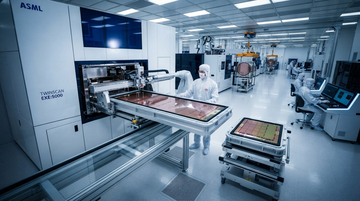
TSMC's 20-fab buildout shows the AI-demand worry is obsolete — equipment is the bottleneck
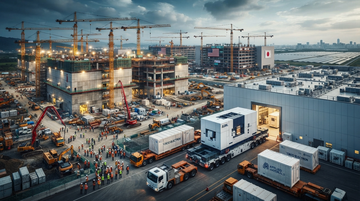
TSMC is constructing 13 fabs in Taiwan and 5-6 overseas simultaneously, with 2026 capex lifted to $60-64B and equipment procurement demand up 90% in eight months. Q2 2026 gross margins hit a record 67.7% and NVIDIA has locked in 60% of CoWoS output, so the binding constraint has flipped from demand to ASML, Tokyo Electron and the rest of the equipment chain. Investors should size positions to the equipment suppliers and the customer anchors, not the foundry itself.
2026-09-05
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.