Materials & Supply Chain
Raw materials and the chokepoints that price them
Lithium, rare earths, copper and shipping — permits, export bans and capacity, followed to the miners and manufacturers on either side.
2026-10-19

Forge Nano Just Put Atomic-Layer Materials on the US Tape. The $199M Trust Walkout Resets the Math.
Archimedes Tech SPAC Partners II shareholders cleared the Forge Nano merger 93.3%–7.2% on Oct 16, sending the atomic-layer deposition specialist public as NANO/NANOW within days. The headline $1.2B pre-money valuation hides a real squeeze: $199M of trust cash was redeemed just before the vote, slashing the planned cash-to-balance-sheet from $417M to closer to $218M, and management is committing that thinner pool to a 3 GWh battery gigafactory that won't produce a cell until 2028. The investment angle isn't the SPAC vote itself — it's the structural pull on Lam Research, Applied Materials, Tokyo Electron, ASM International, and the silicon-anode defense-battery thesis that just got its first pure-play feedstock.

Cleveland-Cliffs' $575M Q3 EBITDA Doubles From Q2 — AI Data Centers Are Pulling US Steel, but 14x Net Leverage Is Why the Stock Still Sits at $12
Cleveland-Cliffs steps into the Q3 2026 print today with guided adjusted EBITDA of roughly $575M, more than double the $286M it actually booked in Q2, against hot-rolled coil at $1,356/ton (+67% YoY) and a 50% Section 232 tariff that's turned the US flat-rolled market into a near-domestic-only pool. The same setup exposes Cleveland-Cliffs's defining handicap: $7.70B of long-term debt and a TTM net-debt-to-EBITDA near 14x, against Nucor's 0.8x and Steel Dynamics's 1.2x. The AI-steel trade is real across the cycle, but Cleveland-Cliffs carries the most debt and the most captive upside from being the only major domestic GOES producer, while the September Stelco idling of Hamilton sits inside the Q3 numbers as the next big wildcard. Read-through: GE Vernova and Hubbell downstream, with Nucor and Steel Dynamics printing Oct 20 and Oct 26 as the cleaner-exposed comparables.
Rare-Earth Recycling Just Got Its First US SPAC — HyProMag's Listing Could Be the Sequel
Three rare-earth and critical-minerals SPACs are racing to a US tape right as China tightens its grip and Washington opens the wallet. Hall Chadwick's REEcycle deal has already signed to claim the first US-listed pure-play rare-earth recycler; Kensington Capital's Nth Cycle follows at a $585M enterprise value; and Mkango's Songwe/Pulawy mining cousin is in registration under the MKAR ticker. HyProMag USA, the recycling vehicle the original brief focused on, is still pre-deal — its announced strategic review points to a late-2026 or early-2027 listing after Texas hub construction milestones, not a wrap on a SPAC today.

$108 Diesel Crack, Then a Waiver: The Refining Trade Meets Its October 22 Reckoning
Trump's Oct. 16 executive order waived the sanctions that kept Russian diesel out of global markets — but Russian refineries, damaged by Ukrainian strikes, cap actual flows near 100,000 bpd. Valero, Marathon Petroleum and Phillips 66 are sitting on a Gulf Coast diesel crack spread at $108/bbl, the 99th-percentile reading on a 40-year chart, and start reporting Q3 earnings on Oct. 22. The supply-shock premium that supported their multiples was priced on an assumption the White House just revoked.
2026-10-18
2026-10-16
$1,255/Ton Hot-Rolled Coil Is a US Steel Pricing-Power Story, Not a Trade Story
Trump's 50% Section 232 tariff has collapsed finished steel imports 8.5% year-to-date through September 2026 per AISI, lifting hot-rolled coil to a four-year high — and handing Nucor, Steel Dynamics and Cleveland-Cliffs a structural pricing floor their Q2 results only partly reflected. The same mechanism is squeezing Ford and General Motors working capital into 2027, while Berkshire Hathaway's 52% August cut to Nucor is the smart-money counter-signal the bulls have yet to reconcile.
Banga's $19 Billion Critical-Minerals Plan Pulls the Refiners and Project-Finance Banks the DFC Couldn't Reach Into the Tent
World Bank Group president Ajay Banga announced a $19 billion critical-minerals financing target for fiscal 2026–2030 — roughly five times the $3.6 billion deployed in fiscal 2021–2025 — anchored to IFC direct loans, MIGA guarantees, and a fresh slate of country compacts with 20 mineral-rich developing economies. The mandate reaches a layer the DFC's $3 billion program didn't: refining IPOs like Nth Cycle, commodities traders like Trafigura, and project-finance banks like HSBC, Deutsche Bank, and Standard Chartered, which the IFC and MIGA now routinely co-lend with. Investors should track the first multi-billion-dollar IFC package and the first MIGA-backed trade-finance facility that flows from the compacts as proof the 5x target is real.
2026-10-15
2026-10-13
AI is rebuilding US factory payrolls and reviving SF/NYC office leases — the building trades are the lever
Three years into the AI capex cycle, US manufacturing has added 72,000 jobs since its December 2025 low, specialty trade contractors another 86,000 over the past year, and AI tenants now absorb roughly half of new San Francisco office leases. The transmission runs through electrical and mechanical construction firms, power-equipment suppliers, and Manhattan-centric REITs — not the hyperscalers themselves.
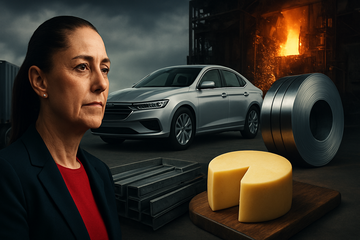
Sheinbaum's Pre-Midterms Pledge Just Put a Price Tag on Mexico's Auto, Steel and Dairy Concessions — and General Motors, Nucor and Kraft Heinz Are Already on the Wrong Side of It
President Claudia Sheinbaum said on Oct. 13, 2026 that Mexico will buy more U.S. goods and cut non-U.S. sourcing to close a Trump trade deal before the Nov. 3 midterms — a concession that now sits on top of an interim package taking light-vehicle tariffs from 25% to 15%, leaving steel and aluminum at50%, and forcing a fight over European cheese names that threaten $1B of U.S. dairy exports. The transmission into markets: General Motors, Ford and Stellantis win if the auto carve-out sticks; Nucor, Cleveland-Cliffs and Steel Dynamics lose any deal that halves the 50% metals tariff; Kraft Heinz, Tyson Foods and Saputo get their cheese-name dispute resolved or lose access; Sempra and Cheniere Energy are the cleanest beneficiaries of the South Korea-style energy ask (already ~75% of Mexico's gas demand is U.S.). Investors should price the deal's political half-life, not its economic substance.
2026-10-12

2026-10-09
Nikkei Just Turned Apple's Memory-Cost Story Into a Demand Story
Apple cut October component orders for the iPhone 18 Pro and iPhone 18 Pro Max by 15-20% after raising prices more than 10% across the lineup to absorb memory costs that surged roughly 400% year over year. The Nikkei scoop reframes Apple's fiscal Q3 iPhone revenue beat of 21.7% as ASP pass-through, not volume strength — and creates a clean winner-loser split: SK Hynix and the broader memory complex are insulated (2027 capacity already sold out to AI customers), while LG Display, assemblers, and the iPhone Pro Max supply chain absorb the cut.
44 EU Industry Groups Just Signed the Trigger Letter — Why US Steel, Chemicals and Defense Are About to Sit in the Same Risk Channel
Forty-four European industry associations urged the EU on Oct. 8 to activate every trade-defence tool available against Chinese overcapacity, ahead of an October 15–16 leaders' summit where France and Germany are pressing for a US-Section-301-style rapid-response instrument. The move mirrors the 2018 US pattern — industry filings into Washington preceded a binding 25% Section 232 steel tariff — and turns Europe's rhetorical defence into a credible binding threat. Combined with US Section 232 derivatives at 50% on 407 product categories, this pulls Nucor, Cleveland-Cliffs, Steel Dynamics, Dow Inc, LyondellBasell, General Dynamics and Lockheed Martin into a coordinated Transatlantic defensive wave that props up US margins and lifts defense demand.
2026-10-08
2026-10-07
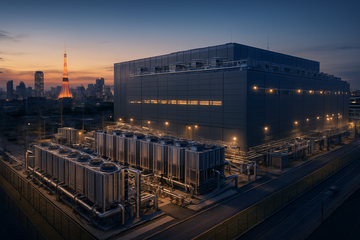
Blackstone's AirTrunk Drops $1B on Tokyo AI Campus as Japan Becomes the APAC Hyperscale Spillover From US Power Constraints
On October 7, 2026, Blackstone-backed AirTrunk committed an additional $1 billion to retrofit its 300+ MW TOK1 campus in Inzai with liquid cooling — the first Japan site purpose-built for large-scale AI workloads. The outlay stacks on a $1.24B green loan from March and an $8B Japan plan, reframing Tokyo not just as a cloud colo market but as the natural APAC landing pad for AI capacity that cannot get permitted, powered, or cooled in the US. The investable consequences run through Blackstone, Daiwa House Industry (GC and equity partner on TOK1), the liquid-cooling complex led by Vertiv and Eaton, and Japanese power-heavy assets like Tokyo Electric Power — while Equinix and Digital Realty face a faster Japan-build-out than they had underwritten.
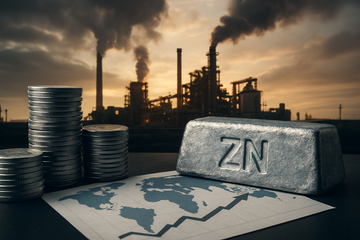
China's 40,668-Ton Zinc Wave Capped the LME Squeeze — The Real Shortage Has Moved West
Chinese refined-zinc exports of 40,668 tonnes in August — the second-largest monthly total in almost 20 years — have drained the LME squeeze and rebuilt inventories 44% in seven weeks, but Teck Resources, Glencore and Nexa Resources now sit on top of a 300,000-tonne deficit the West's own smelters can't refine. With Western refined output down 3.4% YoY, concentrate trading at -$113/ton and Nyrstar's Budel smelter under strategic review, the structural shortage has migrated upstream — and the beneficiaries are the miners, not the smelters.

Vitol just put a $200 target on oil — but the bottleneck isn't Hormuz, it's tankers
Vitol CEO Russell Hardy told the Energy Intelligence Forum on October 6 that a structural tanker shortage — not geopolitics — is the new binding constraint, and could push oil above $200 a barrel if the 12–14M bpd of offshore ship-to-ship transfers out of the Gulf break down. Tanker owners Frontline, DHT Holdings and International Seaways sit closest to the trade; Valero, Marathon Petroleum carry the refining-margin windfall but face a shipping-cost headwind; EOG Resources, ConocoPhillips and Halliburton face the capex-discipline question the market hasn't yet answered.
2026-10-06
2026-10-05
2026-10-02
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.