Materials & Supply Chain
Raw materials and the chokepoints that price them
Lithium, rare earths, copper and shipping — permits, export bans and capacity, followed to the miners and manufacturers on either side.
2026-07-29

2026-07-28
2026-07-27
fairlife’s restart is a supply-chain stress test—and the next “cyber premium” will be paid in packaging, cold-chain, and automation downtime
Coca-Cola says fairlife’s U.S. production was temporarily suspended after a ransomware event and that it is making significant progress restoring operations. Investors should treat the incident as a broader resilience signal: ultrapasteurized capacity is operationally concentrated, so even short cyber downtime can force expensive, fast substitutions across packaging, logistics, and refrigeration networks. The Coca-Cola Company can absorb disruption better than smaller operators—but the higher-probability winners next time are the listed enablers of continuity (industrial automation, cold-chain efficiency, and critical packaging supply).
The 2027 U.S. Critical-Minerals Refining Miss Turns Trump’s China-Decoupling Into a Procurement Backdoor
Reuters’ reporting points to a looming 2027 refining/procurement deadline risk that the U.S. may not meet with domestic capacity alone—forcing quieter concessions to restart flow from China-linked feedstocks. The investable shift is less about “trade with China” headlines and more about how lithium/rare-earth processing economics reprice for MP Materials, Albemarle, and adjacent supply-chain constraints across EV, grid storage, and defense programs.
2026-07-26
FAA’s $2.2B Airline Retrofit Rebate Quietly Turns the Altimeter Upgrade into a 2027 Supply-Chain Price War
The FAA is tying part of the C-band wireless proceeds to a radio-altimeter upgrade schedule by offering up to $2.2B in rebates to eligible airlines that retrofit to withstand 5G interference. That converts what looked like an aviation-safety compliance cost into a structured, time-bounded industrial-policy transfer—creating a near-2027 decision fight between airlines’ fleet replacement plans and avionics upgrade timing, while boosting demand visibility for airframe OEM and avionics suppliers.
Australia’s tariff fight with the US is turning into a US “sovereignty” wedge—making Alphabet’s supply chain and AI compute customers the next battleground
The US raised the tariff on Australian exports to 12.5% effective 24 July 2026 as part of a forced-labour Section 301 action, and Prime Minister Anthony Albanese said Australia will directly raise the issue with President Donald Trump. For investors, the real risk is not the tariff line—it’s how the compliance/sovereignty framing can spill into downstream tech procurement and “trusted” supply chains, potentially changing demand and contract terms for AI and digital infrastructure.
Nvidia’s SK Hynix $500B-style memory lock-up reframes HBM as a contracted utility—tightening the HBM choke point for every other AI GPU maker
Public reporting confirms Nvidia has secured advanced AI memory supply from SK hynix via a multiyear technology partnership announced June 7, 2026. The key market impact is structural: when the “input bottleneck” gets prepaid and custom-developed, HBM behaves less like a commodity and more like a utility with allocation power—compressing upside for Micron and Samsung and making AMD- and Broadcom-adjacent supply strategies more substitute-constrained.
NVIDIA's Vera Rubin entering full production turns the 2026 AI demand debate into a supply-chain scheduling problem
Jensen Huang’s explicit confirmation that Vera Rubin is “in full production” removes the biggest uncertainty from the AI cycle: whether the post-Blackwell ramp is on schedule. For investors, the reframing is immediate—2026–27 hyperscaler capex and TSMC advanced packaging allocations now map more directly to HBM4 and CoWoS throughput timing, not just product positioning.
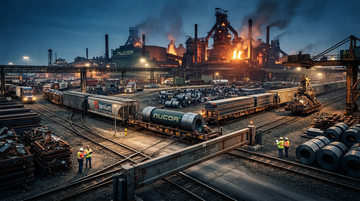
USMCA’s Steel Tariff “Mirror” Push Turns North America into a Tariff Bloc—And It’s the Working-Capital Story for Nucor, Cleveland-Cliffs, and Ternium
A key USMCA dynamic is shifting: the US is using the 2026 USMCA review as leverage over metals and market access, not just arguing about “free trade” rules. For steelmakers, the investable angle is not only pricing power—it’s whether tariff volatility forces contract repricing, reroutes scrap/inputs, and changes working-capital turns inside the North American steel supply chain.
2026-07-25
2026-07-24
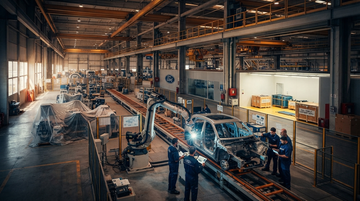
Geely’s “No-Brand-Print” Play in Spain: China EVs First Enter Europe by Taking Over Ford’s Idle Capacity—Not Buying a Publisher-Brand
Geely’s agreement to use Ford’s Almussafes plant in Valencia to produce Geely EVs creates an EU-manufacturing “origin story” that Reuters links directly to avoiding EU tariffs on Chinese EV imports. The real supply-chain message is capacity arbitrage: idle European lines get monetized by China volume, shifting battery/material demand toward whatever can qualify for the JV’s EV ramp instead of whichever OEM owns the logo.
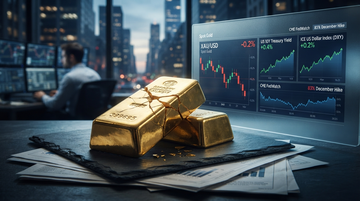
Gold’s “Last Safe Haven” Breaks: Fed-Rate Bets + a Firmer Dollar Can Make Geopolitics Look Secondary
Gold’s recent drop is a clean example of the yield/opportunity-cost channel dominating the hedge narrative: Reuters links the move to firmer USD and rising expectations of Fed hikes, with benchmark 10-year yields up. When gold stops serving as a hedge against rates—and instead loses to higher discount rates and stronger currency—miners and gold-backed flows face a different (and more actionable) set of risks than oil-shock headlines imply.
Newmont’s Q2 Beat Converts Gold Into a P&L Hedge (Not a Trading Call)
Newmont’s Q2 showed how a higher realized gold price flowed through to earnings while the cost stack stayed disciplined: $4,414/oz realized gold with gold AISC of $1,938/oz and 1.181M attributable ounces. The result is a tighter, more hedge-like earnings sensitivity to macro shocks (rates/oil/geopolitics) than investors often price into gold miners—so the “gold vs. oil” conversation should start with the miner’s per-ounce margin, not just the spot chart.
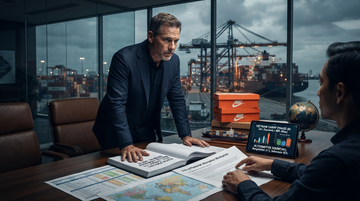
The Vietnam Tariff Shock Is a Margin Bet: Brands Can’t Just “Pay Duty”—They Have to Re-write Contract Math
Vietnam is the apparel exporter that looks most exposed when the U.S. moves from a temporary, broad 10% tariff regime into a higher, country-sliced structure. For the most Vietnam-heavy shippers—like Nike—the spread between Vietnam and alternative sourcing hubs can become a gross-margin event, unless contract pricing and reroute timing are designed to absorb the duty differential.
2026-07-23
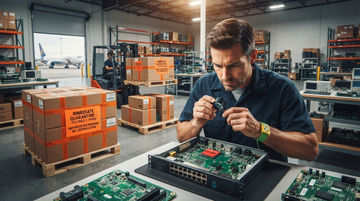
FCC’s “Chinese parts” device ban turns into a replacement-lead-time tax: here’s the compliance checklist for who re-certifies, who loses supply, and who pays delays
The FCC’s move to bar sales of devices containing components from “blacklisted” Chinese firms is best modeled as an equipment-authorization and certification disruption—not just a geopolitical headline. Using FCC’s Covered List mechanics and the communications equipment authorization rules, you can map a practical timeline: upstream testing/authorization constraints force redesigns; downstream buyers then face re-certification and possible sales/importation limits that can translate into margin and delivery shocks.
GE Vernova’s Backlog Is Strong—but the “Margin Leakage” Risk Lives in Equipment Mix and Execution-Cost Timing, Not Demand
GE Vernova reports a growing electrification and grid backlog (RPO) of $44.6B, but the backlog’s margin quality depends on equipment-vs-services mix and how execution costs and timelines hit project-level contracts. In its latest filings, GE Vernova shows large RPO growth concentrated in Power and Electrification equipment (where schedule and cost overruns matter most), while it separately flags tangible cost/timeline pressure in other execution-heavy businesses—an investor analogue for what can go wrong. The actionable takeaway: treat backlog growth as necessary proof of demand, and backlog composition + disclosed execution risks as the real predictor of margin and cash-flow outcomes.
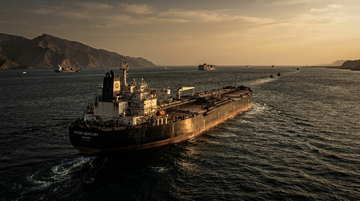
Oil’s “six-week high” is often a shipping-risk repricing: the payoff belongs to tankers and margin-flex refiners, not to everyone holding crude
When Middle East shipping risk rises, part of the crude move is a time-spread shipping-and-uncertainty premium rather than pure physical tightness. That distinction changes who wins: oil-product margins at refiners like Valero Energy and Marathon Petroleum can benefit if product spreads widen faster than feedstock, while airlines such as Delta Air Lines face asymmetric fuel-cost pressure. Conversely, tanker owners like Frontline and Scorpio Tankers tend to capture a more direct shipping-risk revenue pass-through—if the premium persists into the next charter/freight cycles.
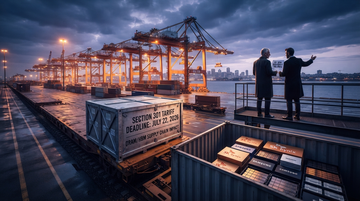
The 301 Tariff Deadline Turns SK hynix and Samsung Electronics Into a Contract-Price Risk Trade: the side that can’t pass through loses first
A July 22, 2026 Section 301 deadline doesn’t hit DRAM/HBM like a simple “tax add”—it tests whether memory makers can hold contract volumes and pricing while wafer-level costs and logistics get repriced overnight. Using SK hynix and Samsung Electronics fundamentals, the market is effectively betting that oligopoly pricing power can offset tariff-driven demand/contract leverage shifts faster than costs can be absorbed.
2026-07-22
Shein’s HK IPO Committee Nod Isn’t the Finish Line—It’s a Test of Trust, Supply-Chain Discipline, and Profitability
Shein has cleared a major procedural hurdle: approval from the Hong Kong listing committee, bringing the fast-fashion retailer closer to an IPO window in 2026. For investors, the real question is whether the company can convert capital-markets access into durable margins and governance credibility—at a time when public e-commerce peers like JD.com, Alibaba, and PDD Holdings already trade on very different “path to profit” narratives.
South Korea’s 301 Tariff Deadline Puts Samsung Electronics and SK hynix in the Crosshairs—Here’s the Supply-Chain Math
A mid/late-July 2026 Section 301 forced-labor probe is pressuring South Korea toward a potentially higher-than-expected U.S. tariff rate, with Seoul scrambling to cap the impact. Because Samsung Electronics and SK hynix sell memory and electronics into U.S.-linked demand chains, even a “single-digit-to-mid-teens” tariff can ripple into pricing, contract timing, and working-capital swings well before volumes adjust. The investor takeaway: this is less about whether memory demand collapses immediately—and more about how quickly firms can shift pricing, mix, and inventory risk while U.S. buyers re-source.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.