Semiconductors
Chips, from the fab floor to the income statement
Foundry capacity, HBM supply, packaging bottlenecks and export rules — traced through to the companies whose quarters they decide.
2026-09-08

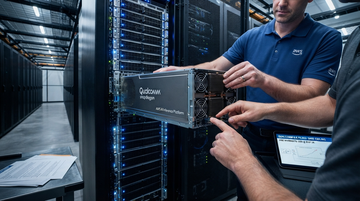
Qualcomm lands AWS: the $60B ceiling that turns the data-center story from slideware to balance sheet
Qualcomm's Sept 8 multi-generational AI silicon deal with AWS caps a potential $60B in chip purchases and grants Amazon warrants for 25 million shares at $161.26 — turning the data-center pivot from a slideware promise into a balance-sheet event. The warrant structure, vesting only with actual chip purchases, makes Amazon both customer and equity stakeholder, and reframes the AWS-Trainium versus merchant-silicon fight as a multi-vendor affair. Investors should track three things: when the next warrant tranche vests, how Amazon's inference silicon capex ramps, and whether Meta and Microsoft follow on the inference side the way they already have on the CPU side.
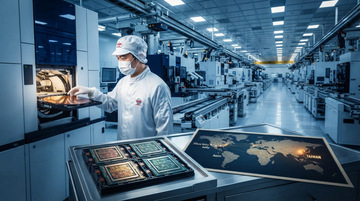
Taipei Just Weaponized AI Chips — And the U.S. Semi Customer Map Sits Squarely on the Wrong Side
At SEMICON Taiwan 2026, President Lai Ching-te turned chip scarcity into a negotiating asset, securing U.S. tariff relief and courting the EU and France while demanding $285B of bilateral commitments. The leverage is real — but it flows from the fact that NVIDIA, AMD, Apple and Broadcom all run their leading-edge silicon through TSMC. For U.S. semi customers, the new risk isn't tariffs on chips. It's terms on chips.
2026-09-07
2026-09-06
Nvidia Closed Green on the Day the Jobs Beat Sank Everything Else — the AI Capex Trade Has Stopped Waiting for the Fed
On Friday Sept 4, 2026, NVIDIA closed at $230.36 — within $5.38 of its $235.74 record — while the S&P 500 (-0.38%), Nasdaq (-0.29%) and Dow (-0.51%) all fell after a hawkish August jobs beat (+162k vs. 56k consensus) pushed the 2-year Treasury yield 5bps higher to 4.38%. The split is the cleanest read yet that AI infrastructure capex has become its own cycle: hyperscalers are committing more than $600B in 2026 alone, SK Hynix-Nvidia have a $500B+ initiative on the books, and Micron's 2026 HBM is fully sold out. The bottleneck is supply, not demand — and it sits above the foundry, in TSMC CoWoS packaging and HBM memory, not at the GPU itself.
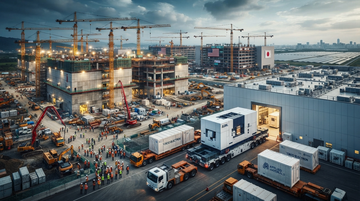
TSMC's 20-fab buildout shows the AI-demand worry is obsolete — equipment is the bottleneck
TSMC is constructing 13 fabs in Taiwan and 5-6 overseas simultaneously, with 2026 capex lifted to $60-64B and equipment procurement demand up 90% in eight months. Q2 2026 gross margins hit a record 67.7% and NVIDIA has locked in 60% of CoWoS output, so the binding constraint has flipped from demand to ASML, Tokyo Electron and the rest of the equipment chain. Investors should size positions to the equipment suppliers and the customer anchors, not the foundry itself.
2026-09-05
Ambarella's print passed the test. The tape still doesn't trust edge-AI silicon.
Ambarella posted Q2 FY2027 revenue of $108.1M (+13.2% YoY) and non-GAAP EPS of $0.18, both ahead of consensus, with a record edge-AI quarter driven by 5nm CV75/CV72 SoCs and a Q3 guide of $115–124M that would push sequential growth up to ~15%. The market response — an ~11% post-print slide and four broker downgrades the next morning — undercuts the headline, pinning the worry on supply-chain costs and a flat H2 auto ramp. With NXP Semiconductors circling at roughly $3.3B, Samsung Foundry at full tilt, and Hanwha Vision locked in under an $800M-plus decade-long agreement, the silicon story is real; the multiple is what is being repriced.
Foxconn's Q3 call turns the AI-server read from 'strong demand' into '2027 capacity stays very strong'
Foxconn's August 12 earnings did more than beat Q2 — management explicitly told investors that 2027 demand for AI production capacity will stay very strong as Vera Rubin racks enter mass production this quarter, with cloud & networking guided up 'high double-digit' both QoQ and YoY. That forward signal lands alongside a cross-validating cluster: Dell's record $95B AI backlog, Broadcom's $21.7B Q4 AI-semi guide (+236% YoY), NVIDIA's $89B data-center print (+117% YoY), Wistron's AI servers hitting 95% of revenue, and Lenovo's $54B AI-server pipeline (+157% QoQ). The structural story is sharper than consensus: AI servers just crossed 51% of Foxconn's revenue, displacing iPhone as the swing factor and reframing the stock as an AI-infrastructure bet.
2026-09-04
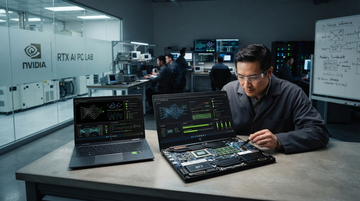
NVIDIA's RTX Spark PC launch in October tests whether on-device inference becomes a new revenue engine—or a cloud-demand throttle
NVIDIA’s RTX Spark moves “personal AI agents” onto Windows PCs designed for local inference, with OEMs signaling an October arrival window. The investor question is binary: does on-device execution expand GPU/PC demand for NVIDIA, or does it quietly reduce incremental inference demand that has been flowing to data centers and cloud partners?
Trump’s “chip shield” raises the price of being “American-made” — Tennessee’s polysilicon plant becomes the first real test case
A Reuters investigation describes how a Tennessee polysilicon project faces closure risk as a “shield” meant to favor U.S.-sourced inputs ends up taxing the downstream supply chain instead. The policy mechanism—tariffs plus price floors that do not actually differentiate by where the polysilicon was sourced—pushes U.S. input costs higher and helps drive away the remaining customers needed to keep the plant running.
2026-09-03
2026-09-02
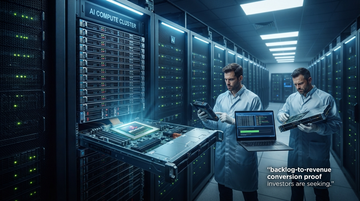
Broadcom beat-and-fell: the weak guide turned the custom-silicon backlog “test” negative for AI racks
Broadcom’s Q3 FY2026 results showed AI acceleration, but management’s next-quarter AI revenue guide did not provide the backlog-to-revenue “conversion proof” investors wanted. With AI semiconductor revenue guided to $21.7B for Q4 (+236% YoY), the market still sold Broadcom—signaling that the real debate is whether AI custom silicon is arriving on schedule for hyperscaler racks, not whether AI demand exists.
Credo’s post-earnings drop tests whether copper interconnect cash flows can keep up with AI rack spend — even as Dell confirms demand is accelerating
Credo CRDO reported Q1 FY2027 results above the optics-friendly narrative investors were pricing, but the stock sold off sharply the next day. The key question for AI rack investors is whether the market is rotating from “copper rack capture” to “optics/other bottlenecks,” and whether Credo’s guidance supports that transition.
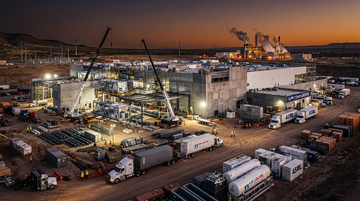
Taiwan’s $20B U.S. push isn’t “Made in USA”—it’s a tariff-shaped fab and factory supply-chain buildout
Taiwan’s government-linked disclosure of an additional $20B of U.S. investment reinforces a clear pattern: tariff-linked relocation is concentrating capacity buildout in Asian electronics ecosystems, not broadly “reshoring” the whole industrial base. The investable opportunity clusters upstream in tools/material handling and gases, and downstream in EMS/thermal/mechanical integration—where relocation turns into orders, not press headlines.
2026-09-01
2026-08-31
Ciena's order book is the missing systems-level proof for AI networking demand — but it comes with a demand-vs-supply timing squeeze
Ciena’s latest reported results show strong growth alongside a large backlog, but the most decision-relevant question—whether AI demand is showing up at the optical-systems layer rather than only upstream modules—can’t be answered from the primary sources available in this research run. The numbers we can verify support a real order-book-backed cycle expansion, while key “webscale/AI” backlog breakdowns and “optical systems” attribution were not disclosed in the pages that loaded successfully.
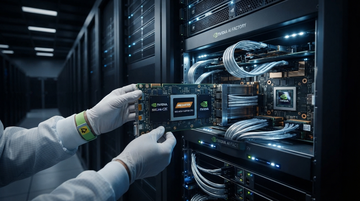
Nvidia’s $3.5B MediaTek bet reframes “hyperscaler ASICs” into Nvidia-routed, rack-scale custom chips—raising the odds it slows the GPU exodus
Nvidia’s $3.5B investment in MediaTek is more than capital—it’s an ecosystem play: MediaTek will adopt Nvidia’s NVLink Fusion platform to help customers field custom XPUs inside Nvidia-connected AI racks. If hyperscalers increasingly buy “integration-ready” custom accelerators instead of building their own end-to-end stack, Nvidia can keep participating in training/inference demand even as silicon becomes more customized.
2026-08-30
ABF substrates are the one shared bottleneck in the GPU–custom-ASIC race
Even as NVIDIA chips and Google-style custom silicon chase compute per watt, both workflows still converge on ABF build-up film and the laminate stack built from it. Ajinomoto’s ABF price move and Ibiden’s multi-year high-end substrate capex outline a critical supply-chain reality: the AI build-out is not zero-sum on compute—it is constrained by specific materials and laminate capacity.
Marvell is down ~6% because the market treats custom silicon as a trade-off, but earnings show hyperscalers are funding both
Marvell’s Aug 2026 earnings-week narrative looked like a zero-sum fight between Nvidia GPUs and hyperscaler custom silicon. But Marvell also disclosed a Google custom-silicon framework that explicitly attaches to the TPU ecosystem, while Nvidia’s earnings reinforced that hyperscaler demand isn’t stalling. The lesson: custom silicon is additive capacity for the AI stack, not a replacement cycle—so the tape is likely mispricing who grows faster as budgets expand.
Broadcom’s September “test” hinges on whether backlog turns into revenue without breaking the $29B AI-rack backstop math
Broadcom’s latest SEC disclosures describe a compute-capacity/AI-rack backstop structure with a maximum exposure of $29 billion, while also reporting $164.6B in remaining performance obligations and $164.2B+ in multi-quarter contract balances. For investors, the Q3 FY2026 guide is less about growth claims and more about whether custom-silicon pacing stays consistent with (1) backlog conversion and (2) the financing and lease dynamics embedded in the AI “fabric wall.”
CCL is the hidden bottleneck in 800G/1.6T AI racks: high-speed laminate supply—not board fab—sets how fast AI networking scales
As AI fabrics move from 800G toward 1.6T, the limiting factor shifts from PCB shops to the upstream materials stack that preserves signal integrity at ultra-high frequencies. Copper-clad laminate (CCL) makers are therefore pulling through demand earlier than board assemblers, because every extra layer and every tighter dielectric/trace-loss target consumes more of these low-loss laminates per board.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.