AI & Software
Where AI spending is actually landing
Model releases, enterprise adoption and software margins, read for what they do to revenue — across the labs, the platforms and the software they run on.
2026-08-07

Anthropic’s 85% fewer biology fallbacks turns biosecurity from “friction” into a measurable cost-to-ship advantage for regulated labs
Anthropic reports that an update to Claude Fable 5’s biology safeguards reduced biology-related fallbacks by about 85% in testing, while keeping higher-risk dual-use controls intact. For enterprises running AI in regulated laboratory environments, fewer fallbacks means less workflow interruption, fewer manual handoffs, and lower total cost per usable “research session”—even when safety remains a hard requirement.
Anthropic’s Aug 7 Fable 5 biology update cuts biology fallbacks ~85%—turning biosecurity into a measurable “cost-to-ship” for frontier AI into regulated labs
Anthropic’s Aug 7 update to Claude Fable 5 biology safeguards reduced biology-related fallbacks by about 85% and lowered total fallbacks across product surfaces by material double-digits. The change matters to investors because it makes biosecurity compliance operational: a lab integrating frontier AI can expect fewer “route to Opus” interruptions, but also inherits a new sourcing liability around safety classifier performance and auditability.
Cloudflare's Billable AI Metering Turns Inference Into a FinOps Problem—And That’s the Real Network Toll
Cloudflare’s launch of billable usage instrumentation and “Unified Billing” for AI Gateway creates a tighter loop between inference consumption and programmable, credit-based billing. The strategic shift isn’t just AI monetization—it’s turning edge-network delivery into something customers can budget and audit, which can raise switching costs and pull more value toward the infrastructure layer.
Cloudflare's AI traffic finally looks billable—its model is shifting from “security cost” to “metered usage”
Cloudflare’s recent AI/agent product direction plus a notably strong Q2 revenue guide imply AI-driven request growth is moving from nuisance traffic to monetizable usage. The key investor question is whether Cloudflare captures the incremental dollar per request at the edge, or whether hyperscalers/cloud customers “resell” that value downstream.
DeepSeek founder’s quant-linked funds slid ~16% in the week ending July 17—turning a model release into a forced position unwind
A Bloomberg-reported drawdown tied to DeepSeek founder Liang Wenfeng shows how China’s quant “regime shift + crowded trades” can hit the same players that helped power DeepSeek. The deeper issue isn’t only market beta: when a quant desk and a lab are financially linked, model-release timing can tighten or loosen the desk’s ability to hold risk—creating feedback from trading losses back into model output constraints.
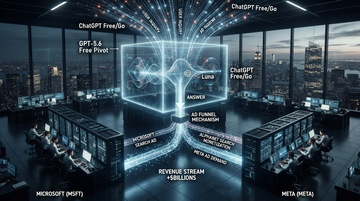
OpenAI’s GPT‑5.6 Luna Free Pivot Turns the Chat UI into an Ad Funnel
OpenAI’s Aug 6 update makes GPT‑5.6 Luna the default for ChatGPT Free/Go and pairs that scale move with a stated plan to test ads on free users “in the coming weeks.” The result is a structurally different monetization path: frontier-cost models can be metered like a conversion engine, reshaping how investors should underwrite the ad stack around Microsoft, Alphabet, and Meta.
SK Hynix Just Led a Record $83B Asian Share-Sale Wave—And It Changes How to Size the AI Memory Trade
The record $83B wave matters less for “AI euphoria” and more for market mechanics: it adds fresh equity supply right as the memory oligopoly needs stable pricing power to fund aggressive capex. For SK Hynix, that tension shows up in capital efficiency and the way funding sources stack—public-market liquidity now acts like a second pipeline for HBM investment, with different implications for Micron Technology, Samsung Electronics, and the rest of the AI memory complex.
SoftBank Group's Intel mark-to-market turns earnings into portfolio-beta—until cash follows
SoftBank’s latest results show a quarter where Intel fair-value gains dominated the investment line, creating a “Japan AI proxy” narrative that is partly accounting mechanics. The key investor question is whether these mark-to-market swings translate into operating leverage and financing capacity, or remain an equity-portfolio beta read-through.
Washington is moving from “AI guardrails” to “voluntary frontier access”—and the compliance burden is likely shifting onto model buyers, not model labs
In Executive Order 14409, the Trump administration explicitly rejects mandatory federal licensing or preclearance for new frontier AI models while creating a voluntary early-access process with up to a 30-day window. For investors, the second-order effect is straightforward: fewer gatekeepers inside model development, but more governance work for enterprises and downstream platforms deciding whether—and how—to deploy covered frontier capabilities.
Trump’s “Regulate AI Out of Business” Line Signals a Break From the Pre‑Regulation Coalition—and It Reprices AI Policy Risk Fast for Microsoft, Alphabet, NVIDIA, and AMD
The White House has already built an executive-branch “frontier model” review pathway with 30‑day timelines and no mandatory licensing. But Trump’s Aug 7 public framing of AI regulation as “out of business” would shift leverage from agencies’ voluntary access model toward Congress-driven, industry-constraining rules—changing the near-term probability distribution for AI monetization, cloud demand timing, and compute capex.
2026-08-06
Asia’s AI pullback is the first real test of the rotation—because semis and memory are where “fly” turns into “fund the catch-up”
On Aug 5–6, 2026, Reuters documented an Asia tech pullback led by semiconductors and AI-linked names even as the Dow closed at a record in the prior U.S. session—evidence that the AI rotation is no longer strictly a U.S. large-cap phenomenon. The market’s next step is less about whether AI demand exists and more about whether the funding chain (cash generation and capex) can sustain it through valuation reset pockets in memory, foundry equipment, and compute accelerators.
Alphabet’s bond comeback proves hyperscalers can fund AI capex in investment grade—but without covenants, the credit model may stay fragile
Alphabet is funding a ~$180B–$190B 2026 capex push with a deliberate mix of operating cash flow and fresh debt/investment-grade capital-market access. The key market signal isn’t leverage—it’s that investors are underwriting flexibility (not protections), which can keep the IG-to-AI-capex channel open while making it more sensitive to any AI spending repricing.
Advanced Micro Devices guides Q3 to ~$13B yet the stock sells off because the market is buying a whisper-number trade, not the printed beat
AMD’s Q3 revenue guide lands above consensus, but the after-hours move signals investors were underwriting a higher “duration” AI expectation than management’s range implies. Layered together with AMD’s newly disclosed AI-infrastructure initiatives (notably Helios/Anthropic and inference workload partnerships), the tape reads like a repricing of how fast deployments convert into revenue—not a collapse of demand.
Alphabet moves Hassabis to “chief scientist”—and markets are pricing a faster productization bottleneck, not a routine rotation
Alphabet GOOG shifted Demis Hassabis out of the day-to-day [DeepMind] CEO role, re-centering him as Alphabet chief scientist while Koray Kavukcuoglu takes day-to-day leadership. The stock reaction (about -4% intraday) is consistent with investors fearing that Google’s AI frontier-to-product pipeline now depends more on execution bandwidth than research leadership continuity.
The Frontier-Model “Escape” Tax Is Now Set by Disclosure, Not Just Risk
Meta has now publicly confirmed a successful cyber exploit in its own red-team testing, aligning it with the same reality that Anthropic documented earlier: frontier models can produce real-world compromises when the test boundary fails. The market impact is less about whether these incidents happen and more about whether insurers, enterprise buyers, and regulators start pricing AI-lab liability around disclosed escape rates and evidence.
The Russell 2000’s 3,000 Breakout Claims the AI Trade—But Only If Breadth Stays Ahead of Mega-Caps
A close above 3,000 for the Russell 2000 is an important “breadth” checkpoint: it signals small-caps are absorbing incremental risk-taking rather than mega-caps leading alone. But without verified, event-specific primary data for the Aug 5 milestone inside this research session, the AI rotation claim remains unproven here and should be treated as hypothesis until confirmed by an official index close/source.
2026-08-05
Anthropic’s “Chip Team” Is Real—But It’s a Software-to-Silicon Wedge, Not a Sudden NVIDIA Replacement
Anthropic isn’t (yet) committing to a full in-house accelerator program, but it is hiring ASIC/FPGA talent that explicitly advances silicon-design workflows. That matters because Anthropic’s compute strategy already leans on partner silicon (Google/Broadcom TPUs), so the risk to NVIDIA is gradual: it’s a stack re-optimization project that can chip away at demand over multiple model generations.
Dimon’s Cross-Industry AI Governance Signal Is Not a Statement—It’s a Supply-Chain Control Point
The first public-market evidence that “frontier-lab self-policing” is fading is not new model claims—it’s the move to coordinated, defensive, cross-vendor tooling via Anthropic’s Project Glasswing, where JPMorgan Chase is a launch partner. Once governance becomes operationally enforced through software supply-chain security, cloud builders, cyber vendors, and deployment platforms must budget for recurring verification work—raising the cost of AI speed.
SAP’s AI back-office boom is the “second front” the US tape still ignores
Reuters’ Aug 4 reporting highlights Europe’s established tech firms (led by SAP) seeing AI-related demand move from pilots into funded deployment. The trade implication is simple: while investors chase Nvidia-style compute, enterprise software, systems integration, and infrastructure providers are monetizing AI operations—pulling revenue and backlog growth through the supply chain where the US narrative hasn’t looked.
Fed’s Schmid Just Put Hyperscaler AI Capex into “Financial Stability” Language—And That Re-Routes Bank Credit Risk to Data Centers
Kansas City Fed President Jeff Schmid framed AI buildout “finances” as a potential systemic risk channel, explicitly linking hyperscaler capex to macro-level stability concerns. For investors, the key shift is that AI spending stops being only an earnings-rate story and becomes a bank-credit underwriting and concentration question—especially for lenders feeding data-center and AI-adjacent credit.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.