Power & Grid
Load growth, and who gets to build for it
Interconnection queues, rate cases, turbines and transmission — what data-center demand is doing to utilities and the equipment makers behind them.
2026-08-31

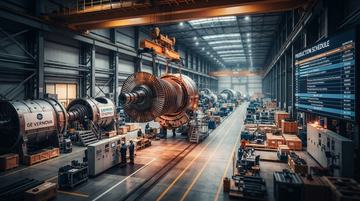
The gas-turbine order book is turning hyperscaler power into a timing bet—OEM slots beat permits by 2027
GE Vernova and Siemens Energy are sitting on huge gas-turbine backlogs while AI-era demand is colliding with unusually tight delivery slots. But the binding constraint for getting megawatts online by 2027 is turning from turbine manufacturing capacity into emissions/permitting sequencing—where delays can strand already-ordered equipment and shift revenue capture toward OEMs with the longest order visibility.
Trump’s bulk-power emergency turns Tesla’s energy stack into the “grid-flexibility” policy floor—Megapack deployments and VPP dispatch rules matter more than Solar Roof tiles
Executive Order 14420 targets national-security risk in U.S. bulk-power equipment (including backup generators) and directs the Department of Energy to implement rules to secure reliability and cyber resilience. Combined with Tesla’s Solar Roof exit from new tile sales, the policy shift increases the market relevance of Tesla’s Megapack and dispatchable flexibility—especially where virtual power plant (VPP) programs convert reliability needs into contracted, dispatch-triggered value.
2026-08-30
AI Data Centers Are Entering a “Cooling Plant” Pricing Regime — Integrated Power + Heat Rejection Designs Can Cut Installation Cost up to 30%
Rack-level liquid cooling gets most of the attention, but every AI megawatt still has to reject heat through the plant mechanical layer: chillers, towers, pumps, valves, and the heat-rejection backbone. A new Trane + Eaton reference design shows why this layer can reprice: it targets up to 15% energy-efficiency gains and up to 30% lower installation costs, shifting value from GPUs to the thermal infrastructure that must scale every new MW.
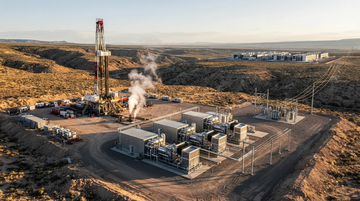
AI’s 24/7 power sprint just found a missing supply-chain map: geothermal’s drill-to-ORC-to-PPA chain
Fervo Energy is converting geothermal from “pilot projects” into bankable 24/7 capacity for AI and data centers—by locking megawatts in PPAs and then moving fast through drilling, permitting, and Organic Rankine Cycle (ORC) equipment. That creates a measurable, investable supply-chain pattern: drill capacity that delivers contracted MW on schedule, ORC turbine/generator OEM scope that scales, and utility-grade offtake economics that are designed to survive the interconnect clock.
The 1kW GPU’s quiet margin engine: VRM/DrMOS power-management silicon is gaining dollars-per-rack faster than the GPU
AWS is planning to deploy 2 million additional NVIDIA GPUs in 2027–2028, while Nvidia’s AI-server pricing was reported to rise by more than 15% as system costs keep climbing. That combination pushes attention from rack-level power delivery to per-GPU voltage regulation—where multiphase controllers, DrMOS power stages, and PMICs are a fast-growing, density-constrained silicon bottleneck.
Iceland’s EU “no” breaks the only slow-moving anchor—Arctic policy now tilts toward power, patrol capacity, and extractive leverage
Iceland rejected restarting EU accession talks by 52.8% to 47.2% in a late-August referendum that opponents framed around sovereignty risks. With the US pressing Greenland through “national security” arguments and NATO simultaneously tightening Arctic posture, the Arctic is shifting from diplomacy-by-institutions toward competition by presence—raising the premium on surveillance, ice-capable lift, and defense supply chains.
2026-08-29
The grid emergency isn’t a power-policy problem—it’s a materials bottleneck upstream of the turbine
The U.S. has framed a national emergency around the foreign supply of bulk-power electric equipment, because reliability can’t wait for long lead-time replacements. At the same time, data-center electrification faces a copper chain strain, while the wind-and-grid buildout still depends on rare-earth magnets. Investors should watch which listed suppliers can convert constrained input availability into backlog, pricing power, and margin support.
Corn and wheat at 3-year highs don’t automatically mean fertilizer margins—Louisiana gas-cost capacity can flip the second derivative in US nitrogen pricing power
With grains strong, the real supply-chain swing is whether US nitrogen pricing tightens or normalizes as new Louisiana capacity moves through permitting and operations. CF Industries’ Blue Point complex and its near-term urea supply plan point to a more local, gas-cost-advantaged margin story that the grains rally can’t price unless fertilizer tightness persists under China-driven export friction.
2026-08-28
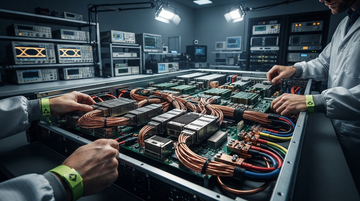
The “dollars per rack” race quietly reorders the BOM: high-speed 224G-grade connectors and 48V power interconnects are becoming the compounding constraint
As AI rack designs push faster copper SerDes and higher bus voltages, the connector/interconnect layer is shifting from “plumbing” to a margin-controlling build constraint. Evidence from TE Connectivity and Luxshare Precision shows 224G connector ecosystems are already being engineered for next-gen switch slot density, while Amphenol reports AI-related strength within IT datacom alongside fast revenue growth.
AI Servers’ Quietest Bottleneck Is the Passive Layer: MLCC + Power Magnetics Can Gain Content Share Even When “Component Strength” Reads False
The passive parts that sit under every GPU power step—MLCCs and power magnetics inside the 48V rack ecosystem—can grow faster than the “GPU-cycle” proxy because higher power density increases decoupling and transient-demand content per rack. Using Murata’s reported financials as a compounding baseline, the investment takeaway is that winners in capacitors/inductors can look steadier than the semiconductor tape, while memory-price volatility can distort how component strength shows up in reported supply chains.
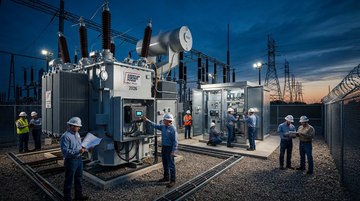
Trump’s Bulk-Power National Emergency Turns Grid Security Into a Mandated Order Book—Transformer, Switchgear, and OT Cyber Winners (and the “who gets paid first” map)
On Aug. 26, 2026, Trump signed an executive order (EO 14420) that makes foreign-produced bulk-power equipment a national-emergency compliance target. The practical effect is a faster, procurement-linked shift from “recommended” grid cybersecurity to hard, equipment-level restrictions and mitigation conditions—reordering cash flows across utilities, domestic integrators, transformer/switchgear OEMs, and OT-cyber vendors.
2026-08-27
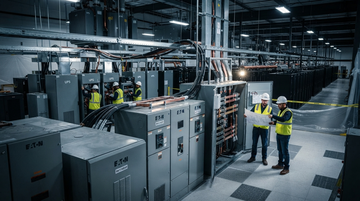
Grid-to-GPU’s new bottleneck isn’t transformers—it’s who can schedule switchgear, UPS and interconnection fast enough to hit data-center deadlines
AI capex is colliding with power-delivery realities that don’t clear on silicon lead times. The result: switchgear-to-UPS-to-interconnection becomes the scheduling choke point where long backlogs, constrained commissioning windows and utility bottlenecks convert into multi-quarter project deferrals and pricing power for a narrow set of electrical-equipment suppliers.
IREN has the miner-to-AI pivot—but the margin test is electricity volatility, not customer contracts
IREN is set to print its FY26 earnings on Aug. 27, 2026, after a year of transforming from Bitcoin mining into AI “cloud services” plus colocation-like revenue. The company’s disclosures already admit electricity price and electricity-market volatility can directly impair margins if it can’t curtail or monetize load at the right times—exactly the risk behind the “miner-to-AI landlord” thesis. The investor question is whether FY26 results (and guidance embedded in the print) show electricity as a controllable pass-through—or a profit killer when spot power spikes.
Rivian’s CFO exit to GE Vernova spotlights a real execution-and-cash tradeoff—EV ramp risk is rising as grid/AI demand pulls finance talent
Rivian RIVN disclosed that CFO Claire McDonough plans to resign effective Oct. 30, 2026, appointing Derek Mulvey as interim CFO. The timing matters: Rivian is already in the R2 ramp phase, while GE Vernova GEV has built its growth story around grid modernization for AI-driven power needs—so the CFO move reads less like a personal career step and more like capital-and-people reallocation.
2026-08-26
Gunvor’s >$1B Haynesville bid flags a gas-trading power shift: feedgas control is the scarce margin
Gunvor is reportedly in talks to buy Haynesville shale assets for more than $1B, a sign that LNG-era economics are pulling trading-house capital into US gas basins. The deal’s implied wager is that the export margin increasingly depends on securing feedgas access (and bottleneck capacity) rather than simply owning more production barrels of hydrocarbons.
Marvell's Q2 FY27 print turns “custom-silicon backlog” into earnings power—or exposes it as optics
Marvell’s Q2 FY27 setup is being judged on whether it converts AI networking “bookings” into sustainable revenue, margin, and cash generation. The only defensible way to tell is to read the print alongside its outlook math: Q2 FY27 revenue guidance centers on $2.7B with a GAAP gross margin range of 52.1%–53.1% and explicit calls for “exceptional AI-related bookings.”
NuScale's TVA deal would be a utility-scale SMR procurement step—if it turns into binding PPAs
TVA and ENTRA1 Energy disclosed an agreement to enable up to 6 GW of NuScale SMR capacity across TVA’s seven-state territory, with ENTRA1 targeting development and ownership and selling electricity to TVA under future power purchase agreements. For investors, the inflection is not the “up to” headline scale—it’s whether this moves from planning to bankable contract terms that translate into revenue and backlog for NuScale while shifting cash-flow economics toward the asset owner and EPC ecosystem.
Zoom isn’t monetizing AI the way the market wants: agent features are proving adoption, not pricing power
Zoom’s Q2 results show steady top-line growth alongside ongoing AI feature expansion, but the earnings evidence does not yet show a clear, separable “agentic pricing” revenue line. The key question for investors is whether Zoom can convert AI Companion/agent workflows into outcome-priced upgrades faster than Microsoft bundles Copilot into Teams-led suites—without sacrificing seat growth.
2026-08-25
HVDC’s “unmapped toll” is landing in converter stations and XLPE cable, not reactors—because PJM is already pricing grid pain at ~$6B/H1 and AI will have to pay it again
PJM’s transmission-constraint costs surged to $6 billion in the first half of 2026, turning congestion into a near-cash “toll” for any AI load that arrives without enough long-haul transfer capacity. The bottleneck chain for adding that capacity is concentrated: converter stations plus XLPE land/subsea cable (and the HVDC transformer scope around them), where multi-year backlogs and long lead times translate grid buildout into a pricing-power opportunity.
OpenAI’s Jalapeño posts 1.5–1.9× more inference work per watt—turning “custom silicon” from an option into a pricing-power threat for NVIDIA
OpenAI published its first Jalapeño inference-chip benchmark results on Aug. 25, claiming 1.5–1.9× more AI work per watt at peak throughput and 1.7–3.6× lower end-to-end latency versus stated comparison systems. Because inference is the spend that scales with live usage, the headline is that OpenAI can potentially shift its next compute build from “GPUs as the default” toward purpose-built accelerators—compressing NVIDIA’s margin cushion just ahead of its Aug. 26 earnings.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.