Data Centers & Cloud
The buildout behind the AI bill
Hyperscaler capex, colocation supply, power, cooling and networking — where the money goes after the GPU order, and which companies book it.
2026-07-30

The EU’s €10B “AI gigafactory” bid turns compute sovereignty into a margin test for US hyperscalers
The EU is preparing to fund firms to build seven AI gigafactories with €10B of public money—an explicit attempt to secure raw AI compute inside Europe. For investors, the actionable question is whether this sovereign capacity forces a pricing and workload-location squeeze on NVIDIA, Microsoft, and Amazon, while turning grid build-out capacity into a near-term bottleneck for utilities and power equipment suppliers like Schneider Electric.
Fitch Calls an “AI Market Correction” a Top Global Credit Risk—So Hyperscaler Downgrades Look Like the First Domino, Not the Last
Fitch’s framing turns AI capex from a company-credit story into a system-credit variable: a potential market correction would hit funding costs, debt rollovers, and even credit quality across sectors and geographies. When paired with the hyperscaler warning line (capex/leases straining near-term credit metrics), it implies bond investors may reprice not just a few mega-cap issuers, but the broader credit “plumbing” that finances the AI build-out.
Meta's El Paso JV with BlackRock turns AI real-estate into pension-backed yield—without making Meta the bank
Meta will move the El Paso campus into a JV where BlackRock-managed funds hold 80% and Meta holds 20%, while Meta becomes the sole tenant via a long lease-back. The deal explicitly shifts AI infrastructure from a pure “capex deficit” debate to a “how cheaply can we finance long-lived boxes” debate—because part of BlackRock’s investment is funded with $12.5B of debt.
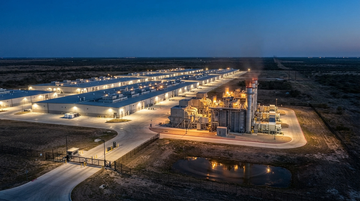
Google's $15B Nexus Loan Is Sovereign Finance in Disguise — and Alphabet's Capex Math Just Got Worse
Alphabet is guaranteeing the Morgan Stanley-led $14B bridge loan on Nexus Data Centers' 1.6 GW Texas gas-powered AI campus for Anthropic, taking ~20% equity in return — the third leg of a $35B+ backstop program that moves frontier compute off Google's balance sheet while keeping it on the hook. With Q2 capex already at $44.9B and free cash flow turning negative, the structure reveals the real constraint: not capital, but the gap between Google Cloud growth and depreciation absorption. Lenders win fees; Broadcom, AMD, and gas-turbine suppliers win volume; the question is what triggers Google's cash calls.
Nscale's $1.65B Anyscale Grab Hands Microsoft a Vertical-Stack Rival It Just Helped Build
London-based neocloud Nscale is buying Ray-creator Anyscale for a reported $1.65B, absorbing the open-source distributed-compute substrate that Microsoft co-engineered as a first-party Azure service just nine months ago. The deal converts a cloud-agnostic Ray ecosystem into Nscale's proprietary full-stack offering, tightening pressure on CoreWeave, Nebius and Lambda Labs while putting Microsoft's $23B Nscale compute commitment on a collision course with the same company's software roadmap.
Seagate didn’t “miss”—it proved the HAMR profit engine… and the market still priced in the harder margin math next
Seagate’s fiscal Q4 blowout (revenue and adjusted EPS both beating expectations) triggered a sell-the-news move that makes the next test less about “more TB shipped” and more about whether HAMR mass-capacity economics hold across the drive build-and-supply chain. For investors, the stock’s reaction matters because it shifts attention from die-count/technology headlines to tray/component margin durability—where suppliers and competing drive OEMs can win or lose first.
2026-07-29
AI hardware is pulling air cargo capacity toward data-center “just-in-time”—and operators with scheduling power are the gatekeepers
In 2025, air cargo transported more than two-thirds of global AI-related goods, making aircraft utilization and slot allocation a strategic bottleneck rather than a background logistics variable. The air-freight scarcity that e-commerce previously dominated is shifting to dense, time-sensitive AI hardware lanes, where the margin moves from shipping volume to capacity control.
Arm’s AI forecast beat indicates the “architecture royalty” flywheel can scale faster than chip unit demand
Arm’s latest guidance/outlook strength can be read as a demand signal that hyperscalers are prioritizing Arm-based AI infrastructure designs—not just buying more chips. The royalty model works only if energy-efficient adoption drives durable Neoverse (data-center) design-in and custom-silicon programs that keep royalty revenue compounding even when hardware supply constraints shift the timing of shipments.
Microsoft’s Cloud Beat Is Real—but AI Revenue Has to Clear a Utilization & Margin Wall
Microsoft’s latest results show cloud growth is strong enough to absorb AI buildout: Microsoft Cloud revenue rose 29% to $54.5B, while Azure and other cloud services grew 40%. The catch is that the same quarter also shows cloud margin pressure from ongoing AI infrastructure investment—so the market will judge the AI conversion not by demand, but by whether utilization and pricing eventually outpace depreciation and cost of revenue.
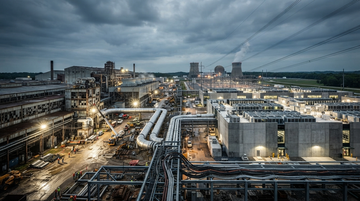
NextEra’s Kentucky “uranium-to-data-center” bet reframes nuclear as grid-speed, not just generation
A proposed $100B-scale NextEra–Brookfield data center campus would repurpose DOE’s Paducah uranium-enrichment footprint into a power-and-compute hub. The investor question isn’t whether nuclear is “clean power”—it’s whether co-locating hyperscale load with a nuclear-linked strategy can compress interconnection and build timelines, shifting value toward NextEra as the project’s grid-speed integrator.
Qualcomm’s data-center pivot is built on handset cash—but mobile weakness is already shaping the funding timeline
Qualcomm QCOM says handset represents roughly one-third of QCT revenues by fiscal 2029, while targeting data-center revenues of more than $15B by fiscal 2029 and $5B in fiscal 2027. The key investable question is whether handset cash generation remains durable enough to fund that ramp through a cyclical, memory-constrained mobile cycle—especially after Qualcomm explicitly expects near-term demand hits from handset supply constraints.
Qualcomm's guidance stress-tests whether handset cash can fund a data-center pivot
In its Q3 FY2026 outlook, Qualcomm guided revenue of $9.2B–$10.0B and non-GAAP EPS of $2.10–$2.30, explicitly baking in memory-supply pressure that hits handset demand. The financial durability question is answerable from cash generation: TTM operating cash flow is $14.285B and free cash flow is $12.502B, but the pivot only creates shareholder value if data-center/edge expansions can offset handset volatility without compressing returns.
House Democrats Just Forced xAI/SpaceXAI to Answer a Clean-Air Permitting Loophole—Turning 27–60 “Unpermitted” Gas Turbines Into a Federal Risk
A House Energy & Commerce ranking-member letter to SpaceXAI demands documents and site-visit access about Colossus 1/2 turbines alleged to be operating “without air permits,” explicitly describing an attempted dodge via “mobile sources.” For hyperscalers planning behind-the-meter gas capacity, the message is simple: once on-site turbines reach scale, permitting becomes a federal oversight issue, pushing the market mix toward utility PPAs (and away from regulatory arbitrage).
2026-07-28
Amazon cutting most Nova models turns “build your own frontier stack” into a cash-flow problem
Amazon is deprecating/winding down most of its in-house flagship “Nova” AI models (Premier, Omni, Reel, Canvas), moving to a smaller set of frontier priorities. The implication for investors: the cost curve of maintaining a multi-model frontier portfolio is steep enough that AWS can’t outspend licensing and platform-scale routing through providers like Anthropic.
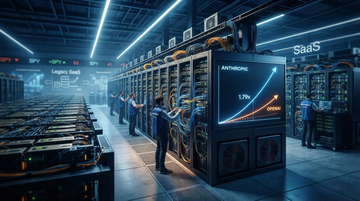
Anthropic’s ~$74.1B ARR run-rate turns “private mega-cap” into a measurable threat to public SaaS compounding in 2027
By July 2026, Anthropic is tracking at ~$74.1B in ARR/run-rate versus OpenAI’s ~$41.3B, about 1.79×, per ARR trackers. At that scale, even small shifts in developer mindshare and enterprise AI budgets can reallocate dollars away from public SaaS growth models—unless the incumbents’ distribution and platform economics keep outcompeting the model layer.
AT&T turns spectrum into fixed-wireless and AI backhaul capacity—an $23B deal that resets the 5G arms race
AT&T is buying 50 MHz of nationwide spectrum from EchoStar for ~$23B, with FCC buildout conditions that directly shape where and when the capacity shows up. The investor angle is less “more consumer 5G” and more “mid-band for air-interface + transport for AI”: Verizon’s recent dark-fiber AI backhaul model implies carriers are monetizing connectivity as compute-adjacent infrastructure.

Core Scientific’s AMD warrant lock turns 529 MW of ex-crypto capacity into an AMD-equity-aligned AI landlord bet
Core Scientific’s 15-year AMD AI infrastructure deal (filed via SEC 8-K on Jul 27, 2026) ties 529 MW of critical IT load to a warrant for up to 30M shares at a $23.47 exercise price, vesting per MW delivered. The structure shifts Core Scientific’s AI ramp from “power-only survivorship” to “AMD-aligned underwriting,” but the real investor question is whether AMD’s locked capacity scales into the deal’s up-to-2.5 GW expansion.
Microsoft’s MAI-Cyber-1-Flash + Project Perception Turns Cybersecurity into an AI-Stack Tollbooth
Microsoft is productizing defensive AI by launching its first in-house cybersecurity model, MAI-Cyber-1-Flash, and an agentic, multi-model defense system called Project Perception that enters public preview on August 3. The key shift is economic and architectural: Microsoft claims its cyber model can handle up to 90% of tasks with “almost 50% cost savings,” which lets it bundle lower-cost security AI compute into Azure and Microsoft Security workflows—raising the competitive bar for standalone security AI vendors.
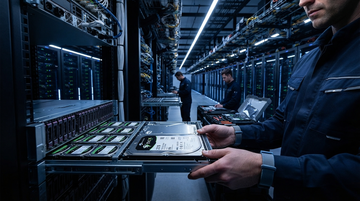
Seagate’s mass-capacity HDD sell-through turns AI storage into a capacity-cost cycle (and the underpriced leg is the drive tray, not the flash die)
Seagate used its earnings to confirm that nearline HDD capacity is already allocated through calendar 2026, with stronger visibility extending into 2027. That changes how investors should map the AI storage supply chain: the scarce, throughput-limited constraint for training data lakes and inference backlogs is increasingly mass-capacity HDD shipments (20TB+), which Seagate and Western Digital can monetize before NAND/SSD-only narratives catch up.

US core capital-goods orders just jumped—and “AI capex is fiction” now needs margin proof, not denial
The latest US core capital goods print shows orders up 0.9% in June and shipments up 1.9%, with shipments at their biggest gain in 4.5 years—i.e., spending plans converting into physical delivery. Investors who argued the AI capex cycle was only credit/FCF optics now face a harder burden: explain why demand shows up in durable-goods shipment data but fails to translate into returns at the equipment supply chain.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.