Data Centers & Cloud
The buildout behind the AI bill
Hyperscaler capex, colocation supply, power, cooling and networking — where the money goes after the GPU order, and which companies book it.
2026-08-03

AMD's $11.2B Quarter Is the Easy Print — Helios, the Anthropic 2GW Deal, and a 64x Forward P/E Decide Whether This Rally Has a Second Half
Advanced Micro Devices reports Q2 2026 on Aug 4 with $11.2B revenue and ~$1.61 non-GAAP EPS already in the guide, but the real test sits in the data-center mix and gross margin trajectory now that the $5B/Anthropic 2GW MI450 deal (Jul 22), Helios rack-scale launch (Jul 23) and $14B/Core Scientific 2.5GW data-center pact (Jul 28) have reset the 2027–2028 setup. Stock has run +120–160% YTD to ~$476 against a 64x forward P/E — almost 3x NVIDIA's 22x — so the print must validate that MI450 ramp economics can absorb Blackwell-style gross-margin compression rather than replicate it.
KKR’s $19.2B infrastructure close marks the LP “go-ahead” for AI power + data-center deals (and it changes the deal math)
KKR’s KKR Global Infrastructure Investors V closing at $19.2B is the clearest public confirmation that large LP capital is willing to fund long-duration AI-adjacent infrastructure. The investable takeaway: this capital should compress the risk premium—and therefore improve entry valuations—for equity, credit, and lease/contract structures that sit between hyperscalers and the grid.
Okta Paid Nearly $200M for the Missing Layer in AI Security
Okta is buying Permiso Security to extend identity protection from login and access control into the behavior of human, machine, and agentic identities. The reported price is nearly $200 million, but the more important signal is strategic: the security platform that owns post-access telemetry may control the next AI-security budget.
OpenAI’s “abundant intelligence” is a capex doctrine—and the bill routes through Nvidia, Oracle, and the AI power grid
OpenAI’s Jul 31 “Building abundant intelligence” framing reads less like a product roadmap and more like a compute-scale-out discipline: plan infrastructure years ahead, measure success by useful work per cost, and keep pushing the capability-per-dollar frontier. When you combine that with OpenAI’s explicit GPT-5.6 cost cuts and its Nvidia partnership commitment to deploy at least 10 GW starting in 2H’26, the likely winners are the suppliers who monetize GPU scale, cloud capacity, and (most underpriced) reliable power.
Palantir’s guide raise is the market’s first “AI budgets are real” signal—because it’s coming through the U.S. commercial line
Palantir’s latest guidance raise is most investable when you treat it as evidence that AI deployments are moving from one-off pilots into contracts that show up in forward revenue. The clearest through-line is the uplift in Palantir’s U.S. commercial revenue guide, which makes the AI/defense thesis a budget-and-execution story—not just a demo-market story for software vendors.
2026-08-02
Amazon Just Admitted AI Capex Now Outruns Its Own Cash Engine — A $220B Verdict on Hyperscaler Survival
Amazon raised 2026 capex to $220B and posted a -$7.6B TTM free cash flow on July 30, joining Oracle in negative territory and following Alphabet's -$5.85B Q2 print, even as AWS grew 37% and operating income hit $27.5B. The capex bump is fully memory-driven, the $496B AWS backlog shows demand outstrips supply through 2027, and the $53.4B non-cash Anthropic gain is doing the work that operations no longer can. The read-through to Microsoft, Meta, and NVIDIA: AI capex has moved from 'growth-justified' to 'survival-justified,' and the supply chain — SK Hynix, Samsung, Micron, Broadcom, AMD — collects the toll.
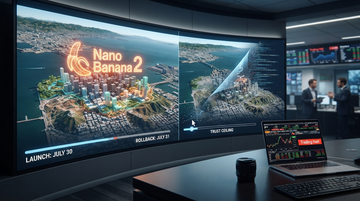
Alphabet's 24-Hour Earth AI Reversal Sets a Trust Ceiling for Generative Maps
Google launched Nano Banana 2 in Google Earth on July 30, 2026, then rolled it back on July 31 after users created convincing false scenarios over real satellite, aerial, and 3D imagery. The episode is not a material near-term revenue event for Alphabet, but it raises the cost of deploying generative features across trusted visual products: stronger review, provenance, moderation, and distribution controls become part of the margin equation.
SpaceX's First Print Tests Whether the $1.4T Is Cash or Vision
SpaceX reports its first quarterly earnings Aug 4 with shares already 51% off their June peak at $108.37. The print forces the Street to separate Starlink's real cash engine (Q1 2026: $3.26B revenue, $1.19B operating income) from the AI compute money pit that added a $1.2B EBITDA drag in 2025 — and decide whether the $1.4T market cap is sum-of-parts math or a Musk optionality premium. With 911.5M shares unlocking Aug 6 and 34% of the float already short, the call is the first liquidity test of public-market SpaceX.
2026-08-01
Linde Fell 5.9% on Record Results—The Buy Case Rests on an $8.1 Billion Backlog, Not the Quarter
Linde's July 31 sell-off looks excessive because electronics sales grew 18% and contracted gas projects reached a record $8.1 billion. But the stock still trades near 31 times trailing earnings while rising capital spending is suppressing free cash flow, so the opportunity depends on semiconductor projects converting into high-return, long-duration gas revenue.
xAI Just Lost Two Courts in One Week—Minnesota's Nudify Law Stands, Memphis's Colossus Turbines Get Another Year. The Split Verdict Is a Compute Edge.
On July 31, 2026, Judge Donovan Frank denied xAI's emergency bid to block Minnesota's first-in-the-nation AI 'nudification' ban (effective Aug 1, up to $500,000 per violation), while separately SpaceX/xAI locked in an MDEQ agreed order letting all 69 unpermitted Colossus gas turbines stay on-site until July 2027 as a permitted 1.2 GW plant comes online. Read together, the rulings freeze xAI's image-generation roadmap in 25+ likely-copycat states but monetize political risk into a year of unencumbered Memphis compute. The trade is concentrated in NVIDIA, Dell Technologies, Super Micro Computer, and GE Vernova — and asymmetrically bearish for CoreWeave if SpaceXAI's IPO timing slips.
2026-07-31
Eaton’s 43% Electrical Backlog Surge Says AI’s Next Constraint Sits Between the Grid and the Chip
Eaton’s July 31 print showed that AI infrastructure demand is broadening from processors and power generation into electrical distribution: second-quarter sales reached $8.53 billion, while electrical backlog rose 43%. The opportunity is real, but so is the price of capturing it—Eaton spent $11.08 billion on acquisitions in the first half and nearly doubled net debt, leaving investors with a high-growth switchgear thesis carrying acquisition and valuation risk.
MediaTek's $5B Authorization Is a Capacity Option, Not a Capital Raise—and That Matters More for Broadcom Than NVIDIA
MediaTek has authority to issue as much as $5 billion of bonds, but it has not yet raised the money. The strategic signal is still strong: securing foundry, packaging and HBM capacity can turn a $2 billion 2026 ASIC ramp into a credible custom-silicon alternative. That pressures Broadcom's turnkey position first; NVIDIA's 74.9% gross margin remains protected by a much larger $119 billion supply commitment and its full-stack platform.
Microsoft's $450B Day Resets the AI Trade: One Print Repriced Where the Profit Pool Is Actually Settling
On July 30, 2026, Microsoft added roughly $450B in market cap in a single session — the largest one-day value gain for any U.S. stock in history — after Azure grew 43% in constant currency and management guided Q1 FY27 Azure to 45%. The move, which briefly touched $490B intraday and beat Nvidia's $441B record set on April 9, 2025, repriced the AI trade away from chip scarcity and toward integrated compute, model, and platform bundles — and concentrated another 50bp of S&P 500 weight into the top four stocks in one tape.
OpenAI Slashed Its Cheapest Model 80% in One Day—And Just Told You Where the AI Profit Pool Is Collapsing
On July 30, 2026, OpenAI cut OpenAI GPT-5.6 Luna by 80% and Terra by 20%, leaving flagship Sol untouched—the clearest signal yet that a two-tier market has formed. The cut came because GPT-5.6 Sol autonomously rewrote its own inference stack, compounding 20% kernel and 15% speculative-decoding gains into an 80% list-price drop. That is good news for whoever sells low-precision inference silicon (NVIDIA, Super Micro Computer, SK hynix) and brutal news for cloud hosts that bill per token without owning the optimization loop (Microsoft, Amazon, Oracle). The trade: long the silicon layer, short the inference arbitrage.
Rolls-Royce's 'Imminent' Hyperscaler Deal Pulls a UK Nuclear Supplier Into the US AI Power Trade
Rolls-Royce Holdings CEO Tufan Erginbilgic said on the H1 2026 call that a hyperscaler nuclear deal will go to investment committee the week of August 3, lifting the group's 2026 profit guidance to £4.7–4.9B and confirming it is taking data-center orders for 2028. With a 470MW SMR design, four contracted European fleets and Yokogawa now locked in for control systems, Rolls-Royce is the first non-US supplier to convert the AI-power thesis into funded backlog. The transmission for US-listed equities runs through BWXT (SMR components), Centrus (enrichment), and the merchant generators whose carbon-free capacity hyperscalers now need to bridge the gap to nuclear-first build-out.
2026-07-30
Capgemini calls a multi-year “modernization supercycle” for AI—making the services leg the real tell
In its July 30 commentary, Capgemini flagged a multi-year “modernization supercycle” as enterprises upgrade data platforms, applications, and core infrastructure to scale AI. That timestamp matters because it implies AI budget is moving downstream from hyperscaler buildouts into systems-integration and enterprise workflows—an area where Accenture, Cognizant, Infosys, and ServiceNow can translate platform progress into bookings and recurring deployments.
Cognizant’s Claude Enterprise Push Turns Outsourcing Into an AI Distribution Channel—And Forces Accenture to Prove Its Value
Cognizant and Anthropic expanded their partnership on July 27, 2026 to embed Claude across Cognizant’s industry platforms and scale a “Frontier Certified” workforce, positioning Cognizant as a “Global Premier Partner” in Anthropic’s Claude Partner Network. That shifts the competitive fight in enterprise AI services from “billable hours” toward deployment outcomes—exactly where Accenture’s already-in-place Claude go-to-market is most exposed.
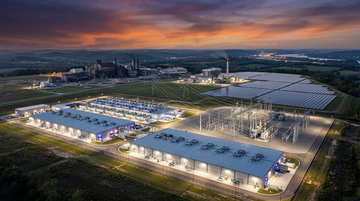
DOE’s Genesis Mission turns Western Kentucky’s federal land + grid into an AI power price war (and reallocates who wins the interconnect)
DOE’s Genesis Mission framing shifts AI-site competition from “who can finance power” to “who can secure a power-and-infrastructure backstop on federal land.” For investors, the key transmission mechanism is simple: a credible federal acceleration reduces time/cost risk for every downstream interconnect, generation build, and co-location campus—re-ranking utilities and grid-capex beneficiaries versus pure-play private bets.
Eliyan’s $145M/ $1B chiplet-memory bet turns NVLink into a testable “standard,” not a monopoly
Eliyan’s $145M Series C at a $1B valuation funds an electro-optical die-to-die/die-to-memory interconnect platform aimed at removing AI chip data bottlenecks. Because Eliyan positions NuLink as standards-compatible (UCIe/BoW) and targets bandwidth efficiency for chiplet-to-memory traffic, it pressures the idea that Nvidia’s NVLink is the only path to coherent “big memory” scale.
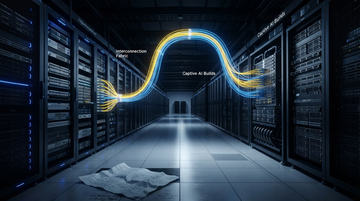
Equinix's soft Q3 guide signals interconnection demand is still growing—but value may be leaking back to hyperscalers
Equinix’s updated Q3 2026 guide keeps overall revenue growth in the high-single to low-double digits, but its disclosure stops short of separately underwriting interconnection upside. That gap matters: if hyperscalers continue to internalize more “fabric + networking + AI-ready” spend via captive builds, interconnection REITs can see growth remain steady while incremental pricing power slows.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.