Data Centers & Cloud
The buildout behind the AI bill
Hyperscaler capex, colocation supply, power, cooling and networking — where the money goes after the GPU order, and which companies book it.
2026-08-12

Sandbar’s Stream Ring reframes the AI wearable race: the “voice interface” wins only if inference cost and privacy both survive the finger
Sandbar’s Stream Ring bets that voice—not screens—will be the interface layer for mainstream AI wearables, and it tries to make the experience feel “always available” without becoming always-listening. The key investor takeaway is not the ring form factor; it’s how Sandbar structures the voice workflow to control privacy risk and reduce the on-device vs. cloud inference cost curve. If other wearable makers copy the same interaction economics, the winners may be the companies supplying edge compute, audio capture, and low-latency on-device inference rather than the model providers.
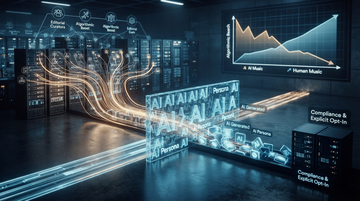
Spotify’s “AI Persona” Label Turns AI Music Into a Distribution Problem—Before UMG/WMG Can Even Standardize a Rulebook
Spotify will show an “AI Persona” badge on some artist profiles and, by default, exclude labeled AI Personas from editorial and algorithmic recommendations starting mid‑September 2026. The move creates a distribution firewall that changes how AI music wins audiences—shifting value away from platform reach, and toward compliance and explicit listener opt-ins long before labels align on standardized handling.
2026-08-11
Aug 10–14 AI-Infra Earnings Is the First “Build-vs-Buy Audit” for the Hyperscaler Cloud Race
Between Nebius, CoreWeave, and Super Micro Computer, investors get a rare same-window read on how much margin and contracted demand the AI infrastructure stack can actually monetize. The cluster matters because it turns the “data-center financing is the bottleneck” thesis into an earnings-testable build-versus-rent problem—starting with Nebius’s $7–$9B ARR target and >3GW contracted power, and flowing into CoreWeave’s and Supermicro’s ability to keep gross profit quality intact as 2027 backlog visibility becomes the market’s next currency.
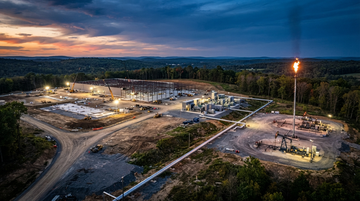
Alpha Compute’s Pennsylvania play reframes the AI data-center bottleneck: buying gas rights to beat the power queue
Alpha Compute ALP reportedly plans to buy Pennsylvania land plus gas rights to anchor a 55MW AI data-center campus—an unusually fuel-first approach to a project pipeline dominated by utility interconnect timelines. If the gas-rights control is real and bankable, it shifts “site control” from the grid side to the upstream fuel side, tightening the link between midstream gas operators and data-center power buildouts.
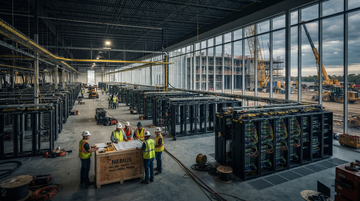
Nebius’s Vineland delay risk just re-priced the “build-fast, rent-fast” AI-server trade
D.A. Davidson’s 30% cut to its Nebius price target—citing Vineland, New Jersey buildout delays that may not complete this year—spotlights a new failure mode for neocloud economics: infrastructure timing, not GPU demand, is what can break revenue ramps. With Nebius already framing long-duration GPU delivery tranches that can affect performance/credits, investors should expect second-order repricing risk across other AI-compute landlords when project timelines slip.
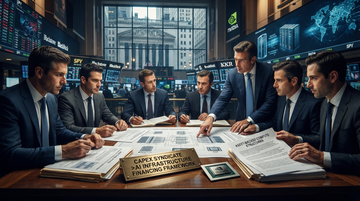
NVIDIA's $500B Wall Street syndicate reframes AI capex ownership: bankers—not GPUs—become the gatekeeper
A reported Nvidia partnership with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs, and KKR targets >$500B of third‑party financing for AI infrastructure, shifting the “capex stack” from Nvidia’s balance sheet to Wall Street underwriting. For investors, the key is not Nvidia’s chips—it’s how financeable-asset structure (and who prices risk) changes hyperscaler ROI, network/equipment throughput, and ultimately who captures the margin.
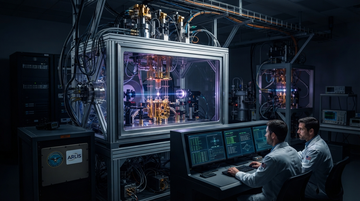
IonQ and ARLIS Are Building the DoD’s First Networked “Blind” Quantum System—Turning Quantum From Demos Into Deployable Mission Capability
IonQ’s newly awarded ARLIS contract is a meaningful step from “quantum access” toward a deployable, multi-node “blind quantum computing” system for national-security research. The investor implication is not just a government check—it’s whether quantum vendors can operationalize networked quantum with the security, control, and integration stack the Pentagon will repeatedly fund.
SEC exempted certain data-center securitizations—so the “ABS-like” buyer universe can expand overnight
A July 29, 2026 SEC staff determination says certain data-center securitizations are not “asset-backed securities” under Exchange Act §3(a)(79), removing a stack of ABS-specific disclosure and risk-retention requirements. For AI infrastructure financing, that effectively widens the capital pool for data-center project paper—shifting more build funding toward the balance sheets and financing channels most comfortable with operating-asset-backed structures like Equinix.
2026-08-10
Akamai’s Q2 proves edge security is the revenue bridge to AI inference—CIS growth is measurable, but the linkage is still the debate
In Akamai Q2 2026 results (quarter ended June 30, 2026), Security revenue grew 10% YoY to $604M while Cloud Infrastructure Services (CIS) grew 39% YoY to $99M—plus $2.8B+ in signed multi-year CIS contracts YTD. The company frames CIS growth as “AI infrastructure” positioning, but it did not quantify an explicit dollar “AI inference” contribution in the earnings materials reviewed, so investors must underwrite the security→inference attachment story more than they can spreadsheet it.
Anthropic turns $30B run-rate into a cyber “industry operating system” with Project Glasswing
Anthropic disclosed a revenue run-rate above $30B and simultaneously launched Project Glasswing, a large, partner-wide defensive cybersecurity effort centered on access to Claude Mythos Preview. The strategic signal isn’t just that Anthropic has “AI security capability”—it’s that Anthropic is trying to convert enterprise trust and regulated buyer demand into a repeatable, credit-funded product line that rides on cloud + security vendor distribution.
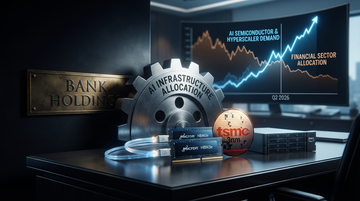
Appaloosa’s Q2 pivot bets the AI capex chain is still mispriced—and its “walk-away-from-banks” move tightens the signal
Appaloosa Management (David Tepper) reportedly rotated its Q2 2026 13F exposure toward AI infrastructure—highlighting a sharp add to Micron and a larger position in Amazon, with Taiwan Semi also pushed into core territory—while exiting bank holdings entirely. The investable takeaway isn’t “AI good, banks bad”; it’s that memory + foundry + hyperscaler demand signals can re-rate margins and capex intensity even when financials look safer on paper.
Atlassian's Cloud +31% delivers the AI “attach” proof the enterprise SaaS market has been waiting for
In Q4 FY2026, Atlassian posted $1.766B revenue (+28% YoY) with Cloud revenue at $1.213B (+31% YoY) and $4.8B in RPO (+44%). The key investor takeaway isn’t another AI feature demo—it’s that Cloud acceleration is happening alongside AI-led product momentum, which changes how investors underwrite the monetization timeline from “promises” to “line-item traction.”
CyrusOne’s 2027 IPO Signal Re-Ratings for “Independent” Data Centers—Because Lenders Are Making Financing a Valuation Variable
CyrusOne is preparing a potential 2027 IPO and has been in discussions with banks about roles, per Reuters. If that listing proceeds, it could force public-market re-pricing across the independent colocation/data-center stack just as tighter lender scrutiny makes leverage and refinancing risk a first-order valuation input.
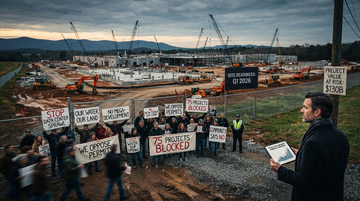
Community opposition is becoming a credit risk—so lenders are shifting data-center financing toward “permit-friendly” states
A Reuters report says lenders are now explicitly folding community opposition into project readiness and drawdown risk. That turns NIMBY/permitting friction into an underwriting variable, which can reorder which markets and operators get built first—and who pays the higher cost of delay.
The Real Bottleneck Isn’t Rack Cooling—It’s the IP Stack Behind the Thermal Interface That Makes AI Chips Work
Discovered Materials’ AI-driven “whack-a-mole” approach to finding cooler thermal materials highlights how fast the industry has to iterate to avoid thermal throttling. But the investable constraint is upstream: the process, deposition, and materials IP that can manufacture new thermal interface layers reliably at scale—where Applied Materials sits and where materials suppliers like Shin-Etsu Chemical and Tokyo Ohka Kogyo are built to monetize.
Fisher’s AI-Infrastructure Crowding Trade Is Real—But It’s the “Grid-to-Aircraft-to-Network” Link That Should Matter for Investors
Fisher Asset Management’s latest 13F (quarter ended June 30, 2026) shows aggressive positioning across AI’s “real economy” buildout—power and electrification via GE Vernova, aerospace platforms via GE Aerospace, and enterprise/data-center connectivity via Cisco Systems, alongside the usual AI compute core. The investable takeaway is not that AI exists—it’s that Fisher is paying up for the bottlenecks and replacement cycles that sit between AI demand and the supply chain that fulfills it.
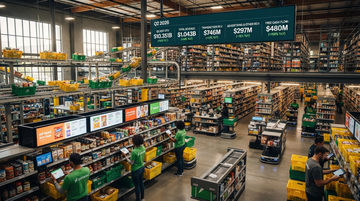
Instacart's ads are outgrowing transactions because grocery data still converts—so the retail e-commerce ad channel is “real demand,” not a funding-cycle artifact
Instacart grew Q2 2026 Advertising & other revenue +16% YoY while transaction revenue rose +13% YoY, with GTV +14% YoY—an uncommon retail pattern where ad-load expands without visibly harming order growth. The proof point is cash too: Q2 free cash flow surged to $480M (+156% YoY), making it harder to dismiss the ad acceleration as purely “spend-driven.”
The Trade Desk's real Q2 2026 ad-tech stress test wasn’t the 3% growth—it was executing a C-suite reset while guiding lower
In Q2 2026, The Trade Desk reported $715M revenue and non-GAAP EPS of $0.34—both short of what markets were looking for—and simultaneously disclosed an executive-leadership rebuild across CFO, CMO, and Chief Commercial roles. The key investor question isn’t whether growth missed; it’s whether the company can re-stabilize go-to-market and measurement execution as CTV/programmatic competition tightens.
2026-08-09
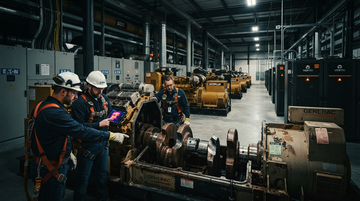
AI Power Spikes Are Forcing First-Order Capex Into UPS, Switchgear, and Generators—Turning Grid Reliability Into an OEM Supply-Line Shock
A new wave of AI power volatility is not just straining the grid; it is shortening the life and pushing the replacement cycles of batteries, generators, and cooling/power electronics inside data centers. That shifts the 2026–27 capex bottleneck from “build power lines” to “rebuild mission-critical power chains,” which can tighten supply and raise downtime-cost risk for operators and volume-forced production for OEMs like Eaton, Vertiv, and Generac.
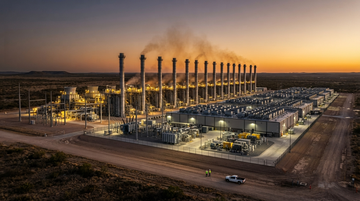
Amazon's Pecos County gas plant permit implies ~33M tons CO2/year—so AI data-center siting is starting to behave like a carbon-forward power project
A planned Amazon-powered AI data-center campus in Pecos County, Texas is tied to an on-site natural-gas power plant permitted to emit up to 33 million tons of CO2 per year. That shifts the hyperscaler AI-capex trade from “compute demand vs. electricity availability” toward a carbon-cost and regulatory-liability problem that can change project economics well before the campus starts full operations.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.