Data Centers & Cloud
The buildout behind the AI bill
Hyperscaler capex, colocation supply, power, cooling and networking — where the money goes after the GPU order, and which companies book it.
2026-08-17

Fabrinet will try to prove the 800G→1.6T ramp is shipping, not just selling design wins
Fabrinet’s Q4 FY2026 report is the first high-signal check from the ODM layer of AI optical supply chains: it turns optical module “qualification” into product shipments and margin. Investors should focus on whether optical communications revenue mix and gross margin expand together, and whether working-capital swings look consistent with a real production ramp into larger-capacity transceivers.
Groq’s $350M Pivot to a “Neocloud” Turns the Inference Margin Question Into a Land-Grab
Groq says it raised $350M in a Series A led by Disruptive, with planned NVIDIA participation, while scaling toward 200MW of inference capacity in 2027. The move reframes the neocloud war: instead of trying to win on silicon alone, Groq is positioning its LPU advantage to capture a larger share of the inference supply chain—pressuring chip-only economics and intensifying the NVIDIA/CoreWeave-style model in inference-first workloads.
2026-08-16
The unpriced line item in AI data-center finance: insurers/reinsurers are underwriting grid-interruption and residual-value “tails” that lenders can’t see
Insuring a $20B+ data-center build is not just a property issue—it’s a business-interruption and residual-value “tail-risk” problem shaped by grid strain and catastrophic concentrations. Swiss Re’s AI data-center risk research ties construction limits and BI severity directly to how insurers ration capacity, which can change project finance math even when property damage itself looks insurable.
The transatlantic bottleneck for AI isn’t fiber—it’s who gets to land it
Google’s new transatlantic subsea buildout shows how AI demand is now translated into physical route control: its Nuvem system targets ~384 Tbps across 16 fiber pairs and lands at the Atlantic “gateways” it chooses. In the U.S., FCC licensing and the ownership/architecture of cable landing stations then shape which ecosystems can absorb that capacity first—creating a new competitive edge for operators that sit closest to landing points like Equinix, and a new risk for traffic planners that assume capacity availability is purely a “cable count” problem.
Databricks’ $190B private ceiling turns Snowflake’s AI Data Cloud into a pricing test
Databricks has closed a $5B round at a $190B valuation, explicitly funding its Lakebase/Genie/“AI Gateway” roadmap—another step toward packaging enterprise data as an AI-ready product. For Snowflake, the market’s job is to answer whether Cortex AI and the Data Cloud can scale fast enough to earn anything like a private-market “ceiling” multiple, or whether the public stock is still discounting lakehouse-vs-warehouse migration risk.
2026-08-15
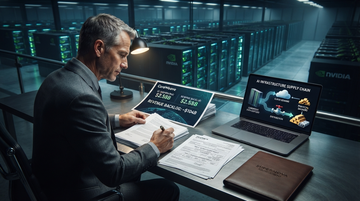
CoreWeave’s backers start distributing right after the $104B backlog surge
Two different investor/board-aligned Form 4 filings tied to Supernova Management (David J. Snyderman) show derivative call-option dispositions on Aug. 13, 2026—right after CoreWeave reported Q2 revenue of $2.575B and a ~$104B revenue backlog. The signal isn’t “panic,” but it is a first real test of the AI-cloud financing “toll booth” thesis: the money that funded capacity is visibly willing to monetize gains near the backlog inflection.
Gas-fired AI power is starting to look like a financing trick: a new forecast argues gas prices could soar above $10/MMBtu—hurting the turbine owners first
A new forecast highlighted in Aug 14, 2026 reporting argues natural gas prices could “soar above $10” per MMBtu in key U.S. hubs as hyperscaler-driven demand meets slower supply growth and higher LNG exports. If that happens, the first margin squeeze likely hits the companies that monetize gas-to-power hardware and contracted availability—while hyperscalers face higher power fuel costs and earlier pushback on expansion timelines.
Nvidia’s Ohio OpenAI guarantee just got smaller—what that says about who really funds the AI data-center build-out
Reports that Nvidia is pulling back its planned Ohio OpenAI financing guarantee are the first visible downgrade to the “Nvidia-as-lender” style of AI infrastructure dealmaking. The key shift for investors: less construction/funding risk stays on Nvidia’s balance-sheet narrative, and more of it reverts to hyperscalers, data-center developers/landlords, and the financing stack behind them.
2026-08-13
Microsoft's China retreat trades tiny revenue for compliance certainty—and signals the AI export-control regime is becoming structural
Microsoft weighing (and likely continuing) a China wind-down is less about demand than about making cross-border AI work legally predictable. With Microsoft explicitly flagging shifting U.S. AI export controls as an uncertainty factor in its FY2026 reporting, the investor takeaway is that hyperscalers will increasingly “partition” engineering and delivery—creating a durable Azure China vacuum for local demand while locking U.S. AI franchises into compliant lanes.
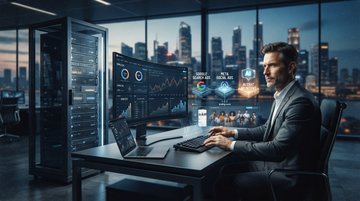
OpenAI’s “Testing Ads in ChatGPT” Turns the Free Tier Into a Live Pricing A/B Lab—And the Ad Market Just Got a New Distribution Toll Booth
OpenAI’s Aug 11 update confirms ChatGPT Ads are expanding beyond the U.S., with ads served at the bottom of answers for logged-in Free and “Go” users while Plus/Pro/Business/Enterprise stay ad-free. Mechanically, the program is built as a controlled monetization experiment—privacy-limited, topic- and history-matched, and measured primarily via aggregate ad engagement—meaning the real competition isn’t only for ad budgets, but for the right to arbitrate “intent” across the conversation. For investors, the signal is that OpenAI is converting the consumer AI funnel into a third ad-ecosystem alongside Google’s search ads and Meta’s social ads.
Vantage’s ~$100B exit talk turns AI data centers into a public valuation test for Equinix and Digital Realty
Vantage Data Centers is exploring an IPO around a ~$100B valuation and has also discussed a sale, with discussions still informal. Either outcome would pressure public “AI-ready” market pricing because it would anchor a new reference value for wholesale hyperscale land plus contracted capacity—re-rating Equinix and Digital Realty through capital-cost and replacement-value math, not just sentiment.
2026-08-12
Anthropic’s unreleased Claude jumped the “Riemann zeta” lower bound to 67.2%—and the moat is shifting from demos to math-proof cadence
Anthropic says an unreleased Claude research version advanced a long-standing Riemann zeta bound from 41.6% to 67.2%, then produced a Lean formalization that passed validation checks. The valuation implication is bigger than the headline: the lab is turning mathematical reasoning into something closer to a publishable, verification-ready workflow—exactly the kind of capability that justifies “frontier science” spending at $965B valuation levels.
Blacksmith’s near-10x re-rating doesn’t prove “AI tests AI” is a moat—yet it does prove CI cost and test latency became investable infrastructure
Blacksmith’s valuation jump (reported alongside its $10M Series A) is best read as proof that the software supply chain is being re-priced for an AI era: build, test, and feedback loops matter more than ever. The key investor question isn’t whether AI-generated code needs testing—it’s whether Blacksmith’s “CI for faster, cheaper, observable runs” can compound into a durable workflow lock when AI tools push code frequency up and failure modes change.
Bank of America’s $250B pledge reframes AI buildout finance as a bankable “industrial policy” product — and changes who gets paid
Bank of America says it will mobilize and deploy $250B by July 4, 2027 across digital, energy, and core US infrastructure. The investable takeaway isn’t just scale: the bank is positioning project finance + capital markets fees as a repeatable, measured pipeline—at a time when its own net interest income and investment-banking fees are already moving up. Investors should watch whether this “banking the buildout” focus increases earning-asset yield and fee share without loading up credit risk into a cycle that private credit has been dominating.
Cisco's FY27 guide effectively sets a “$9B+ AI order bar”—and it will be judged on revenue conversion, not backlog headlines
Cisco guided the market with an AI-networking demand runway that hinges on sustaining a high order pace into FY27. The key risk is that supply-chain and acceptance timing can push revenue recognition out of the quarter—so investors should treat “AI order proof” as a revenue-conversion test, with every miss resetting expectations for the entire networking trade.
CoreWeave proves $104B backlog can still lose $626M—because the AI cloud “toll booth” is a financing story before it’s a cash story
In its Q2 2026 update, CoreWeave more than doubled revenue to $2.58B and reported an approximately $104B revenue backlog, yet also posted a $626M net loss and guided full-year 2026 revenue to $12.4B–$13.2B. The gap implies that the economic conversion of signed commitments into cash is being delayed by build-and-finance timing—so 2026 looks like a construction bill, not a backlog monetization victory.
Lumentum turns “1.6T is coming” into Q4 revenue—making optical capacity conversion the new proof point investors should price
Lumentum’s fiscal Q4 2026 delivered a record $1.006B in revenue and $3.23 non-GAAP diluted EPS, while full-year revenue rose to $3.014B—nearly tripling year over year. The key signal is not just growth; it’s that optical networking hardware (including the company’s optical communications engine) is translating hyperscaler throughput plans into measurable quarterly dollars, giving the 800G/“1.6T” AI interconnect narrative a company-level anchor.
OpenAI’s Linux Desktop App Push Turns the Developer OS into the Last AI Distribution Frontier (and Bypasses Both Apple and Microsoft)
OpenAI’s ChatGPT desktop app is now in preview on Linux, bundling ChatGPT, ChatGPT Work, and Codex in a packaged install for mainstream Linux distributions. The strategic shift matters less because “Linux is niche,” and more because it attacks distribution control at the OS layer—where both Apple and Microsoft typically set rules—while pulling more developer workflows into the same subscription funnel.
Oracle’s Quantinuum quantum-cloud deal is a tell: hybrid AI compute beats a “quantum hedge,” and cost-out is funding the path
Oracle and Quantinuum plan to deploy Quantinuum Helios inside Oracle Cloud Infrastructure (OCI) to sell “hybrid quantum-AI” access rather than a standalone quantum bet. At the same time, Oracle’s latest 10-K shows large, AI-aimed restructuring charges—supporting a view that Oracle is cost-out funding the expensive, classical compute required while quantum matures.
River AI’s $1.1B Round Turns Custom-Model Training Into a Co-Op Between NVIDIA and AMD
River AI says it raised $1.1B in a round led by General Catalyst and AMP PBC, with strategic participation from both NVIDIA and AMD Ventures. The bigger signal isn’t just the money—it’s River’s pitch that enterprises can train and deploy custom frontier “open-weight” models via an API in minutes, forcing chip vendors to compete on not only hardware, but end-to-end training workflows.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.