Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-11-05

Snap Fell Over 10% on a Half-Percent Revenue Miss — the Answer-Engine Print Was Reddit's, Six Days Earlier
The market punished Snap for four million missing daily users, not for a broken ad business: Q3 revenue of $1,722 million missed the $1.73 billion consensus by roughly 0.5%, while ARPU of $3.48 actually beat the level implied by consensus, adjusted EBITDA of $383 million beat by 13.5%, and fourth-quarter guidance landed above the street. The genuine answer-engine evidence came six days earlier at Reddit, which disclosed Google search referrals falling by more than a million a week and guided daily uniques to a low-double-digit decline, and at Alphabet, which said AI Mode monetizes less per search than classical search. So the discovery budget was not taken; it was repriced, and Snap now sells the most repriced inventory on the board — upper-funnel brand ads, whose decline management attributed to weak consumer-goods spending. The deeper issue is that Snap is quietly changing the scoreboard, retiring daily users as its headline metric from Q1 2027 at the exact moment user growth halved, while trailing stock compensation of roughly $1.03 billion exceeds trailing free cash flow of $777 million.
Uber's 20% Bookings Beat Came With a 510-Bp Mobility Take-Rate Bill: Buying Drivers Now, Automating in 2028
Third-quarter results at Uber Technologies split cleanly: gross bookings of $59.82B, up 20%, and adjusted EBITDA up 31%, but Mobility gross bookings rose 18% to $29.51B while Mobility revenue fell 2% to $7.52B, taking the segment's revenue margin from 30.6% to 25.5%. Management blamed elevated fuel prices and thin driver availability in international markets, then shifted incentive dollars from riders to drivers to rebuild marketplace balance. The automation investors are underwriting is arriving on the supply side, not the demand side: third-party AI agents filled four rides in the quarter, while roughly 700 driverless vehicles by year-end and a 35,000-vehicle Lucid commitment carry the marketplace into 2028 — the year Waymo ends Uber exclusivity in Austin and Atlanta.
No Fed Put: November 5's 5.5% Nasdaq Rout Prices What Warsh's October Hold Does to AI Capex
On October 28 the FOMC held at 3.75%–4.00% on a 10–2 vote, upgraded the economy to 'expanding at a strong pace', left inflation 'elevated', and Chair Warsh told reporters that interest rates 'get in the cracks' and that AI investment is not insulated from monetary policy. Six days later Democrats took both chambers, and on November 5 the AI complex cracked: the Nasdaq Composite closed 5.5% lower, the Philadelphia Semiconductor Index fell 9%, the VIX jumped 71% to 28.3, and the 10-year Treasury rallied to 4.84%. Because roughly a third of hyperscaler capex is now debt-financed and heading to 35% in 2027, the marginal AI dollar must clear a credit market rather than a central bank — which sorts the trade into balance sheets that can fund the boom and balance sheets that need it to continue.
2026-11-04
Garry Tan's $200,000 Token Bill Prices an AI Employee Like a Utility — and It Breaks Seat Pricing
Y Combinator CEO Garry Tan said he spends $100,000 to $200,000 a year on model tokens to run AI agents, which is the first operating line anyone has put on the record for what vendors call an AI employee. At Anthropic's published prices that bill buys roughly 167 premium seats, about 225,000 finished agent jobs, or 1.47 times the median software developer's salary — so the unit of AI labor is consumption, not a licence. The pricing industry is already repricing to match: Microsoft switches new Microsoft365 Copilot Business licences to usage-based billing by default from December 1, 2026, and Salesforce sells the same agent by conversation or by Flex Credit. Margin migrates with it, from seat vendors to meters, memory and compute, while Chinese open-weight models deflate the price of a token faster than seat prices can fall.
73% of AI Political Ads Shipped Unlabelled: Meta, Google and TikTok Now Pay to Verify Ads They Didn't Make
More than $187 million of AI-generated political advertising ran in the 2026 midterm cycle, and 73% of the 220 ads tallied on Oct 15 carried no AI disclaimer at all — because a label costs an ad 31.5% of its click-through rate, per the NYU Stern study cited in the Interactive Advertising Bureau's August 2026 disclosure framework. With no federal mandate and roughly 30 inconsistent state laws, the verification bill has moved from the campaign to the platform: Meta now detects third-party AI creatives itself, Google keeps the check at the point of purchase and pushes attestation onto the advertiser, and TikTok declines the political ad market entirely. Democrats now control both chambers, so this becomes a 2027 hearing-risk line rather than a revenue event: the political book is 0.08% of Meta's trailing revenue, but it is 100% of the argument a congressional committee will have about what the platforms did and did not check.
AMD Doubled Data Center Revenue and Guided 2027 to +80%: The Market Paid 6.5% Because HBM4 Now Sets the Margin
AMD's fiscal Q3 2026 data center revenue jumped 97% to $8.55 billion and management guided 2027 revenue growth above 80%, yet the shares rose only about 8% the morning after the release and sit roughly 27% below their 52-week high. The argument is inside the guide: roughly $17 billion of December revenue at about 55% non-GAAP gross margin, down from 56%, because rack-scale Helios revenue carries memory, switches and power that AMD buys rather than makes. That scarcity rent is visible upstream, where SK hynix earned an 80% operating margin and Micron an 86.8% gross margin in the September quarter, while AMD turned only 4% of revenue into free cash flow. The second-source mandate is genuinely won, with five named hyperscalers running production racks, but the margin on it accrues first to the bottlenecks, not to the accelerator vendor.
Apple's 18+ Gate on AI Companions Is the AI Safety Rule Congress Still Can't Pass
Apple has done what Washington has not: from November 16, 2026, any App Store app whose virtual companion engages users in sexual or romantic content must carry an 18+ rating, with declarations due January 12, 2027, while the federal GUARD Act that would bar minors from AI companions still has no floor vote. Enforcement happens where installs happen — Apple's own adult-confirmation pipeline blocks 18+ downloads in Australia, Brazil and Singapore, and the Declared Age Range API hands apps an age signal — so the compliance bill lands on companion apps while Apple's first-party assistant, sold outside the App Store, carries no descriptor at all. Roblox has already run the same experiment, cutting daily users 9% and bookings 12% in a single quarter, which is the best available price tag on a permanent age gate. For investors, the binding constraint on AI consumer apps has moved from model capability to distribution eligibility, and whoever writes the eligibility rule captures the category.
$490 Million and Zero Sold: Ballistic's AI-Security Fund Is a Bet on Exit Math, Not a New Category
On November 2, 2026, Ballistic Ventures filed to raise $490 million across two vehicles — a $360 million third flagship and a $130 million Fund B — and both SEC notices report $0 sold with no first sale. The filings show a specialist crossing from seed into growth, not a generalist widening its mandate, and they expose the real constraint: the exit. Private AI-security marks are set by two listed comparables, with Island's $6.4 billion valuation implying about 32x revenue against CrowdStrike's 45.7x, while the rest of the listed security complex clears at 7x to 11.5x. For public shareholders, that gap decides who ends up buying Ballistic's winners — and who gets left holding the fund.
Big Tech Added $750 Billion After the Blue Sweep — Because Voters Just Made New Data Centers Harder to Build
Democrats took both chambers on Nov. 3, 2026, and the market split the AI complex along one line: platforms that already own compute gained roughly $750 billion in market value, while the companies that must build new data centers were sold hard. Voters in 36 of 36 counted local ballot measures backed restrictions on data center construction, Texas elected a governor promising an immediate moratorium, and the four largest hyperscalers now spend 91 cents of every operating cash dollar on capital expenditure. A permitting brake is therefore a pricing and cash-flow event for Amazon and Microsoft, which can charge more for compute they already own, and a revenue event for everyone downstream of a new site, from CoreWeave to Constellation Energy. This was not a deregulatory trade: Democrats closed off federal preemption of state AI law, so what the market bought was a capex brake, not a regulatory gift.
China's $120 Billion Mine-Stake Spree Is the Supply Chain Washington Cannot Screen
Chinese buyers have committed more than $120 billion to overseas mines and upstream processing since 2023, and $8.8 billion to mineral acquisitions in the first nine months of 2026 alone — on pace to be the highest annual total since at least 2018 — while Chinese firms are expected to double outbound mining investment over the next five years. None of that registers as an export control, a tariff line or a screened transaction, because Beijing is buying the right to own the metal rather than the right to ship it. The proof points are a Chinese antitrust condition bolted onto the $54 billion Anglo American–Teck Resources merger, a state-owned group circling the shareholder that holds a stake in MP Materials, and a Congolese government that just showed equity holders cannot outrun the host state. The investable question is no longer who exports the metal; it is who owns the mine, holds the offtake and can pull the licence.
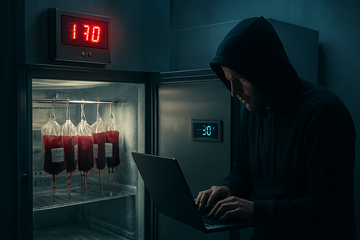
Hackers Just Took Europe's Blood Fridges: Cold Chain Is Now Critical Infrastructure and No One Owns the P&L
On the night of Nov. 1-2, 2026, hackers reached France's national blood service through the refrigeration contractor that maintains its cold rooms, and reprogrammed freezers holding blood products and plasma from minus 30 degrees toward 110, while the same technique stripped tens of millions of euros of grocery stock from seven European countries. The blood service lost nothing because its alarms and an on-call technician caught the drift; that near miss exposes the real problem: 12,976 refrigeration supervisory services are reachable from the internet, 54% of them on a single vendor's platform, and the same regulatory and insurance gaps leave the loss with whoever owns the cold inventory. Standard property cover excludes cyber-caused spoilage, standard cyber cover excludes physical damage, and EU reporting duties now force vendors to disclose exploited vulnerabilities without obliging them to fix hardware that is already end-of-life. For investors the read-through is narrow and dated: the beneficiaries sell verification and the new insurance class, while the P&L that absorbs an uninsured cold-chain loss sits with the fractionators carrying 200 to 420 days of refrigerated inventory on four to six times net leverage.
CVS Health's Drugstore Breakup Doesn't Unlock a Discount: At $180.5 Billion, the Market Already Pays for Both Halves
CVS Health will separate into two public companies, with the roughly 9,000-store pharmacy chain becoming CVS Pharmacy in the first half of 2028 — but the arithmetic does not support the sum-of-the-parts story. Valuing the health half on Cigna-like multiples and the chain on the 0.16x sales private equity paid for Walgreens puts the parts at roughly $125 billion to $194 billion against the $180.5 billion enterprise value the market already pays, so the separation transfers the valuation question to the Form 10 rather than resolving it. What is actually moving the stock is the operating line: adjusted EPS of $2.09 in the third quarter against about $1.63 expected, guidance lifted to at least $8.20, and $11.8 billion of trailing free cash flow against $63.6 billion of net debt at 4.85x trailing EBITDA.
Converted Jet Engines Won a $1.465 Billion Order — and the AI Power Queue Still Runs to 2031
Retired aircraft engines have become sellable power: FTAI Aviation disclosed a $1.465 billion initial purchase order for 25-megawatt gas turbine generator sets built from CFM56 engines, with more than 100 units under contract for delivery in 2027 and 2028. The channel adds almost no megawatts — it adds time, because new-build aeroderivative turbines are sold out through 2029 while a converted engine can deliver in 2027 and bridge a data center for five to seven years. That makes repurposed engines a bridge-power market rather than a power source, with roughly 1,000 retiring engines setting a hard ceiling on supply. The investable result is a new toll layer between aerospace and AI power, captured by whoever already holds the engine cores.
Democrats won both chambers on Nov. 3 — and the managed-care tailwind investors were trading was never there: Molina Healthcare's trailing EPS is minus $0.61
Democrats took the House and Senate on Nov. 3, 2026, putting drug-price controls, a reversal of the nearly $1 trillion Medicaid cut, restored exchange subsidies and a public option on the agenda — but the premise that this reverses a managed-care margin tailwind is wrong. The tailwind was never in the prints: Molina Healthcare lost $0.61 a share on a trailing basis through Sept. 30, 2026 and burned $535 million of operating cash in 2025, while its exchange premium revenue fell 46% year over year. What Democrats now control is a 2028 volume recovery for Medicaid managed care and a 2029 price floor for high-price pharma, with hospital payer mix the channel that has already hit the income statement and Cigna Group's pharmacy benefit economics the one that waits until 2028–29.
Disney's 20% Cost Target Is a Pricing Signal, Not a Demand Signal — and It Cuts Less Than Netflix's 6%
Disney is asking some managers for 20% cuts in annual costs across the TV networks and the motion picture studio, a move Bloomberg reported on Nov 2, 2026, with savings redirected into programming, technology and the parks. Treat it as a price, not a volume call: in the June quarter Disney grew Entertainment revenue 6% while holding segment costs flat at $9,757M, turning that into 64% segment operating income growth to $1,680M, so the cost base — not the audience — is the variable being reset. The headlines overstate how much Disney is cutting and understate what the number means: Netflix cut 6% of its workforce on Oct 14, Comcast booked a $1B-plus charge on Oct 22, and the merged Paramount Skydance group is chasing $6B-plus of savings, so 20% is becoming the sector's cost benchmark. The milestones are dated: fiscal 2026 results and the first post-cut headcount on Nov 17, 2026.
Fal.ai Doubled to $16B Without Paying a New Multiple: Media Inference Is Priced Now, and the Next Leg Goes Upstream
fal.ai's $1.3 billion Series F, announced Nov 3, 2026, values the generative-media inference layer at $16 billion — double April's $8 billion mark, and the same 16-to-22-times revenue multiple the market has paid in every round while the revenue behind it compounded from roughly $25 million to roughly $800 million in run rate. That makes the layer priced rather than speculative, which relocates the incremental dollar: fal bills per second of video and per megapixel of image but pays for GPU-seconds, so volume, not price, is the only variable that can grow. NVIDIA, which took equity in the December 2025, April and November rounds, is paid on the hardware and on the toll; the labs whose models ride on fal's rails trade at 0.9 to 4.2 times sales against the rail's 20 times.
Alphabet's K-12 AI Ultimatum Adds No Revenue — It Defends a $63.4B Search Line
On November 3, Alphabet said K-12 student accounts would lose Gemini, Gemini Notebook, Gemini in Classroom and Google Search until district administrators turned them on, then softened the policy after Senator Bernie Sanders and New York Mayor Zohran Mamdani objected — but only in a way that keeps AI-generated summaries inside search. The classroom is the one distribution channel where the default costs Alphabet nothing, so the policy trades free default behavior for consent to AI rather than for revenue. With rivals giving classroom AI away through 2027 and 2028 while Alphabet buys the compute with $51.36 billion of quarterly capex, the payoff is cohort behavior carried into consumer search; the risk is a remedy or procurement rule that reaches education distribution.
HP Inc Hired a GSK Cost-Cutter Into a Memory Cost Crisis: $1.8 Billion of New PC Revenue, Zero New Profit
HP Inc named Emma Walmsley chief executive on Nov 4, 2026, effective Jan 4, 2027, handing a restructuring veteran a problem she cannot restructure away: DRAM and NAND inflation has migrated the industry's margin upstream. In the September quarter, Personal Systems revenue rose about $1.8 billion year over year to $11.77 billion while segment operating profit was flat at $537 million, because unit shipments fell 16% and every dollar of growth was price and mix. Printing, a quarter of revenue at an 18.1% margin, now produces 57% of HP's segment operating profit, so the company the market buys as an AI-PC story is really a printing business with a shrinking PC attached. The shares rose 8.0% to $30.53 on the hire, 11% above the $27.52 consensus target, before the incoming chief executive has said a word about fiscal 2027.
Democrats Took the Senate, and SpaceX's $10 Billion Federal Contract Book Just Became a Re-Competition Risk — the Market Priced It at 7%
Democrats clinched the Senate and took the House on Nov. 3, 2026, and the market's opening verdict on SpaceX was a6.9% premarket drop after an earlier 1.8% postmarket slide. That discount is too small, because the channel running from a new Congress to SpaceX's income statement is not the $10 billion of contracts itself but the award process behind them — sole-source justification, conflict-of-interest rules, and who may give money to whom while holding a contract — stacked on top of a $41.1 billion annualized compute book assembled on the assumption of a friendly federal government. For Tesla, the same shift raises the odds that a merger needing 50% of all shareholders gets renegotiated rather than closed. The tradable conclusion is a governance discount on the federal franchise, not a re-rating of the launch business.
Novo Nordisk's tablet won 3.6 million U.S. scripts at about $174 each — and 2026 revenue is still capped at +2%
Novo Nordisk beat on the number that matters: the oral Wegovy did DKK 5,394 million in the third quarter of 2026, 68% above the second quarter and DKK 774 million ahead of the DKK 4.62 billion consensus, and full-year adjusted sales guidance was raised to -2% to +2% at constant exchange rates. The raise is a floor-raise, not a growth signal — nine months are already +2% at constant exchange rates, so the band leaves the fourth quarter somewhere between flat and about 14% below the year-ago quarter. The reason is price: U.S. tablet revenue works out to about $174 per prescription, below the $245 Medicare bridge net price and close to the $149 cash entry tier, so scripts compound into a shrinking revenue-per-patient pie while free cash flow guidance jumps DKK 15 billion at the midpoint to DKK 60-70 billion. The trade has repriced around that split — the market pays about 7 times trailing EBITDA for the manufacturer that has already reset its prices and about 31 times for the one still buying volume with a 15% price cut.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.