Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-10-24

Trump's Mortgage Order Cuts Paperwork, Not the 7.32% Rate — and Insurers Capture None of the Savings
President Trump's Oct. 22, 2026 order on housing costs starts a pilot to cancel mortgage insurance proactively and turns FHFA's title-acceptance pilot into a nationwide program, but the signed text limits the insurance pilot to loans written after it is established — a draft version industry estimates would have reached roughly 40% of borrowers with mark-to-market loan-to-value below 80%. The cash is therefore capped at $500 to $1,500 of closing costs per refinance and one insurance premium on a new vintage, while a 7.32% 30-year fixed rate costs a $400,000 borrower about $272 a month more than last year's 6.30%. Private mortgage insurers keep the premium on their legacy books, refinances are roughly 7% of title premiums, and refinances are 10% of MGIC's new insurance written, so the order is close to a non-event for the mortgage-insurance and title groups. What actually decides those balance sheets is the long end and the capital regime now in force, with PMIERs risk-based required-asset tables fully effective since Sept. 30, 2026.
Ukraine's Starlink Speed Cap Produced a Signature, Not a Contract — and the Sovereign Communications Spend Lands on Satellites, Ground Segment and Terminals
Ukraine's Ministry of Defence signed a letter of intent with ICEYE and Nokia on October 22, 2026 to explore a sovereign satellite communications capability, with a first Ukrainian satellite targeted for 2028 — but the document implies no ordering, discloses no price and commits no financing, making it a category-defining signal rather than a revenue event. The trigger was SpaceX's 160 km/h cap on military-grade Starlink in force since October 13 and still binding on October 23, an instruction Reuters traced to inside the White House, while Reuters reported the same day that no viable short-term alternative to Starlink exists for Ukraine. What changes is the addressable order book: governments that cannot tolerate a political kill switch now buy satellites, ground segment and terminals outright, and that money flows to the equipment and platform layer — Nokia's secure networking and terminals, ICEYE's spacecraft, IHI's industrial base — rather than to consumer capacity resellers. The honest conclusion is that this is a 2027–2029 buildout option for platform and ground-system vendors, and a non-event for anyone modelling Ukraine's connectivity bill in 2026.
Union Pacific Grew Revenue 15% — and 63% of That Increase Came From a Fuel Surcharge
Union Pacific reported operating revenue of $7.20 billion, up 15%, with adjusted EPS of $3.53 and a 59.1% operating ratio — and $598 million of the $953 million revenue increase came from fuel surcharge programs rather than from freight. Diesel at $6.28 a gallon is the real driver: shippers are moving long-haul freight off trucks and onto trains, which lifted intermodal volume 11% and intermodal pricing 14% while costing the railroad 140 basis points of operating ratio. That tension explains the decision that matters more than the headline — capital spending raised to $3.5 billion to pull 2027 work forward, into a fourth quarter where implied EPS growth decelerates from 16% to roughly 3%-7%, with the Surface Transportation Board's merger decision pushed into the second quarter of 2027.
Volvo's Autonomy Push Is Funded by a China Demand Hole: SEK 3.7 Billion Q3 Loss, SEK 8.9 Billion Cash Burn
Volvo Cars expanded its autonomy partnership with NVIDIA on Oct. 15, then reported on Oct. 23 a core operating loss of SEK 3.7 billion, EPS of SEK -1.63 and China revenue down almost 50%. The hole is structural rather than seasonal: Greater China deliveries fell 40.6% and the ICE base that carried the region's margin halved, while the units that survived were the low-priced electrified ones. With free cash flow at SEK -8.9 billion and net cash of roughly SEK 1 billion, a door-to-door autonomy stack is now being funded out of a shrinking revenue base, which turns seat economics into the real story. NVIDIA is insulated by scale, Mobileye and Autoliv are levered to the volume that just vanished, and Polestar is the second casualty.
2026-10-23
Airlines Absorbed $6.1 Billion of Extra Fuel in One Quarter: The Elasticity Test Says Cost Shock, Not Demand Shock
US carriers took roughly $6.1 billion of additional fuel expense in the third quarter of 2026 and pushed most of it into fares — airline fares rose 22.4% year over year in September and Southwest Airlines's average fare jumped 26.9% to $231.69 — yet United Airlines recovered only 72% of its $1.8 billion fuel increase and three of the four big carriers cut guidance. The mechanism matters more than the headline: airlines hedge crude rather than jet fuel, so the record $57-a-barrel crack spread passed straight through to fuel bills and was collected by refiners, where Valero Energy earned a $39.24-a-barrel refining margin and a record $6.8 billion quarter. Because capacity was rationed rather than demand destroyed — load factors moved half a point — this is still a cost shock, but the balance sheets that can carry it are unevenly distributed, and the same fuel spike is moving freight off trucks onto rails.
Blackstone Raised a Record $63.3 Billion and Sold Almost Nothing: AI Infrastructure Is Now a Fee Engine, Not an Equity Trade
Blackstone split its third quarter in two: record inflows of $63.3 billion and fee-related earnings up 6% to $1.572 billion on record assets of $1.368 trillion, against net realizations down 34% to $331.5 million and distributable earnings down 13% per share. Management says AI infrastructure is about 7% of assets — roughly $96 billion — and the highest-return area of the firm, financed through Google-backed Crux AI, a $9 billion junior tranche inside an $18 billion Anthropic package, and a data center portfolio heading to about 6 gigawatts. The mechanism is capital migration: with Meta running negative free cash flow and NVIDIA organizing more than $500 billion of third-party compute financing, the marginal AI capital expenditure dollar now clears through private credit and contracted leases rather than public equity. The market paid for the fee engine — the shares rose 6.2% on Oct. 22 — but they are still down nearly 30% in 2026, and the wealth channel that funds the buildout is rationed.
Canva's First Image Model Attacks Adobe's Seat Pricing From Below — and the Real Story Is Cost, Not Quality
Canva's in-house image model, released Oct. 22, 2026, lands fourth on the DesignArena leaderboard behind three OpenAI models — which is precisely why it matters. Canva built it because its own AI bill had broken the SaaS economics of a free-to-create design: cost of goods to serve went from cents per month to many more cents, and the company cut its 2026 growth guide from 30% to 20% while its backers marked it down 17% to $34.9 billion. The model is a margin repair that also creates a new supply line, because Canva now sells the same generation capability it used to rent from OpenAI, Alphabet, ByteDance and Meta through its Connect API and a coming MCP server. For investors the read-through is that creative software is unbundling from the seat to the asset: Adobe is absorbing inference inside its cost of subscription revenue (+24% year over year against 13% revenue growth), Figma has already halved the price of its own AI credits and warns in its 10-K that customers may move off seats entirely, and NVIDIA and Amazon get paid to serve whatever model wins.

Citigroup's Banamex Roadshow: The US$9 Billion Charge Is Certain, the US$3 Billion Proceeds Are Not
Citigroup is taking Grupo Financiero Banamex public in Mexico, and the analysts who flew into Mexico City in the week of Oct. 19 were building the pricing work for a January 2027 listing. The question for Citi's shareholders is not what Banamex is worth but what the exit converts into: roughly US$9 billion of currency translation losses that run through earnings in early 2027 while risk-weighted assets leave the balance sheet and the capital ratio edges up. With more than US$3 billion of proceeds targeted, the sale funds about one quarter of Citigroup's current buyback pace, which is why the January print — not the earnings — decides whether this exit creates capital or merely books a write-down.
GM Did Not Cancel a Magnet Plant. It Canceled the Contract That Made 90% of It Sellable
General Motors terminated its magnet supply agreement with Vacuumschmelze's South Carolina subsidiary on July 1, 2026, and the magnet maker is now arbitrating for damages over a contract that covered roughly 900,000 EV motors a year — about nine times GM's current run-rate US electric vehicle sales. The policy stack around this chain finances capacity, not customers: a $110/kg NdPr price floor, a $140 million annual EBITDA guarantee at MP Materials's 10X campus, and federal loan support for mines upstream. Energy Fuels paid the price for the missing customer, with a $1.9 billion acquisition whose purchase price now moves with the arbitration outcome.
Google's 1,070 MW Virtual Power Plant Turns PJM's $325 Capacity Cap Into an AI Capital Line
Google and power aggregator Voltus announced on October 22, 2026 an expansion of their PJM bring-your-own-capacity agreement adding 1,070 MW on top of the 100 MW tranche signed in June, with the contract running through 2040 — sixteen days after Constellation Energy agreed to supply Google 3,590 MW of new and existing nuclear power in the same market. PJM's July 2026 capacity auction cleared at the $325/MW-day cap and still came 6,831 MW short of reliability, so the demand-side leg is where hyperscaler power strategy now actually differentiates: Google buys the capacity obligation itself instead of waiting in an interconnection queue. For investors the read-through is that AI power cost is migrating off utility rate base onto hyperscaler balance sheets, with the money flowing to the aggregator and the device fleet — and with a performance risk that PJM's own 67% demand-response dispatch record quantifies.
Google Unblocks PyTorch on TPUs with “TorchTPU” makes inference demand captive
Google’s new open-source “TorchTPU” removes the engineering friction that keeps many AI apps pinned to Nvidia-style GPU stacks, directly targeting the inference workload routing layer. Combined with Amazon’s “TorchNeuron,” hyperscalers are shifting the battleground from GPU pricing power to the app-to-accelerator funnel—where independent startups lose flexibility and hyperscaler silicon wins utilization.
Baidu Reached Kazakhstan First — Pony.ai's Astana MOU Buys a Regulatory Template, Not Robotaxi Revenue
The Oct. 23, 2026 memorandum of understanding between Pony.ai, inDrive and NVIDIA makes Kazakhstan the first Central Asian testbed for a Chinese Level 4 stack, but the announcement discloses no vehicle count, no contract value and no launch date — and Baidu's Apollo Go got to Kazakhstan about five weeks earlier with a local partner. The value of Astana is not rides in a 1.7 million-person capital; it is a legal precedent for remote-operator-supervised driverless operation that inDrive can reuse across 1,200 cities in 47 countries, and a certification ground for NVIDIA's Hyperion safety stack. For investors, the tradeable markers are narrow: a Kazakh government agreement, the Nov. 18, 2026 third-quarter print, and whether the same Gen-7 hardware can pass a Western road test in London.
Microsoft's Diagnostic AI Beats Physicians 2.3 Times — and Hands the Liability to the Hospital
Microsoft published the most striking clinical-AI result yet on Oct. 22, 2026: its Diagnostic Orchestrator reached 83% accuracy on 304 New England Journal of Medicine case proceedings against 36% for generalists with reference materials, and 80% versus 47% on emergency-department presentations. But the benchmark prices the medicine — the cost of the tests ordered — and not the machine that orders them, so the savings accrue to payers and hospitals while the clinician who accepts the recommendation keeps the malpractice exposure The BMJ flagged in June. For investors the asymmetry is clean: Microsoft is paid on cloud consumption and clinical workflow long before anyone pays for the diagnosis itself.
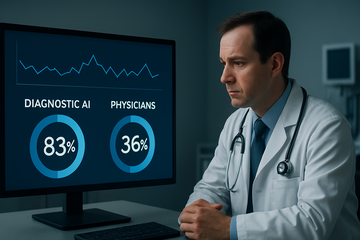
Microsoft's Diagnostic AI Beat Physicians 83% to 36% — and It Still Can't Be Sold, Deployed or Insured
Microsoft published the most aggressive diagnostic-AI result to date in Science on Oct 22, 2026: its Diagnostic Orchestrator (MAI-DxO) diagnosed 83% of 304 New England Journal of Medicine cases against 36% for generalist physicians with references, and 80.3% of emergency-department cases against 47%. The system has never run inside a clinic, ships as no product, and appears in no Microsoft revenue line — fiscal 2026 accounts still carry healthcare inside “Health and Life Sciences cloud services” with no separate figure. What decides deployment is law, not capability: California's SB 503 makes bias-mitigation documentation a compliance duty for clinical decision support from Jan 1, 2027, and Gov. Newsom's veto of AB 2575 on Sept 30 left clinicians who overrule AI without statutory cover. For investors the read-through runs through Azure rather than diagnostics: clinical AI is an Azure consumption story, a cost-of-care claim that squeezes testing volume downstream, and a capability bar that presses on AI-native vendors such as Lunit and iFLYTEK.
1Password Let AI Agents Log In Without the Password — Now the Human Approval Is the Product Nobody Priced
On October 22, 2026, 1Password shipped 1Password for Agents: an agent requests a credential, the user approves on their own device, and 1Password types the password and one-time code straight into the site’s login form, so the agent never holds the secret. That converts stored credentials into per-session delegated authority and makes the human approval the scarce, unmetered input in agent commerce. 1Password gives the consumer layer away free while more than 75% of its ARR comes from business, so the real trade is the enterprise machine-identity control plane where Okta, SailPoint, Palo Alto Networks and Microsoft already show bookings and ARR proof points. Courts and banks are writing the liability rules this layer needs — the Ninth Circuit has already held that an agent acting on a user’s instruction is the user — and delegated identity already carries private pricing at 15x–30x revenue, while the consumer approval step that makes it work remains unpriced.
OpenAI is renegotiating the AI funding ladder—because private marks are now the capex cycle’s earliest pricing
OpenAI is reportedly pushing a new ~$30B bridge round at a ~$1.25T valuation, below the ~$1.4T mark it was previously targeting. That downward private repricing matters for listed markets because it controls the timing—and credit structure—of the AI compute buildout upstream, before hyperscaler guidance catches up.
Free to Run, $410 Million to Build: Recursive's Flint Re-Prices Cloud Inference
Recursive's Flint, a 39.8-billion-parameter mixture-of-experts coding model released on October 21, 2026 under Apache 2.0 with no revenue gate, runs at more than 125 tokens per second on an M4 Pro MacBook Pro and was built in under four months with help from the company's automated research system. The leaderboard is the least important part: an unrestrictively licensed model running on hardware the developer already owns turns the price of an agentic coding token into a rounding error, while the same lab signed a $410 million compute deal with Amazon Web Services to build it. On-device inference relocates AI spending rather than removing it, so recurring per-token revenue migrates to the device while the lumpy training bill stays in the cloud and the fixed-cost layer in between gets squeezed first. We read that as value migrating toward compute, distribution and memory and away from the model layer, with CoreWeave carrying the clearest exposure and Microsoft the clearest transmission into a reported income statement.
SK hynix Shelved Solidigm's US IPO With ₩66.9 Trillion of Net Cash — the Memory Equity Window Moved to Shanghai, Not Closed
On October 23, 2026, SK hynix ended its review of a pre-IPO round and US listing for NAND subsidiary Solidigm, 79 days after the plan first surfaced, blaming capital market conditions. The balance sheet says the money was never the point: SK hynix held ₩88.0 trillion of cash and short-term investments against ₩21.1 trillion of total debt at June 30, 2026, and had already raised $26.5 billion on Nasdaq three months earlier. What closed was a valuation window, not a funding window — and the memory equity market did not disappear, it relocated to Shanghai, where CXMT closed its debut 465.8% above its offer price and YMTC filed to raise $4.6 billion. The consequence is narrow but sharp: the listed NAND pure-plays keep the pricing cycle without a new listing rival, the equipment chain keeps the order book, and the margin squeeze lands on the downstream storage buyers.
The Dirty Secret of Vietnam's Coal Boom: 25-Year Fuel Contracts Written Against a Narrowing Tariff Moat
Vietnam is importing 17-19 million tonnes of coal in 2026 and has begun locking fuel supply to state-owned plants through 2047, because coal now supplies 54.5% of its electricity and gas, hydro and the grid cannot close the gap on the same timetable. The hidden fault line is price elasticity: the same Iran-driven spike that made coal strategically necessary pushed Newcastle to $150 a tonne, and Vietnam's seaborne buying shrinks as prices rise. The listed consequences are narrow — Mitsubishi Corp and Doosan Enerbility bank contracted fuel and EPC revenue, Core Natural Resources is converting the demand into profit while Peabody Energy ships its first cargo from a cost curve it cannot yet cover, and the relocation premium behind the load is deflating, which is the bullish case for Jasan Holding.
Tesla's AI capex test failed: $4.7B of quarter spending didn’t match the market’s appetite—and cash generation weakened
In Tesla’s quarter ended Sep. 30, Tesla reported $4.7B of capital spending—well below the Street’s ~$7.9B expectation—and produced only $1.53B of free cash flow. At the same time, operating income fell to $718M as total operating expenses jumped $1.35B year over year and automotive regulatory-credit revenue dropped sharply, tightening the company’s ability to act as a high-conviction, open-ended “AI capex buyer.”
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.