Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-09-09

Amazon’s pregnancy-discrimination case reframes “HR risk” as a recurring cost line—so budgets, not reserves, decide the outcome
A proposed nationwide pregnancy-discrimination lawsuit against Amazon (plus a parallel New Jersey pattern-or-practice complaint) alleges failures in accommodation handling, documentation gating, and retaliation timing. The investor takeaway is less about any single settlement: it’s that platform-scale HR operations can convert compliance failures into ongoing, budgetable spend—training, investigations, policy redesign, and slower workforce throughput—showing up in how management plans for labor-cost “overhang.”
Anthropic's Safety Lead Puts A >10% Extinction Probability On The Product Going Into Its $2T IPO
Three days before Anthropic's public S-1 hits the SEC, its own alignment science lead publicly endorsed a junior researcher's resignation letter and pegged human extinction odds inside a decade above 10%. The $2T valuation pitch rests on a $30T TAM story built around 'safety as moat' — and Anthropic's IPO math now has to absorb a number its most senior safety researcher put on the front page.
AT&T's Stankey called the iPhone Duo 'not new' — that's the first honest carrier read on Apple's $1,999 bet
AT&T CEO John Stankey told the Goldman Sachs Communacopia conference on Sept. 9 that Apple's $1,999 foldable iPhone Duo is just another Android-style foldable in a category that has stayed niche — a verdict from the channel that controls postpaid upgrades. The Duo starts shipping Oct. 23 with Samsung Display as its exclusive OLED panel supplier and Foxconn handling assembly; Counterpoint and IDC both project Apple taking 20–25% of the global foldable market in its first year. The trade is whether Apple's direct-to-consumer financing pivot can bypass the carrier skepticism that just got stated out loud.
Barclays' 7,950 S&P 500 Call Is Wall Street's Most Honest Number—If the 10-Year Doesn't Wreck It
Barclays raised its year-end S&P 500 target to 7,950 from 7,800 on a technology-led Q2 earnings beat, but the 8.3% EPS upgrade (to $365) does more work than the 1.9% price upgrade. At 21.8x forward earnings, Barclays's call is cheaper than Goldman Sachs's 8,000 or HSBC's 8,100, yet it sits against a 10-year yield already 16 bps above HSBC's own end-2026 forecast and a Federal Reserve chaired by hawk Kevin Warsh while Treasury Secretary Scott Bessent doubles bond buybacks to suppress them. A projected $1.55 trillion in 2026 buybacks and an 86% Q2 beat rate hold the bid; the September 11 CPI print and the September 15-16 FOMC decision decide whether 7,950 is a stair or a ceiling.
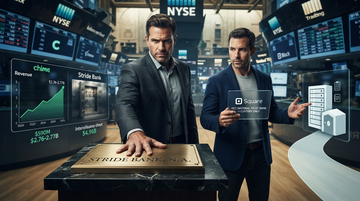
Chime's $590M Stride Bank Buy Ends the BaaS Era — and Block Just Showed the Other Path
Chime Financial is paying $590M in cash — roughly 1.5x tangible book — for its seven-year sponsor bank Stride Bank, N.A., converting a fee-laden BaaS dependency into a $4.96B deposit balance sheet that anchors $100M+ in net synergies and pushes 2026 revenue guidance to $2.76–2.77B. Hours later, Block filed for an OCC national trust bank — uninsured, no deposits, custody-only — proving the 2026 charter wave is bifurcating into deposit-rich acquirers and lean custody shells, with SoFi, Upstart and Nu Holdings all already mid-flight on the same playbook.
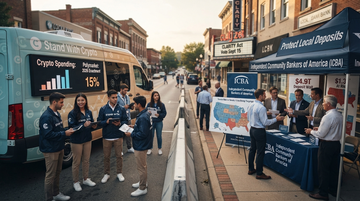
CLARITY Act Lobby War: Crypto's $190M vs Banks' $4.9T Deposit Wall — Who Wins the Next Decade of Payments
The fight over the CLARITY Act has moved from Washington hearing rooms to senators' home states during the August recess, with Coinbase-backed Stand With Crypto and the Independent Community Bankers of America spending through September 14 to lock the 60 cloture votes needed for the September 15 procedural vote. If the stablecoin-rewards guardrail survives, Circle and Coinbase keep a USDC yield flywheel that now drives 44% of Coinbase's revenue; if the bank-favored language wins, JPMorgan, Bank of America, Wells Fargo and Citigroup preserve a $4.9T community-bank deposit base at risk of losing $1.3T. The fight is binary — and Polymarket has2026 enactment at just 15%.
CVC Capital Partners hands power to co-CEOs—so watch how quickly its underwriting tightens (or loosens) in the US
CVC Capital Partners says Todd Sisitsky and Peter Rutland will become co-CEOs by Q1 2028, with Rob Lucas stepping back as CEO. The near-term investor question is not the résumé swap—it’s whether the new structure changes how CVC funds US mid-market deals, prices leverage risk, and times exits as record realisations and strong fundraising collide.
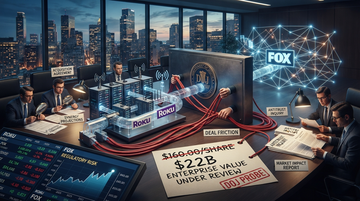
DOJ’s widening probe into Fox’s Roku deal targets TV streaming’s distribution choke point—investors should price higher “deal-friction” before they price synergies
The DOJ’s reported move to expand its antitrust inquiry into Fox’s planned acquisition of Roku turns a distribution merger into a subscriber-and-ad-economics risk test, not just a process headline. Fox is buying Roku for a stated ~$22B enterprise value and $160/share, with management banking on cost synergies and cash-flow accretion—so a prolonged, second-request style review threatens the timing and economics investors assumed for streaming distribution leverage.
GE Aerospace turns a castings bottleneck into margin: the $11.75B CPP deal targets durable supply, not just faster deliveries
GE Aerospace agreed to buy Consolidated Precision Products (CPP) for $11.75B, explicitly to expand “mission-critical” castings capacity that constrains engine output. The market will focus on whether in-house castings convert temporary shortages into sustained pricing power and higher adjusted cash flow—especially if the $200M expected net synergies translate into steadier throughput through the 2027 closing window.
GE Aerospace’s $11.75B castings move reframes delivery risk as a margin lever—because it attacks the bottleneck, not the symptoms
GE Aerospace agreed to buy Consolidated Precision Products (CPP) for $11.75B to expand mission-critical castings capacity and support a stated >30% airfoil demand outlook. The deal’s $200M net synergies target and “yield/productivity” capacity levers suggest the company is pricing delivery reliability as an income-stream, not a one-off cost. For the broader US aerospace supply chain, the signal is clear: constraint-heavy components are becoming vertical-integration targets, and OEM delivery-risk assumptions are likely to be repriced in contract negotiations.
Google’s €13B Finland push tests whether hyperscaler capex buys more than compute
Google says it will invest at least €13B in AI infrastructure in Finland across 2027–2028—alongside grid upgrades, clean energy and battery projects. The investor question is whether this shifts power, cooling, and network bottlenecks into durable leverage (higher utilization and pricing power), or whether it mainly extends a capex cycle that only tightens cash-flow pressure.
As Japanese yen firms and oil sprints toward $100, the “carry-to-energy” repricing starts with bank hedging, not equities
In late August/early September 2026, the yen strengthened while crude moved up on renewed Middle East supply-risk, tightening the FX-rate-oil triangle and pushing markets to price a more hawkish Japan path. The key for US investors: the first-order trade-through is likely via hedging and funding costs inside large dealers and banks, before it shows up as a clean rotation across equity factors. Exxon XOM and Chevron CVX offer the clearest direct linkage through oil pricing, while Toyota is the pressure-test for how FX translation swings can flow into earnings expectations.
Meta Turns “AI Chat” Into “AI Permissions” — and that shifts value toward the companies that price access, monitor actions, and prove audit trails
Meta’s new Muse “AI agent” goes beyond answering by connecting to other apps and executing actions after permission/approval. That changes the economics of AI from model quality alone to who controls cross-app permissions, action logging, and misuse prevention—raising demand for identity, security, and monitoring while pressuring ad/payout players exposed to higher compliance and fraud risk.
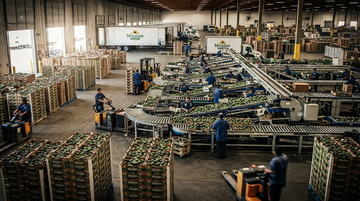
Mission Produce’s margin swing is explaining less “pricing power” than “fruit math”: a tape move built on timing can unwind fast
In Mission Produce’s recent results, the same margin line can swing while per-pound avocado pricing moves sharply—meaning the market’s focus on “good margins” risks over-crediting sustainable pricing power. The filings show gross margin changing alongside per-unit price and volume (and with industry supply conditions explicitly driving results), so investors should stress-test margins under a normalization of both fruit prices and customer/order timing.
Oil near $100 is noisy—what matters for US earnings is the shipping “war-risk premium” that keeps diesel expensive
As Middle East tensions flare, the first earnings transmission often shows up not in crude, but in the cost of moving and insuring barrels—via a higher war-risk premium tied to shipping routes. The latest Red Sea re-escalation pushed indicative war-risk premiums to about 0.75% of vessel value (from about 0.3%), a mechanical input into bunker and distillate logistics that can tighten US distillate balances faster than crude headlines.
OpenAI's 10,000-Agent Math Coup Is Really a Microsoft–NVIDIA Compute Story — and the Bill Lands on Six Stocks
OpenAI claims a 10,000-agent swarm solved a 90-year-old Navier–Stokes singularity in 88 hours using ~130 billion output tokens. The math, still unverified by Clay, reframes frontier-AI R&D as a 'PhD-per-watt' moat — and it lands on a tightly wired supply chain: Microsoft, NVIDIA, AMD, Broadcom, Oracle, and Salesforce. Investors should price the next leg of OpenAI compute spend before they price the prize.
OpenAI’s Samsung memory pact shifts the AI edge toward availability of constrained silicon, not just benchmark scores
OpenAI’s Stargate push is being underwritten by Samsung and SK hynix scaling advanced memory supply—specifically targeting up to 900,000 DRAM wafer starts per month. For investors, that reframes “AI performance” as a logistics and throughput advantage: the first supplier who can ship constrained memory capacity at the required cadence gains strategic leverage across the training-to-inference chain.
ServiceTitan’s “after-hours scheduling” story isn’t new revenue—yet—because its only hard KPI here is retention staying above 110%
ServiceTitan’s most concrete durability signal in the latest SEC filing is that net dollar retention remains >110% for the quarter ended July 31, 2026—evidence that existing customers are still paying more, not churning. However, the Sept. 8, 2026 after-hours move tied to a current report wasn’t matched with load-bearing, AI-scheduling-specific guidance language in the primary document excerpt available here, so “AI scheduling monetization” is still a working thesis rather than a confirmed financial driver.
Signet Jewelers' premium-jewelry slowdown looks more mall-linked than demand-wide
In Signet Jewelers’ latest reporting, same-store sales stayed slightly positive overall in FY26 but slipped in the key holiday quarter (Q4 FY26 SSS -0.7%). The guidance language also flags mall-traffic and customer-credit risks, implying the recent premium-jewelry softness is more channel/placement-driven than a broad affordability collapse—important for deciding whether discretionary weakness spreads to all retail categories.
Smithfield Foods' Q3 pork-loss guide makes the protein-cycle the next margin test—while packaged meats stay shielded
Smithfield Foods SFD guided a Q3 Fresh Pork adjusted operating loss of $70M–$90M, with total adjusted operating income of $115M–$175M—making this a clearly measurable protein-cycle margin reset, not a demand/marketing timing issue. The swing matters for the whole complex: when the “spread compression” phase hits, processors with heavier fresh exposure get the earnings timing pain first, while packaged peers with more pricing power decide whether they can offset it.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.