Data Centers & Cloud
The buildout behind the AI bill
Hyperscaler capex, colocation supply, power, cooling and networking — where the money goes after the GPU order, and which companies book it.
2026-09-11

2026-09-10
2026-09-09
2026-09-08
Anthropic’s Claude Fable 5.1 turns agent economics into the product: the near-term moat is “prompt-cache gravity,” not just model quality
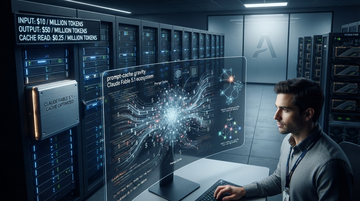
Claude Fable 5.1 and its pricing changes reframe agent rollouts around unit economics: Anthropic cut cache-read costs to $0.25 per million tokens (and describes up to ~45% savings for “highly agentic tasks”). The investor question for a future IPO-style narrative becomes whether enterprises will buy the compute-efficiency and enterprise-governance package—then scale agent usage faster than rivals can match.
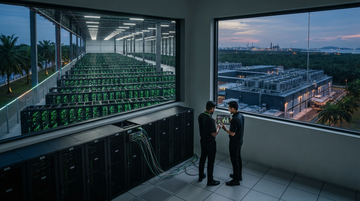
OpenAI's Malaysia Bet With Firmus Just Made the US Hyperscaler Capex Trade a Two-Region Story
Nvidia-backed NVIDIA partner Firmus has signed OpenAI as anchor tenant for two Malaysian AI factories, lifting its contracted capacity above 900 MW days before a planned A$15–30 billion ASX float. The deal is the first credible proof that the AI build-out has a second, cheaper geography: Malaysia's medium-voltage industrial power runs ~6.7¢/kWh against PJM's ~8.99¢/kWh in Northern Virginia, and PJM capacity prices have gone from $29/MW-day to $329/MW-day in two auctions. For Microsoft, Oracle, Amazon and Alphabet, the trade is no longer
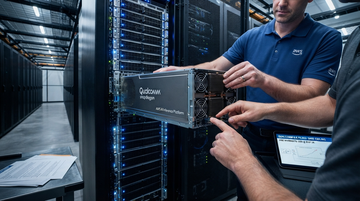
Qualcomm lands AWS: the $60B ceiling that turns the data-center story from slideware to balance sheet
Qualcomm's Sept 8 multi-generational AI silicon deal with AWS caps a potential $60B in chip purchases and grants Amazon warrants for 25 million shares at $161.26 — turning the data-center pivot from a slideware promise into a balance-sheet event. The warrant structure, vesting only with actual chip purchases, makes Amazon both customer and equity stakeholder, and reframes the AWS-Trainium versus merchant-silicon fight as a multi-vendor affair. Investors should track three things: when the next warrant tranche vests, how Amazon's inference silicon capex ramps, and whether Meta and Microsoft follow on the inference side the way they already have on the CPU side.
2026-09-07
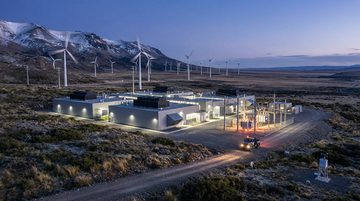
Why Patagonia’s Cold + Wind Can Break the Next AI Data-Center Siting Trade-Off—and Who Benefits
A Sept. 7 Reuters report says hyperscalers are probing Argentina’s Patagonia for mega data centers, attracted by wind-powered power economics and a cold climate that can lower cooling costs. The market signal isn’t just “cheaper kWh”—it’s that AI siting economics may shift toward places with both dispatchable-like renewable pricing dynamics and long runway for grid and generation buildout, reshaping who wins interconnect, power contracts, and capacity. Public investors should watch the listed power and data-center-adjacent names most exposed to these contract and buildout cycles.
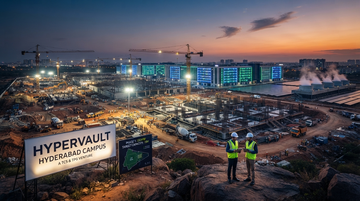
Tata Consultancy Services plants a 1GW hyperscale flag in Hyderabad—forcing a power-and-capex price fight across India’s AI data-center buildout
Tata Consultancy Services’s HyperVault is committing up to ₹70,000 crore (about $7.41B) for a purpose-built up to 1GW AI data-center campus in Hyderabad, backed by TPG—an inflection for India’s hyperscale build map. The move matters less for near-term IT services revenue and more for who controls “AI availability” in India: power, cooling, and capacity scheduling—where NVIDIA NVDA racks and Vertiv VRT infrastructure pricing flow downstream to hyperscale and colocation competitors.
2026-09-06
2026-09-05
2026-09-04
Ciena proves AI optical demand is real—and the next bottleneck shifts upstream supply, not downstream build
Ciena reported $1.67B revenue in Q3 FY2026, up 37% year over year, confirming its “AI-networking order-book” thesis for optical interconnect. The key investor implication is timing: when bookings accelerate faster than component throughput, near-term reads move from demand validation to supply availability across the coherent/optics test chain.
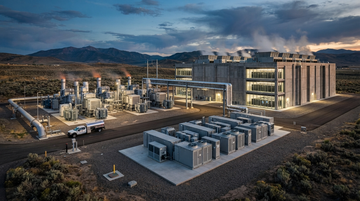
Crusoe’s $30B mark reframes AI data centers as a power-ownership business—boosting “turbine-to-rack” spillovers that scale-colo players can’t easily replicate
Crusoe’s reported $3B fundraising at a $30B valuation signals that investors will pay for AI capacity only when power reliability and grid stability are built into the product. The key tell is Crusoe’s disclosed path to on-site generation (via gas turbines) and power-conditioning/ride-through (via AI UPS), which shifts leverage from colocation landlords to power-integrators and equipment suppliers.
Nscale just locked in $3.5B of compute for humanoids—turning embodied AI into a tenant-class the “neocloud” playbook can underwrite
Nscale and Figure have signed a multi-year compute partnership starting in the second half of 2027, with an initial $3.5B commitment and an intent to scale beyond $6B. The deal matters less as robotics news and more as infrastructure proof: it extends Nscale’s contracted-revenue model (already validated by Anthropic-style compute deals) into a new physical-AI demand profile—low-latency, high-volume data pipelines tied to real-world deployment. That raises the stakes for how investors should think about compute capacity, utilization risk, and the timing pressure on incumbent robotics and cloud tenants.
Microsoft's Foundry channel turns OpenAI GPT-6 Astra into the enterprise monetization gate—before open access
OpenAI is rolling GPT-6 Astra out first through its Daybreak enterprise program (with ChatGPT tiering and API access following), while Microsoft promotes how OpenAI models are sold through Microsoft Foundry under Azure’s enterprise distribution mechanics. The tradeoff is clear: scarcity is being used to secure higher-trust buyers and tighter deployment controls—setting up Microsoft to capture more “resale-style” AI revenue economics per seat and per inference rather than waiting for universal open APIs.
2026-09-03
Dell clears the AI-rack “margin test” by proving its mix can expand—guidance lifts while gross and operating margin jump
Dell raised FY27 guidance after posting Q2 results that expanded both gross margin (20.9%) and non-GAAP operating margin (12.6%), alongside record AI-Optimized Servers revenue ($16.4B) and backlog ($95B). The key investor takeaway is not just AI demand—it’s that AI-related product momentum translated into structurally higher margins, directly undercutting the “AI revenue with lower-profit payoffs” narrative that has pressured Broadcom and Credo.
Can “neutral” colocation capture AI inference profit—now that Nvidia is building inside Equinix’s fabric?
Equinix’s Sept. 2, 2026 launch of “Equinix Inference Exchange,” anchored on Nvidia’s enterprise reference architecture and Together AI’s inference platform, is a bid to make vendor-neutral inference easier to deploy across Equinix’s interconnection layer. The investor question isn’t whether AI demand grows—it’s whether this packaging changes where the margin lands: colocation economics, or the hyperscalers’ walled-garden inference/distribution advantage.
Nscale’s $103B “contracted revenue” claim raises the hardest audit question in neoclouds: is it demand—or financing math?
Nscale’s Sep. 2 claim that it has ~$103B of contracted AI revenue ahead of a potential IPO is big enough to reframe expectations for the neocloud buildout. But without line-item, investor-auditable contract terms, that number is difficult to distinguish from circular financing dynamics—exactly the risk investors have been stress-testing in CoreWeave, where reported revenue backlog is massive even as losses persist.
The Software Recovery Map: AI “Attach” Now Shows Up in Guidance—Here’s the Winner/Laggard Split
Software’s rebound since the SaaSpocalypse bottom is real, but it isn’t uniform. The re-rating is separating layers that convert AI demand into measurable guidance (data platforms, CRM/enterprise suites, and process “execution” layers) from names still priced off a future miracle—visible in what companies actually forecast and how quickly they monetize AI-related usage.
2026-09-02
Brazil just made data-center capex cheaper—turning the US power bottleneck into a potential LatAm “second queue” for AI builds
Brazil’s Congress approved a special tax regime (REDATA) that suspends key federal taxes on data-center IT capex starting in 2026, reducing the cost and friction of deploying new capacity in-country. That timing matters because several US states are tightening approvals and interconnection timelines for new data centers, leaving AI demand to find the next buildable power queue. The twist for investors: the same Brazil-for-AI push is occurring alongside a new 25% US Section 301 tariff on Brazilian goods, which can raise cross-border equipment costs and complicate the economics of any Brazil-to-US supply chain.
Credo’s post-earnings drop tests whether copper interconnect cash flows can keep up with AI rack spend — even as Dell confirms demand is accelerating
Credo CRDO reported Q1 FY2027 results above the optics-friendly narrative investors were pricing, but the stock sold off sharply the next day. The key question for AI rack investors is whether the market is rotating from “copper rack capture” to “optics/other bottlenecks,” and whether Credo’s guidance supports that transition.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.